


Delta Air Lines (DAL) Could Be 25% Overvalued On Its Hyatt Loyalty Tie Up
Delta Air Lines (DAL) just agreed to a long-term loyalty tie-up with Hyatt Hotels that links SkyMiles and World of Hyatt, offering dual earning on flights and hotel stays for eligible elite members.
The Hyatt tie-up lands at a moment when Delta Air Lines’ share price has eased back, with the stock down 11.71% over the past month and 4.09% over 90 days. At the same time, the year-to-date share price return sits at 14.23% and the 1-year total shareholder return reaches 37.83%, pointing to longer term momentum that contrasts with the recent pullback.
Compare Delta Air Lines’ loyalty-driven story with other travel players by scanning our hand-picked 16 high quality undiscovered gems across the broader transport and tourism space.
The share price has given ground even as Delta Air Lines reports positive annual revenue and profit growth. Does that pullback now tilt the risk-reward balance toward buyers, or is the recent premium already generous?
Most Popular Narrative: 25% Overvalued
Against a last close of $78.89, the most followed narrative around Delta Air Lines pegs fair value closer to the low $60s, which contrasts sharply with Simply Wall St's cash flow based estimate and the current analyst optimism.
Atlanta's home airline still shines bright, and indeed brighter than most in a notorious low-margin, low-profit industry. In its Q2 trading update, Delta once again trounced analysts' expectations both top and bottom line, yet there's a snag: The legacy carrier comes from all-time high profitability. Hence, the risk distribution is skewed to the downside as long as there's no final and reliable re-opening of the Strait of Hormuz. That's why I stick to my valuation even in the face of shares trading some 38 per cent in excess of my calculations, because the latter is just that: excess. A current PE at some 14.5 and a forward PE at around 12 are simply too rich against this macro and geoeconomic backdrop. Delta would have to increase its current profit margins considerably to justify these multiples, which the author describes as a well-nigh impossible order. If you seek exposure to the airline industry, Delta is described as a mandatory buy without doubt, but not at these levels. Once the froth is out of the price, however, the author is certain to increase their holding.
See why 23 investors see Delta Air Lines as 25% overvalued.
Result: Fair Value of $63.21 (OVERVALUED)
Still, the bearish Delta Air Lines narrative could be shaken by any easing of tariff pressures or by a faster recovery in premium long haul demand.
Find out about the key risks to this Delta Air Lines narrative.
Another View on Delta Air Lines’ Valuation
That 25% overvaluation narrative differs from the Simply Wall St DCF model, which puts Delta Air Lines’ fair value closer to $230.56 per share and identifies the stock as materially undervalued at $78.89. If cash flows indicate one direction and sentiment another, which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
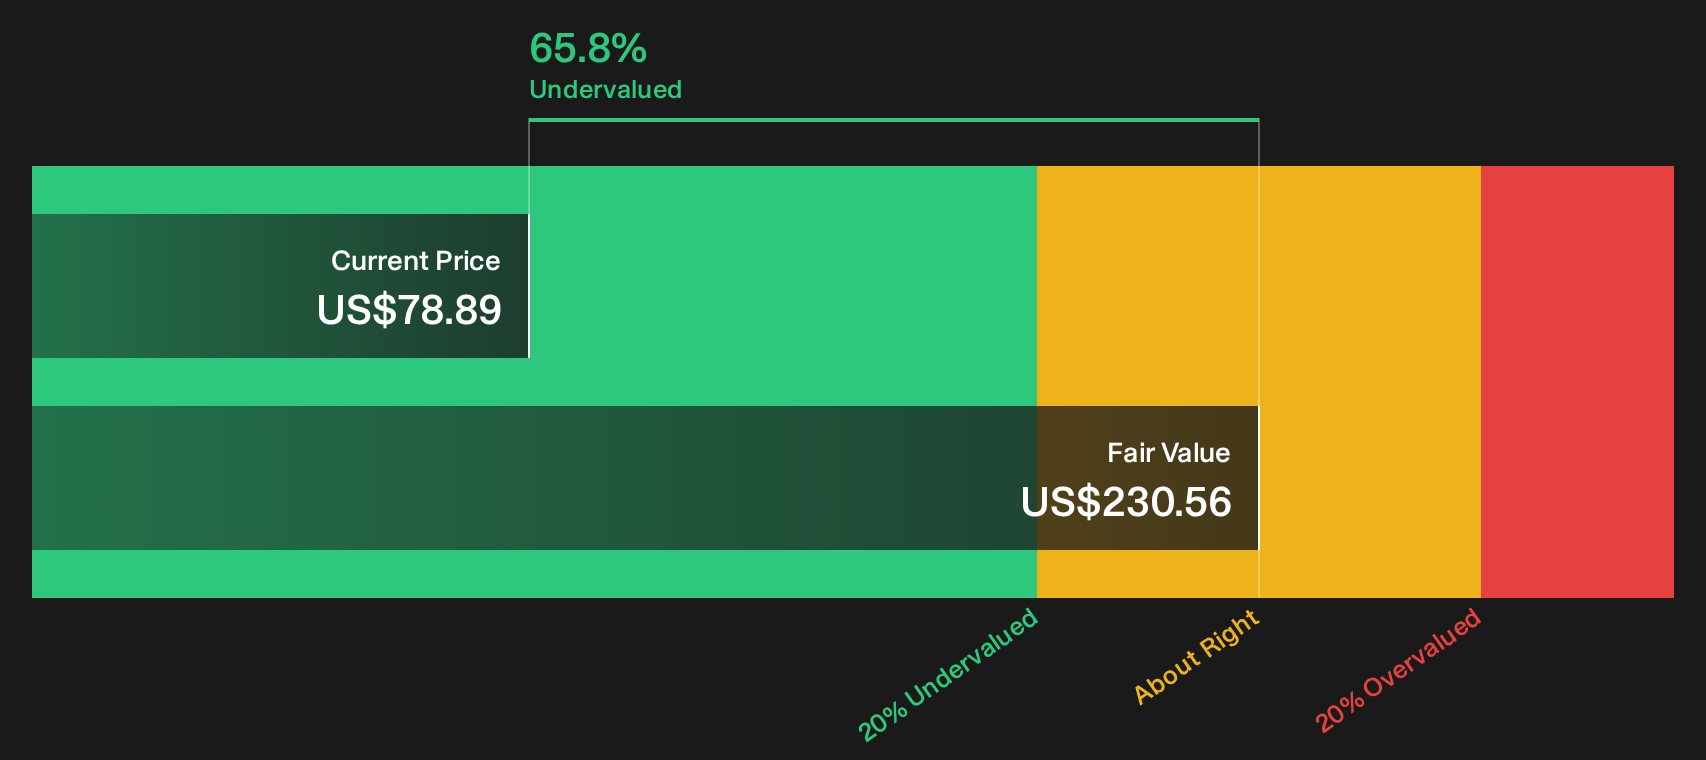
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Delta Air Lines for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Delta Air Lines’ valuation story are clear, so weigh those risks and rewards for yourself and act before sentiment shifts. To see both sides laid out in one place, review the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Delta Air Lines?
Do not stop with Delta Air Lines. Use the Simply Wall St screener to spot fresh angles, compare opportunities, and pressure test your own watchlist fast.
- Target potential mispricing by scanning a curated group of 34 high quality undervalued stocks before sentiment catches up.
- Strengthen your downside protection by focusing on a list of solid balance sheet and fundamentals (23 results) that can better handle tough conditions.
- Lock in income-focused opportunities by shortlisting a set of 6 dividend fortresses that already clear a 5% yield hurdle.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com