


Carnival (CCL) Stock Still Looks Like A Bargain After A 49% Run
Carnival has seen a sharp reset in its share price over the past year, even after a much stronger three year stretch for holders who stayed the course. With earnings now in sharper focus, the key question is whether the current US$22.11 price fairly reflects what the cruise operator is actually earning.
- The stock has gained 48.9% over the past three years, which puts real weight on whether those earnings now support that recovery.
- New offerings like the planned Carnival Tropicale ship and the Carnival Rewards loyalty program can influence how investors think about future booking volumes, pricing power and the timing of cash flows that underpin earnings.
- The analysts covering Carnival have run their own numbers. See what analysts think Carnival's shares could be worth.
The stock's next move may depend on whether Carnival's current earnings justify the price investors are being asked to pay today.
If the Carnival story has you weighing whether earnings justify the price, it can help to compare that same question across 34 high quality undervalued stocks.
Is Carnival Still Cheap on Earnings?
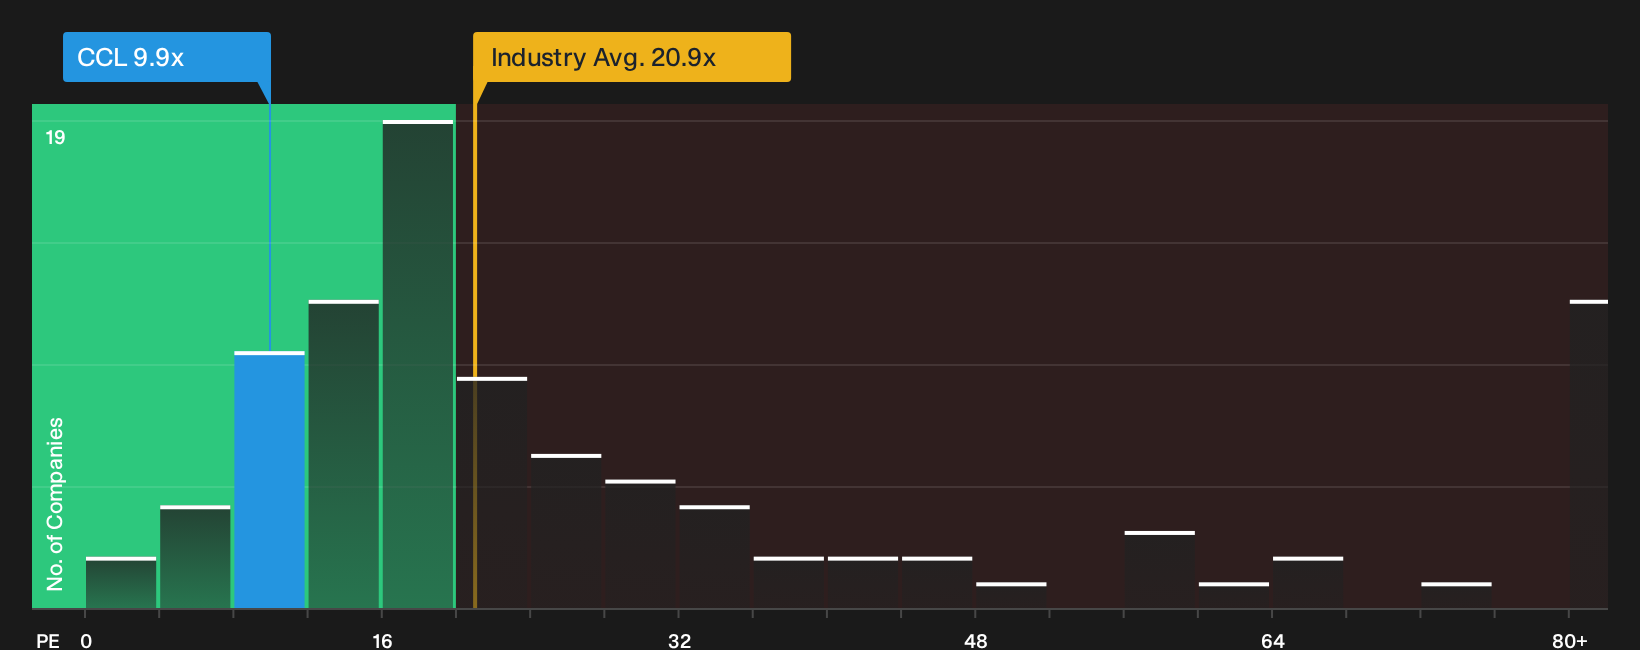
P/E fits Carnival because earnings have quickly become the main yardstick investors reach for when judging a recovery story. At a P/E of 9.9x, the stock trades at a clear discount to the wider hospitality group on 20.9x and also below the 16.5x peer average. On the internal model that links Carnival’s multiple to its growth profile, margins, scale and risk, the shares change hands below the level that framework would typically imply, which is why the stock screens as undervalued on earnings.
Because reservations for the Carnival Tropicale and the new Carnival Rewards program have focused attention on future demand, that gap between a 9.9x P/E and richer sector pricing matters even more for anyone weighing how much optimism is already embedded in the current share price. The multiple suggests the market is not paying up to the same extent as it does for many hospitality stocks with similar characteristics. Explore the numbers behind Carnival's P/E valuation.
The Carnival Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St’s Carnival Community page pick up where the P/E puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the shares to look meaningfully higher or lower than today’s valuation. Each scenario links its number to a concrete view of how Carnival's future profitability and risk profile might evolve, which you can revisit as fresh information comes through.
One of the top community narratives on Carnival: 38% undervalued
"Ongoing modernization of the fleet through programs such as AIDA Evolution and the addition of new, fuel efficient ships is improving guest experience..."
Discover why this Narrative puts Carnival at 38% undervalued.
One more Carnival clue worth checking before you move on
Carnival’s current P/E only tells you what the market is paying today. Analyst models sketch out where they think earnings and cash generation could land a few years from now. Explore where analysts expect Carnival to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com