


Does On Premises Splunk AI Change The Bull Case For Cisco Stock?
- Cisco Systems announced new Splunk AI features for self-managed environments, expanding its work with NVIDIA and AWS and adding Tokenomics tools that monitor AI agent performance, security guardrails, and AI spend across Cisco’s observability and security portfolio.
- The move pushes more AI, observability, and agentic SOC capabilities directly into customer data centers, which could influence Cisco’s mix of infrastructure, software, and security revenue as enterprises scale AI workloads on existing networks.
- This development examines how Cisco Systems’ investment narrative is affected by bringing Splunk AI on-premises through the Cisco AI POD platform.
Cisco Systems Investment Narrative Recap
Cisco Systems appeals to shareholders who buy into a story where AI networking, security, and observability gradually become a larger share of a US$63.3b hardware centric business. In the short term, the main swing factor is execution on large AI infrastructure orders and Splunk integration. The new on premises Splunk AI features support that push but do not radically change the near term picture on their own.
The biggest risk still sits in dependence on a small group of hyperscale buyers and pressure from lower cost and open networking rivals. If AI orders slow or security and software traction stalls, the transition to higher margin recurring revenue could look slower while Cisco absorbs Splunk costs and complexity.
The Cisco AI POD for Splunk looks like the most relevant recent announcement. It ties AI networking hardware, NVIDIA acceleration, and Splunk’s software into a pre validated stack that can sit in customer data centers, private clouds, or air gapped environments. That gives Cisco a concrete product to point to when discussing AI infrastructure demand.
For catalysts, the key question is whether enterprises adopt this stack at scale. Broad adoption would support Cisco’s AI revenue goals and reinforce its recurring software shift. The same product also introduces risk. If customers prefer cloud native or open alternatives, hardware pull through, software usage, and observability uptake from this Splunk rollout could end up more limited than bulls expect.
Cisco Systems’ current consensus roadmap points to US$83.4b in revenue and US$20.3b in earnings by 2029, based on analyst assumptions of 9.6% yearly top line growth and an earnings increase of about US$7b from US$13.3b today.
Uncover why Cisco Systems' fair value indicates a 24% potential upside to its current price, which could narrow quickly.
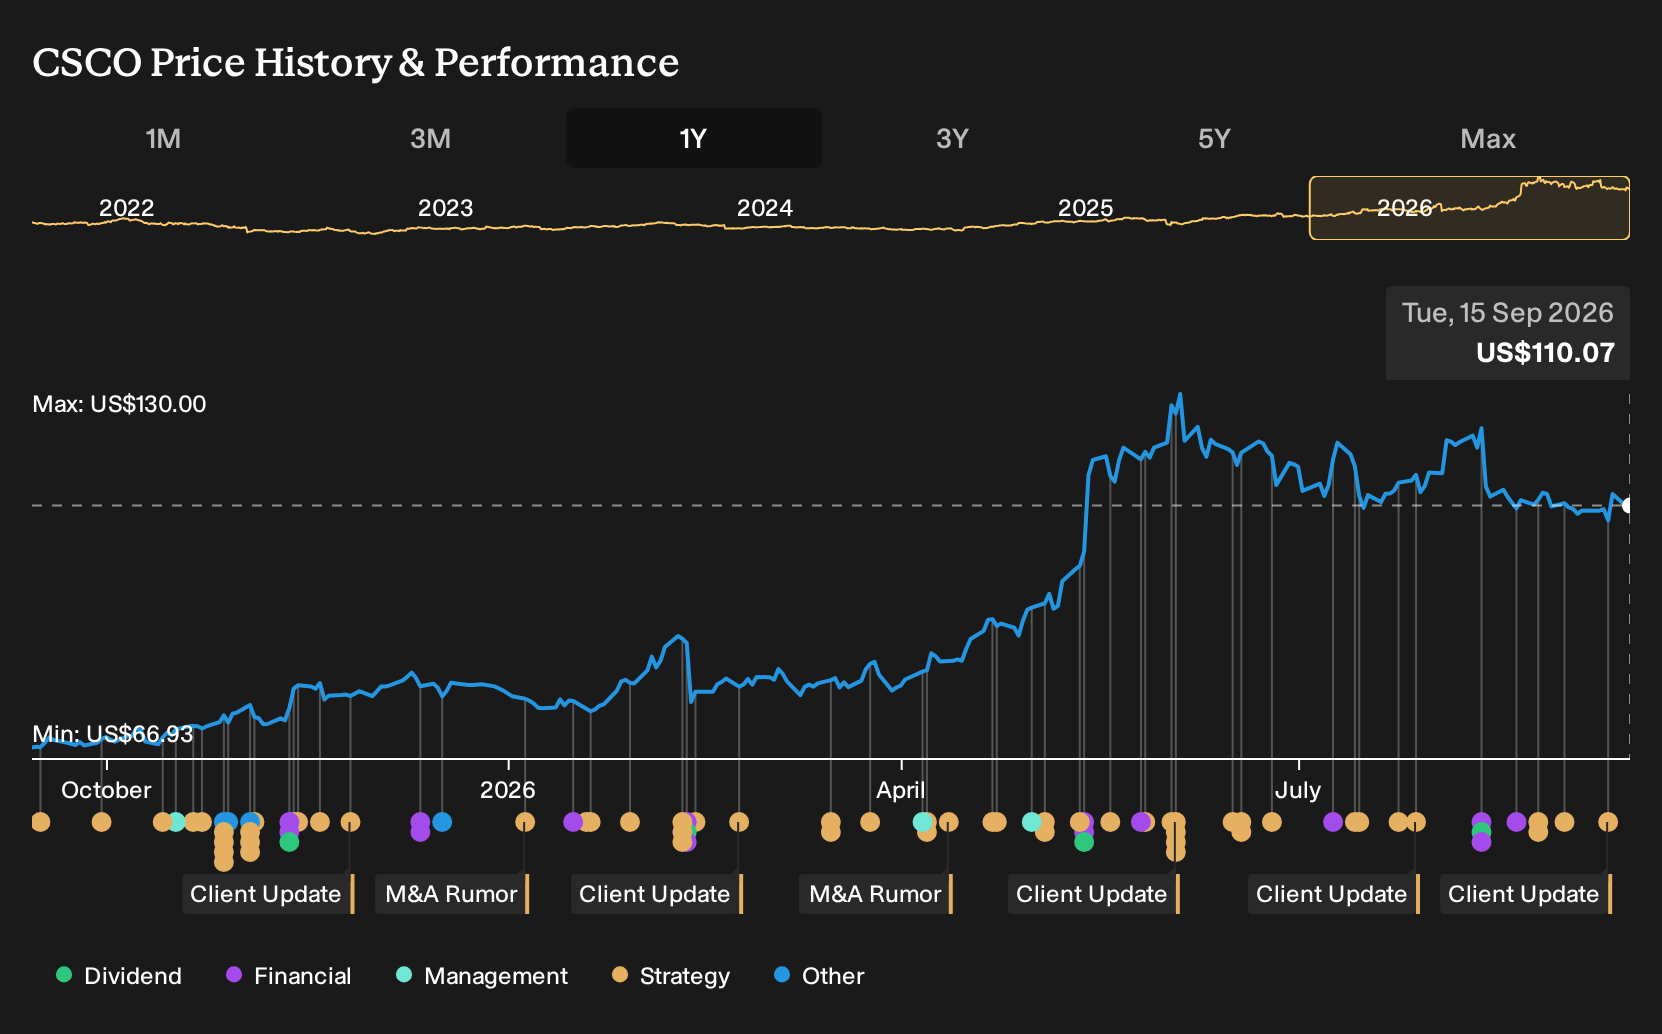
Exploring Other Perspectives
Some of the most optimistic analysts focus on AI infrastructure demand as the swing factor for Cisco Systems. Before this Splunk AI POD news, the bullish camp was already modeling revenue of about US$90.6b and earnings near US$23.0b by 2029. You can compare that view with more cautious forecasts and decide which storyline feels closer to your own expectations.
Explore 6 other Cisco Systems fair value estimates, including one that suggests up to 40% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cisco Systems research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Cisco Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cisco Systems' overall financial health at a glance.
Looking For More Ideas Beyond Cisco Systems?
Once you have a handle on Cisco Systems and its AI story, it can help to widen the lens and compare it with other opportunities that share some of the qualities you care about most.
- If resilience is a priority, focus on businesses that pair steady operations with muted volatility through our screener of 11 resilient stocks with low risk scores.
- For investors hunting for value, use the curated set of 34 high quality undervalued stocks to spot companies where fundamentals and price look out of sync.
- Those who care most about financial strength can zero in on companies with robust balance sheets using the list of solid balance sheet and fundamentals (23 results) and see which ones deserve a place on a watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com