


Asian Market Gems: Promising Penny Stocks For September 2026
As the Asian markets navigate a landscape marked by geopolitical tensions and fluctuating oil prices, investors are keenly observing opportunities that may arise amidst these challenges. Penny stocks, despite their somewhat outdated moniker, continue to attract attention for their potential to offer growth opportunities in smaller or emerging companies. This article will explore three such stocks that not only demonstrate financial resilience but also present intriguing possibilities for those looking beyond traditional investment avenues.
Underneath we present a selection of stocks filtered out by our screen.
YesAsia Holdings (SEHK:2209)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: YesAsia Holdings Limited (SEHK:2209) is an investment holding company that trades in Asian fashion, lifestyle, beauty, cosmetics, accessories, and entertainment products with a market cap of HK$1.55 billion.
Operations: The company's revenue is primarily derived from its YesStyle B2C segment, which generated $399.54 million, and its ABW B2B segment, contributing $153.70 million.
Market Cap: HK$1.55B
YesAsia Holdings has demonstrated robust financial health, with a high Return on Equity of 29.4% and earnings growth averaging 53.2% annually over the past five years. Despite its earnings growth slowing to 24.3% last year, it remains well-positioned financially with short-term assets exceeding liabilities and more cash than debt. Recent results for the first half of 2026 showed revenue increasing to US$301.51 million and net income rising to US$18.33 million, driven by strong revenue performance and effective cost management strategies that improved profitability despite a one-off expense related to organizational changes.
- Get an in-depth perspective on YesAsia Holdings' performance by reading our balance sheet health report here.
- Learn about YesAsia Holdings' future growth trajectory here.
Tian An China Investments (SEHK:28)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: Tian An China Investments Company Limited, along with its subsidiaries, is involved in property development and investment services across the People's Republic of China, Hong Kong, the United Kingdom, and Australia, with a market cap of approximately HK$4.92 billion.
Operations: The company's revenue is primarily derived from its operations in healthcare (HK$1.62 billion), property development (HK$769.91 million), and property investment (HK$563.16 million).
Market Cap: HK$4.92B
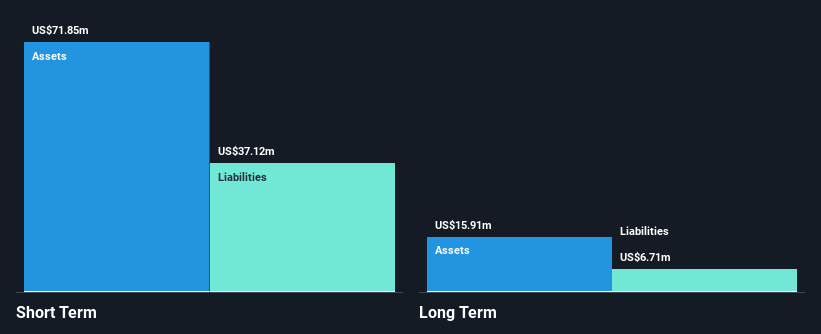
Tian An China Investments faces challenges typical of penny stocks, with recent earnings showing a significant decline in revenue to HK$1.67 billion and a net loss of HK$446.03 million for the first half of 2026. Despite this, the company's financial structure is stable; short-term assets exceed both short and long-term liabilities, and its net debt to equity ratio remains satisfactory at 2.7%. The management team is experienced, averaging 7.2 years in tenure, while the board boasts an average tenure of over two decades, indicating seasoned leadership amidst current profitability issues exacerbated by a downturn in the Mainland property market.
- Click here to discover the nuances of Tian An China Investments with our detailed analytical financial health report.
- Gain insights into Tian An China Investments' past trends and performance with our report on the company's historical track record.
China High Speed Transmission Equipment Group (SEHK:658)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: China High Speed Transmission Equipment Group Co., Ltd. operates in the manufacturing and sale of gear transmission equipment primarily for wind power generation, with a market cap of approximately HK$1.81 billion.
Operations: The company generates revenue primarily from its Wind and Industrial Gear Transmission Equipment segment, which accounts for CN¥16.98 billion, and also from its Rail Transportation Gear Transmission Equipment segment, contributing CN¥292.70 million.
Market Cap: HK$1.81B
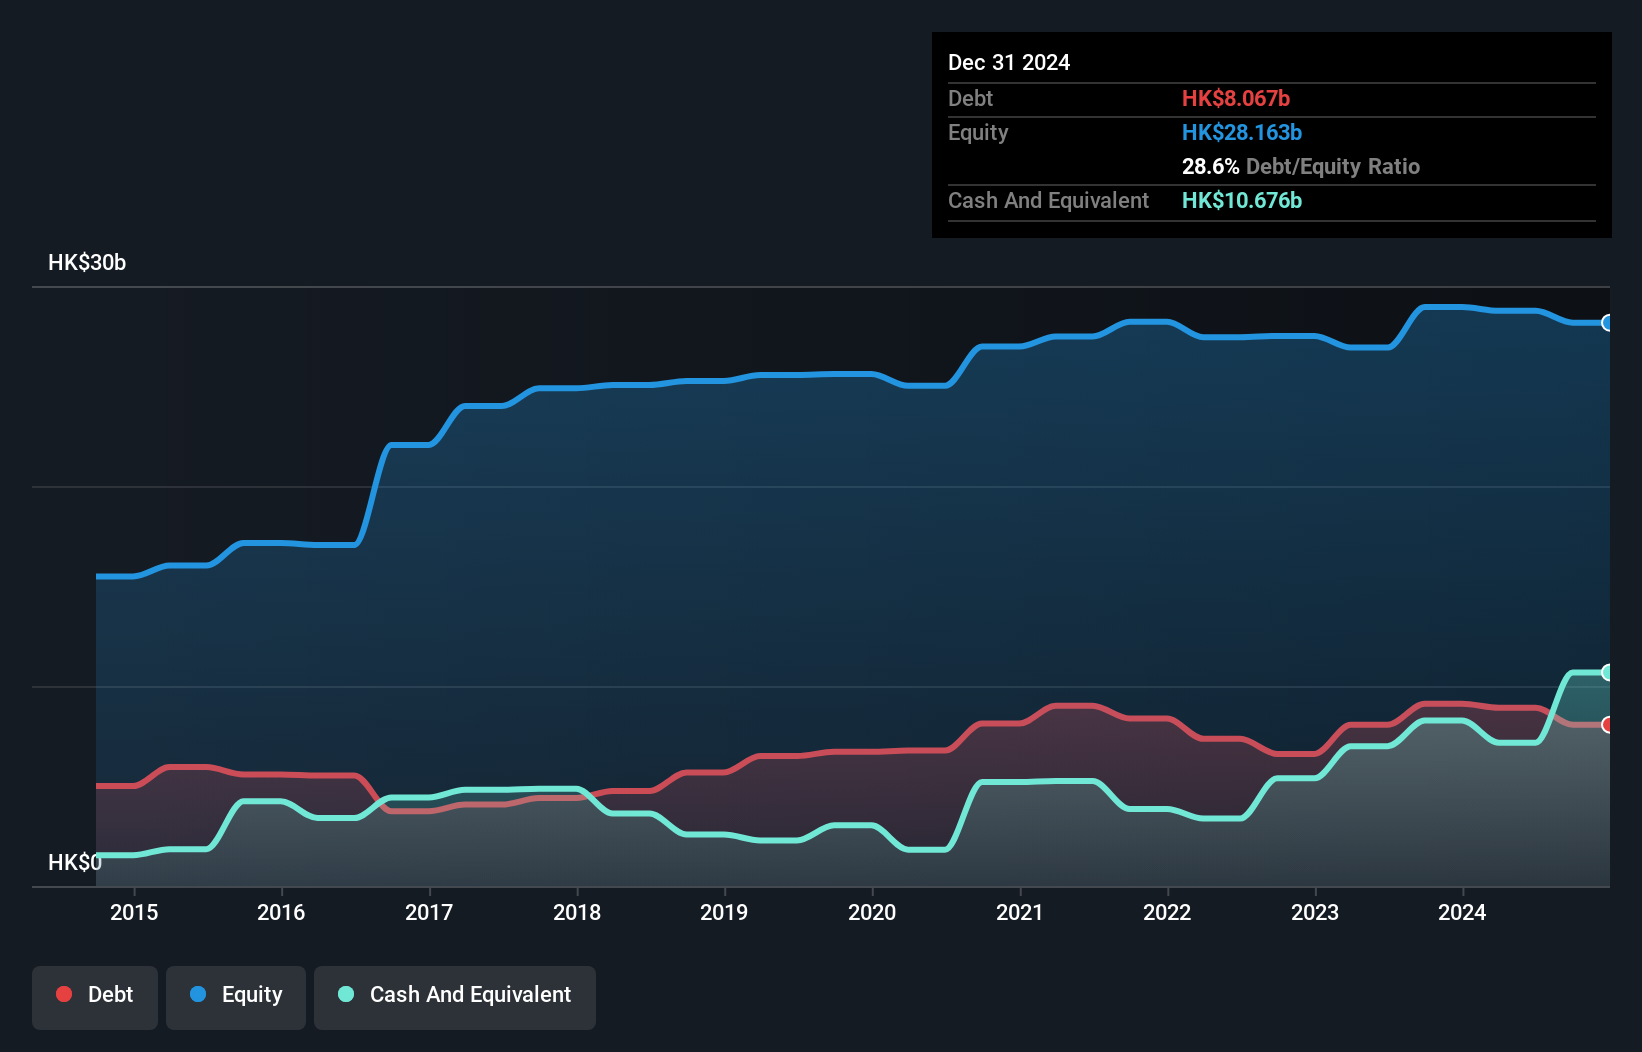
China High Speed Transmission Equipment Group has recently become profitable, with net income reaching CN¥32.94 million for the first half of 2026, a significant improvement from a net loss in the same period last year. The company's revenue primarily comes from its Wind and Industrial Gear Transmission Equipment segment, although sales have decreased to CN¥7.52 billion compared to the previous year. Despite this volatility and a high debt-to-equity ratio of 67.1%, short-term assets comfortably cover liabilities, and interest payments are well-covered by EBIT at 10.5 times coverage, suggesting financial resilience amidst market challenges.
- Jump into the full analysis health report here for a deeper understanding of China High Speed Transmission Equipment Group.
- Learn about China High Speed Transmission Equipment Group's historical performance here.

Taking Advantage
- Click through to start exploring the rest of the 1,054 Asian Penny Stocks now.
- Contemplating Other Strategies? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com