


Exploring Three Undiscovered Gems In Asia With Promising Potential
Amidst a backdrop of geopolitical tensions and fluctuating oil prices, Asian markets have experienced mixed performance, with small-cap indices showing particular volatility. In this environment, identifying stocks that demonstrate resilience and growth potential becomes crucial for investors looking to navigate these uncertain times.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.39% | 25.87% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| Xinxiang Chemical Fiber | 70.11% | -0.33% | -29.16% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Shanghai Fudan Microelectronics Group | 16.49% | 9.29% | -6.62% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
Hyosung TNC (KOSE:A298020)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Hyosung TNC Corporation is a South Korean company that manufactures and sells fiber both domestically and internationally, with a market cap of ₩1.39 trillion.
Operations: Hyosung TNC generates revenue primarily from its Textile and Trade sectors, with the Textile segment contributing ₩5.32 billion and the Trade sector adding ₩5.37 billion. The company also engages in internal sales between these sectors, amounting to -₩2.33 billion.
Hyosung TNC has been making waves with its innovative approach in the textile industry, particularly through its bio-based spandex solutions. The company recently reported a substantial increase in net income for Q2 2026 at KRW 95.49 billion, up from KRW 12.21 billion the previous year, showcasing impressive earnings growth of 42.7% over the past year. Trading at a significant discount to estimated fair value, Hyosung TNC is capitalizing on its fully integrated production system in Vietnam to meet global demand swiftly and efficiently. Despite a high net debt to equity ratio of 99.5%, interest payments are well covered by EBIT at 4.5x coverage, indicating solid financial management amidst expanding operations into premium bio-textile markets globally.
- Click here to discover the nuances of Hyosung TNC with our detailed analytical health report.
Assess Hyosung TNC's past performance with our detailed historical performance reports.

Aisan Industry (TSE:7283)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Aisan Industry Co., Ltd. specializes in the manufacture and sale of automotive parts both in Japan and globally, with a market capitalization of ¥120.33 billion.
Operations: Aisan Industry generates revenue primarily from its automotive parts sales across various regions, with Japan contributing ¥143.39 billion and Asia adding ¥136.96 billion. The Americas and Europe segments contribute ¥80.04 billion and ¥15.96 billion, respectively, to the total revenue stream.
Aisan Industry, a compact player in the auto components scene, has shown steady earnings growth of 11.9% annually over five years. Despite trailing the industry’s recent 26.6% surge with its own 21.5%, it trades at a compelling value—43.4% below estimated fair value—and holds more cash than debt, ensuring financial flexibility. However, its share price has been quite volatile recently and free cash flow remains negative. Recent guidance revisions highlight optimism with projected net sales of ¥335 billion and operating profit of ¥19.5 billion for fiscal year-end March 2027, suggesting potential upside if forecasts hold true.

Noritsu Koki (TSE:7744)
Simply Wall St Value Rating: ★★★★★★
Overview: Noritsu Koki Co., Ltd. is a company that, along with its subsidiaries, focuses on the manufacturing and sale of audio equipment and peripheral products across various global markets, with a market capitalization of ¥204.69 billion.
Operations: Noritsu Koki generates revenue primarily from manufacturing audio equipment and peripherals, amounting to ¥118.48 billion, and parts/materials sales totaling ¥27.43 billion.
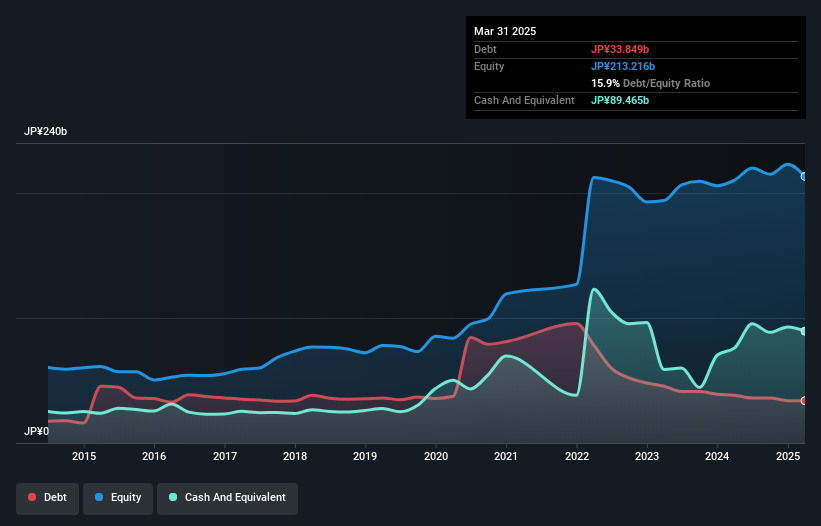
Noritsu Koki, a nimble player, has been making waves with its recent financial performance. Over the past year, earnings surged by 74.6%, significantly outpacing the Leisure industry's 1.5% growth rate. The company's debt to equity ratio impressively shrank from 71.7% to 33.7% over five years, showcasing prudent financial management and a satisfactory net debt to equity ratio of 5.8%. In the first half of 2026 alone, sales climbed to JPY 82 billion from JPY 55 billion last year while net income jumped to JPY 12 billion from JPY 7 billion, reflecting robust operational strength and high-quality earnings amidst industry challenges.
- Delve into the full analysis health report here for a deeper understanding of Noritsu Koki.
Evaluate Noritsu Koki's historical performance by accessing our past performance report.
Taking Advantage
- Reveal the 116 hidden gems among our Asian Undiscovered Gems With Strong Fundamentals screener with a single click here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com