


How Agent Led TV Buying Will Impact Magnite Stock (MGNI)
- Recent updates show Magnite working with ITN, Telly and Amnet to extend agentic and programmatic tools across local linear, CTV and live streaming.
- The focus on agent-led workflows and unified execution through ClearLine and SpringServe points to a push for faster, lower-friction TV ad buying.
- This article will examine how Magnite's push into agentic TV buying could reshape the existing investment narrative around its CTV expansion.
Magnite Investment Narrative Recap
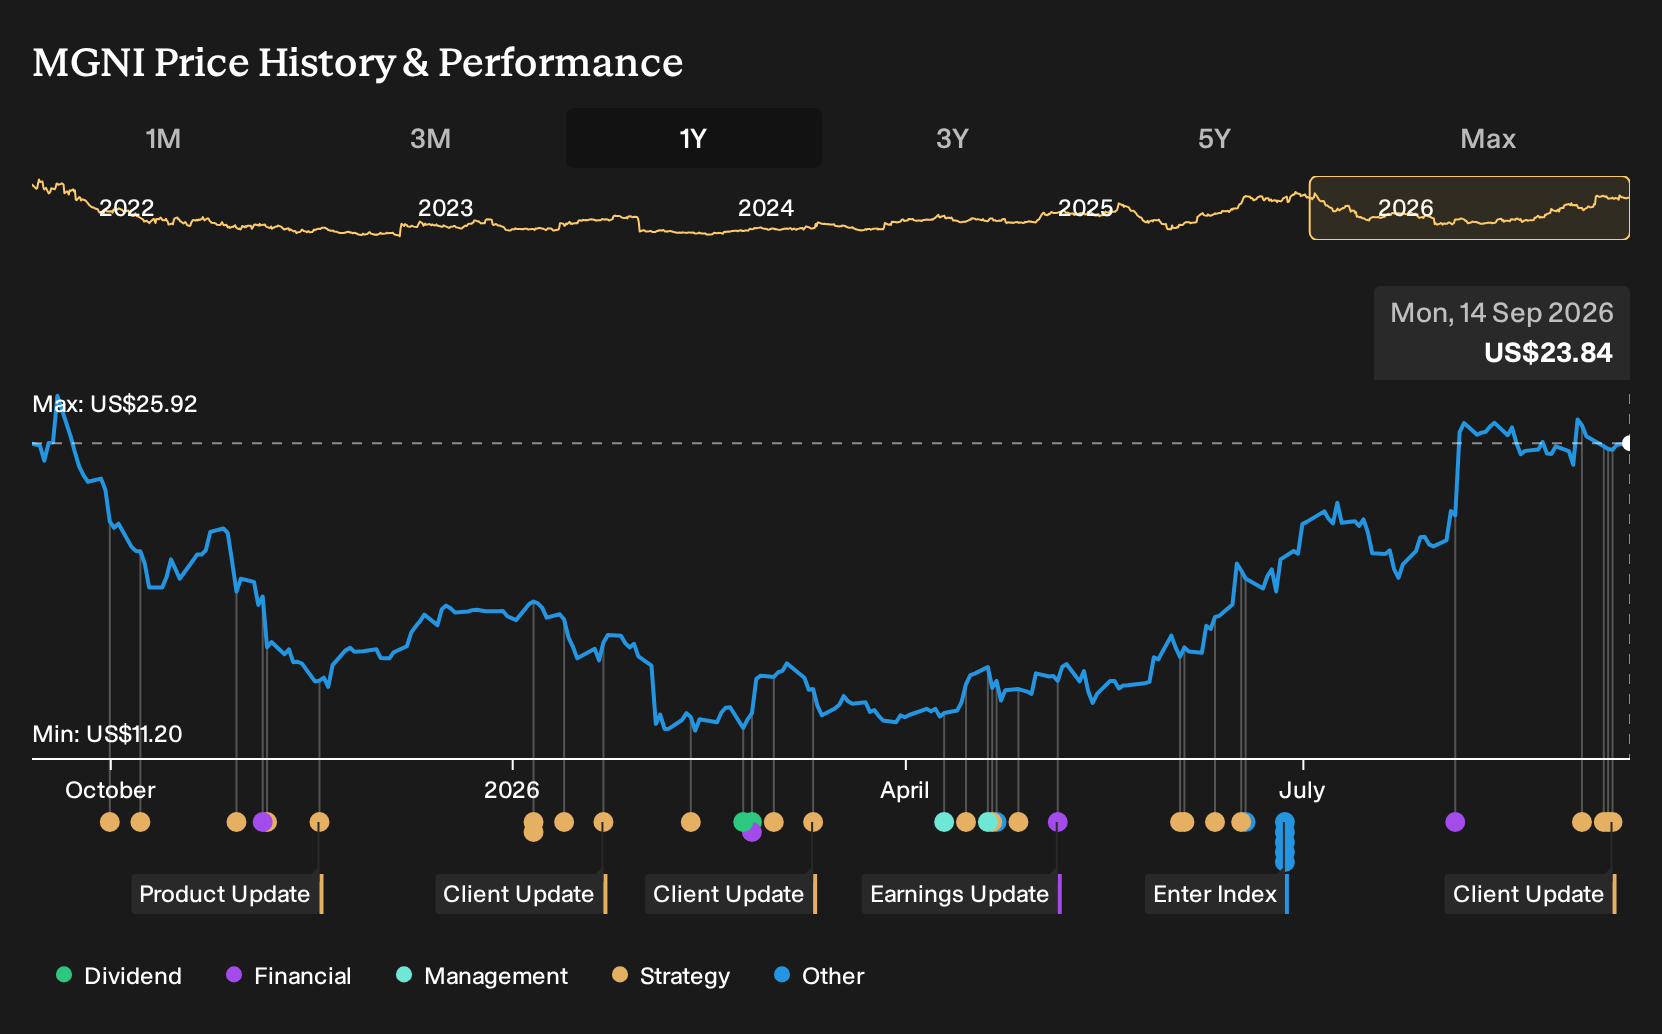
To stay in Magnite, you need to believe that independent TV ad infrastructure still matters as budgets move toward CTV, live streaming, and automated buying. The short term swing factor is whether the agentic and programmatic tools actually deepen spend from existing partners rather than just shifting workflows. These updates help the operating story but do not clearly change near term earnings risk on their own.
The main near term risk remains concentration in large CTV streamers and agencies, plus the heavy spend required to keep Magnite’s tech stack competitive. Faster, lower friction TV buying could support utilization of that infrastructure. If adoption disappoints or ad budgets soften, the same fixed cost base could pressure margins that recently improved.
The expanded Magnite and ITN partnership around agentic local linear looks most relevant here. It tries to turn a multi week IO process into hours and connects ITN’s NXTv with ClearLine, so buyers can plan, forecast and execute in one flow. That directly targets one of Magnite’s key operational levers, which is deeper CTV and TV style spend running through its own rails.
You should see this as a live test of whether Magnite’s orchestration layer and agents can actually pull more demand into open TV inventory rather than lose it to walled gardens. Success would support the catalyst around TV ad dollars shifting into transparent, independent platforms. Any operational hiccups or weak take up would reinforce the risk that big platforms and in house tools keep more of the budget.
Magnite’s analyst narrative points to revenues of $927.5 million and earnings of $134.8 million by 2029, tied to a projected 7.7% yearly revenue growth rate and an earnings decline of $32.1 million from $166.9 million today.
Uncover why Magnite's fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One very different angle comes from the bearish focus on shrinking margins at Magnite. The lowest analysts were pencilling in profit margins dropping to 7.5% with earnings of about $65.1 million on $863.1 million of revenue by 2029, far below consensus. That is a much harsher read on risk. These views all predate the recent agentic TV news, so you should expect fresh opinions and updated numbers as more analysts revisit their models.
Explore 3 other Magnite fair value estimates, including one that suggests as much as 29% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Magnite research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Magnite. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Magnite's overall financial health at a glance.
Looking For More Investment Ideas Beyond Magnite?
If the Magnite story has you thinking more broadly about where to allocate capital, it can help to line it up against other opportunities with clear financial traits. The Simply Wall St Screener lets you filter for specific qualities so you can build a watchlist that reflects your own risk and return preferences.
- For investors who care most about resilience and capital preservation, start with a basket of 11 resilient stocks with low risk scores that score well on stability metrics and may be better suited to steadier compounding.
- If you want to stay focused on value while keeping an eye on balance sheets and cash generation, scan a curated 35 high quality undervalued stocks that combine quality fundamentals with potentially appealing pricing.
- Income focused readers who still want room for capital appreciation can review a 6 dividend fortresses to see which companies pair higher yields with robust financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com