


Should Meta One Launch Require Action From Meta (META) Investors?
- Meta Platforms has launched Meta One, a paid subscription bundle across Facebook, Instagram and WhatsApp, and is advancing in-house AI chips Arke and Astrid with Broadcom and TSMC to reshape how it earns money and runs its infrastructure.
- The combination of direct subscription revenue from Meta One and tighter control over AI compute through custom chips points to a business model that relies less on pure ad volume and more on multi-channel monetization and cost discipline.
- We will examine how Meta Platforms' investment narrative is reshaped by the Meta One rollout and its push into custom AI chips.
Scan how Meta Platforms' pivot into AI subscriptions and custom chips compares with peers by lining up the 60 AI infrastructure stocks that could also be gearing up for the next leg of AI spend.
Meta Platforms Investment Narrative Recap
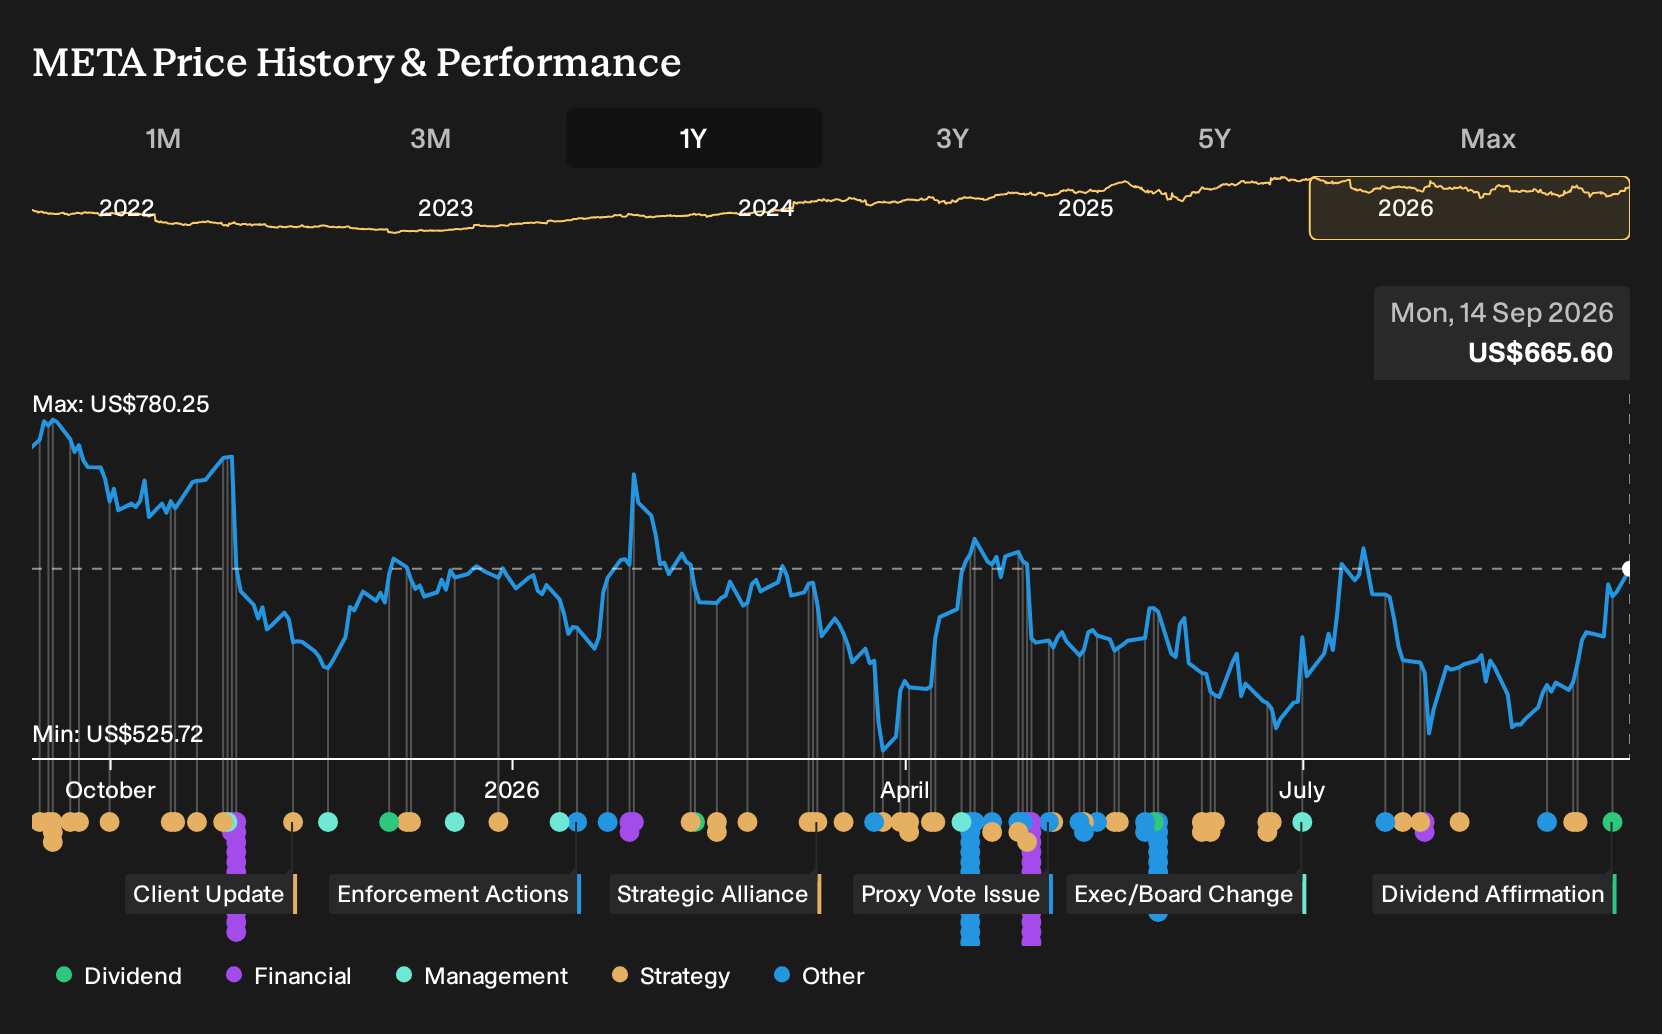
To own Meta Platforms, you need to believe its heavy AI and infrastructure spending eventually supports healthier earnings than the recent margin pressure suggests. In the short term, the key issue is whether management can keep expense and capital spending growth from running ahead of revenue for too long. The new quarterly dividend of US$0.525 per share signals confidence in cash generation, but does not materially change that central debate.
The biggest operational risk is that AI data center investment, legal settlements, and Reality Labs losses keep dragging on profitability while regulation weighs on European ads. Meta’s near term catalyst remains evidence that AI driven ad tools, messaging monetization, and subscriptions like Meta One start to show up in more efficient profit growth.
The fresh dividend declaration is the clearest operational signal tied to this shift. Meta Platforms is now committing recurring cash to shareholders while still absorbing sizeable capital outlays for custom AI chips, multi gigawatt compute clusters, and expanding data centers. That combination puts a spotlight on free cash flow resilience and on how quickly the firm can convert AI and subscription bets into earnings support.
Regular dividends can also change how some investors frame risk. Income focused holders may become more sensitive to swings in spending, regulatory fines, or long dated Reality Labs losses that could threaten payout capacity over time. For you, the practical question is whether the new income stream offsets concerns about elevated capex, volatile AI headlines, and the execution gap between strong top line advertising performance and compressed operating margins.
Meta Platforms' current analyst narrative points to US$392.8b in revenue and US$113.3b in earnings by 2029, based on an assumed 19.8% yearly revenue growth rate and an earnings increase of about US$45.2b from US$68.1b today.
Uncover why Meta Platforms' fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts Meta Platforms’ AI spend and data center buildout at the center of the risk story. In that lens, the big worry is that the heavy infrastructure bill never lines up with returns, even though the most optimistic analysts were modeling US$483.4b in revenue and US$155.7b in earnings by 2029 before this Meta One and dividend news. Those estimates came from before the latest subscription launch and dividend affirmation, so you should expect opinions to move as fresh information filters through. That disagreement is the opportunity for you to compare multiple scenarios and decide which version of Meta Platforms’ future feels more realistic.
Explore 61 other Meta Platforms fair value estimates, including one that suggests there could be as much as 60% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Meta Platforms research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Meta Platforms. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Meta Platforms' overall financial health at a glance.
Looking For More Ideas Beyond Meta Platforms?
If Meta Platforms is on your radar, it often helps to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener can surface stocks with traits that align more closely with what you want from your portfolio, whether that is resilience, income, or under the radar growth potential.
- If capital preservation and smoother drawdowns matter most to you, consider focusing on 11 resilient stocks with low risk scores that score well on stability and downside resilience.
- For investors who like finding mispriced opportunities with strong fundamentals, it can be worth scanning 15 high quality undiscovered gems that are not yet widely followed.
- If your priority is dependable income rather than rapid capital gains, you could concentrate on 6 dividend fortresses that combine higher yields with a focus on payout strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com