


Datadog (DDOG) Stock Looks Cheap Against Its Cash Flow Outlook
Datadog has delivered powerful long term gains for shareholders, which puts a spotlight on a simple question: Is the current US$230.05 share price adequately supported by the cash flows the business is expected to produce?
- The stock has returned 143.4% over the past 3 years, which raises the stakes on whether that performance lines up with the cash the company can generate over time.
- The business model is built around recurring software subscriptions that can support relatively visible cash generation, so any change in customer retention or spending plans may have an outsized effect on what those future cash flows are worth today.
- What if you looked at Datadog through its sales instead? See why Datadog's 20.8x P/S tells a different valuation story.
For investors, the debate is whether Datadog's current market value is justified by its intrinsic value as estimated using its cash flows.
If you are weighing whether Datadog's cash flows justify a US$230.05 share price, it can help to compare that question with a broader group of 35 high quality undervalued stocks
Does Datadog Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Datadog can return to shareholders over time. Based on the latest twelve months, the group generated around $1.1b of free cash flow, which gives the model a concrete starting point rather than a purely theoretical build.
Analysts and internal estimates then project that free cash flow keeps growing, reaching into the low single digit billions of $ annually by the early 2030s. That pattern assumes Datadog keeps converting its subscription base into higher cash generation rather than relying on one off spikes. When those projected cash streams are discounted back, the DCF output comes in meaningfully above the current US$230.05 share price, so the model implies the market is not fully pricing in those expected cash flows today. Find out what Datadog could be worth using our Discounted Cash Flow (DCF) estimate.
The Datadog Narrative: What Would Justify Today's Price?
Narratives for Datadog sit between the current valuation puzzle and the real world, explaining which future paths for growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than it is today. Rather than leaving you with a single model output or ratio, they describe the future assumptions behind those figures so you can track how Datadog's actual progress aligns over time on Simply Wall St's Community page.
Community narratives around Datadog split between those who see more upside in the current setup and those who think expectations already look full.
Bull case: 19% undervalued
"Ongoing product innovation (e.g., autonomous AI agents, enhanced security modules, expanded log and data observability) is increasing platform breadth and relevance..."
Discover why this Narrative puts Datadog at 19% undervalued.
Bear case: roughly fairly valued
"The proliferation of open-source alternatives and hyperscaler-native monitoring solutions, coupled with the desire for greater vendor-agnosticism and “bring your own cloud,” may intensify competitive pricing pressures..."
Explore why this Narrative puts Datadog at roughly fairly valued.
One more Datadog signal the valuation does not answer
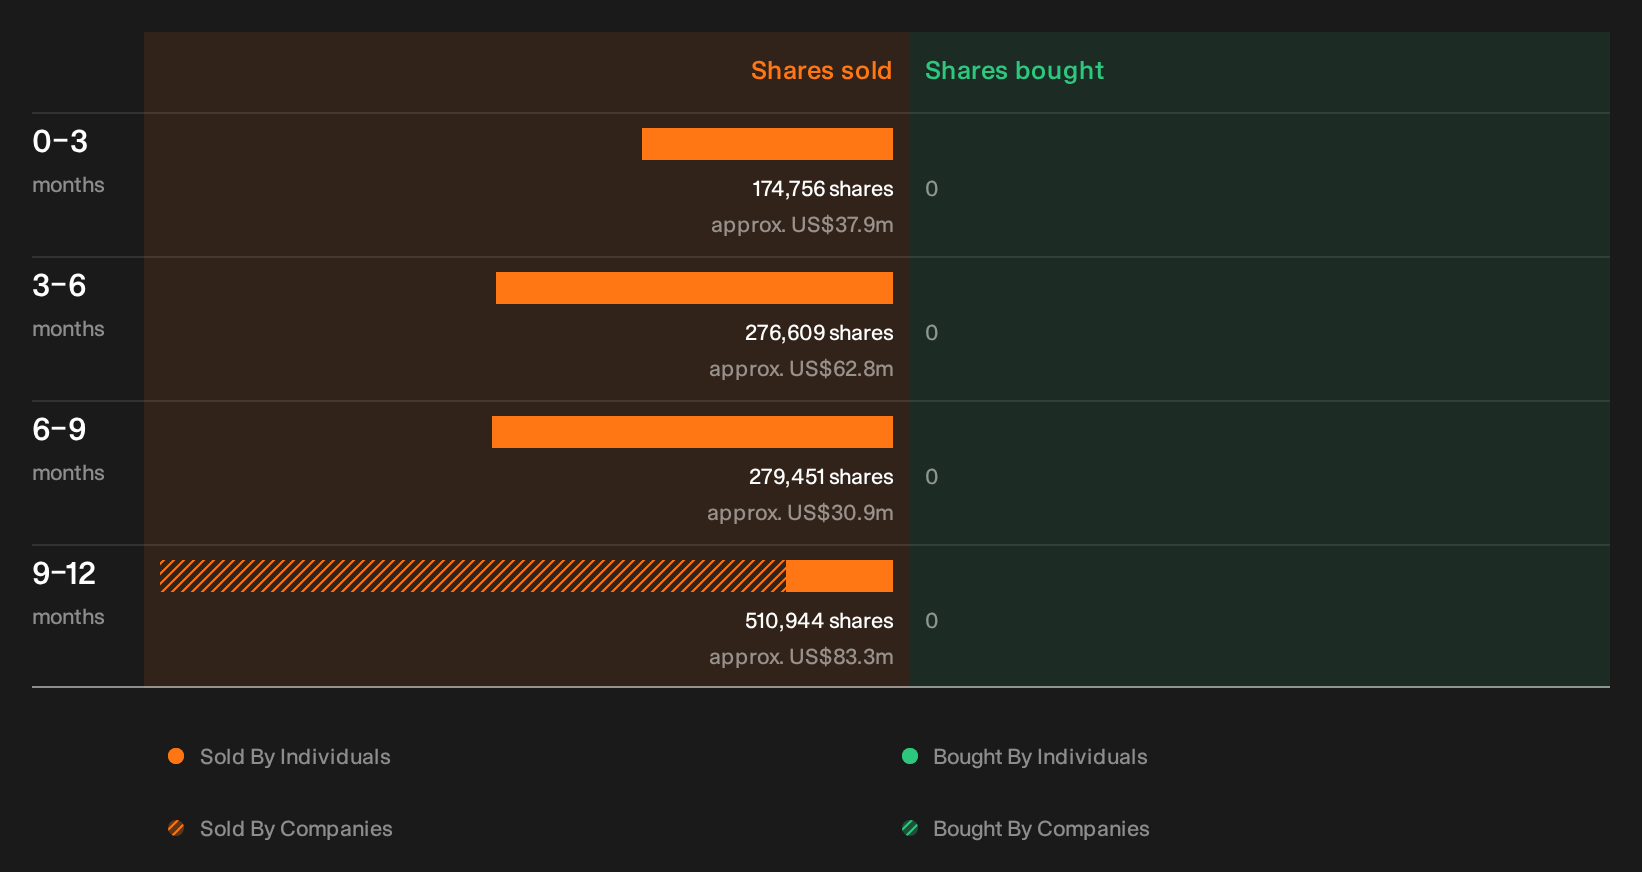
Price and cash flows tell only part of the Datadog story, because our checks have also picked up recent share sales by people inside the business, and the specific sellers, volumes and context are left for you to review in detail. See the recent insider selling flagged for Datadog.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com