


Should Stronger Earnings Require Action From Gold.com (GOLD) Investors?
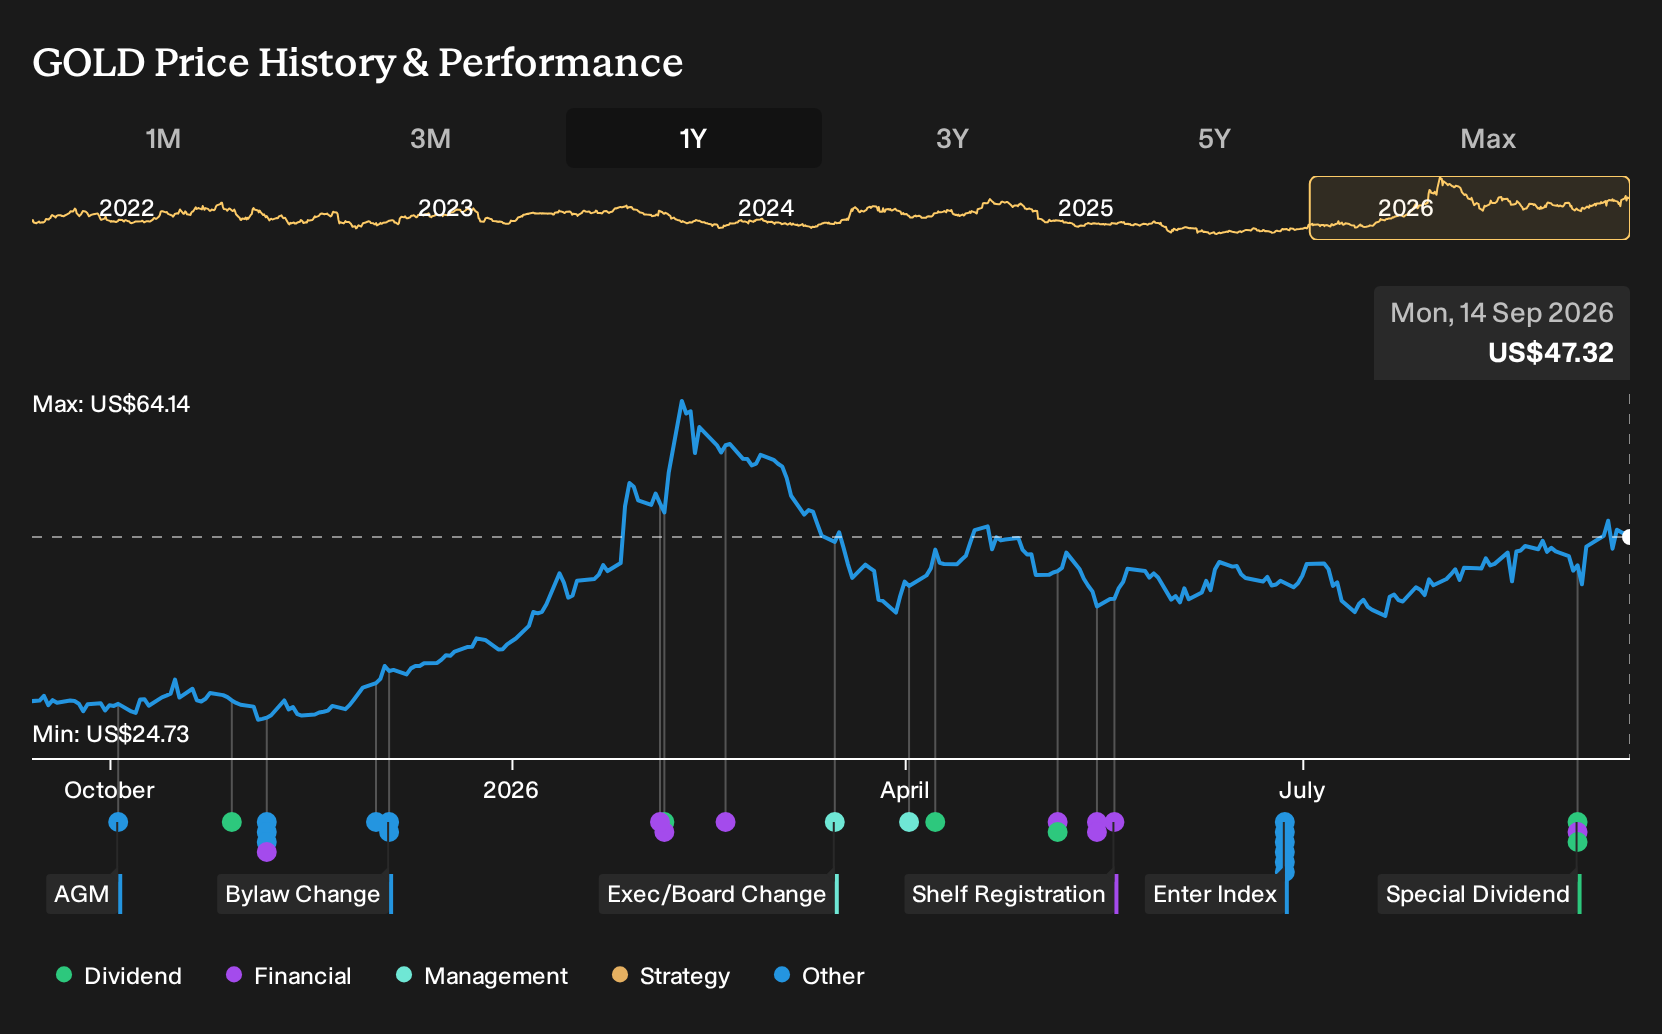
- Gold.com reported fourth quarter sales of US$5,005.01 million and net income of US$12.16 million, with full year sales of US$25,513.41 million and net income of US$82.34 million. The board declared both a US$1.00 per share special dividend and a US$0.20 quarterly cash dividend, all announced on September 2, 2026.
- The combination of sharply higher annual earnings per share from continuing operations and the added one time cash dividend indicates that Gold.com is pairing stronger operating results with direct cash returns to shareholders, which may influence how investors think about the durability of its current business model.
- Next, the focus turns to how this stronger full year earnings profile and special dividend at Gold.com might reshape the broader investment narrative.
Scan beyond Gold.com and size up other potential opportunities with our hand picked list of 35 elite gold producer stocks that are also returning cash to shareholders through dividends.
Gold.com Investment Narrative Recap
To stay invested in Gold.com, you need to believe the business can turn its current earnings profile into something repeatable. Full year sales of US$25,513.41 million and net income of US$82.34 million show scale, while forecast earnings growth and slightly better net margins suggest some operating leverage. The key near term catalyst is continued execution across wholesale, direct to consumer and secured lending without giving back margin.
The biggest risk is that organic demand for physical metals and collectibles softens while costs stay high. Reliance on acquisitions and higher risk funding sources could pressure stability if integration benefits stall or financing becomes more expensive. The latest results improve the story, but do not remove those concerns.
The special US$1.00 per share dividend announced on September 2, 2026 is the clearest new data point. It comes on top of the regular US$0.20 quarterly dividend and arrives after a year where earnings per share from continuing operations were US$3.11 basic and US$3.02 diluted. For you, that combination links current profitability with a tangible cash return.
This extra payout also sharpens the focus on dividend sustainability and capital allocation. Gold.com already has an unstable dividend track record and recent shareholder dilution. That places more weight on management delivering the forecast earnings growth and keeping balance sheet flexibility intact so that future investments, acquisitions and any ongoing distributions are not constrained.
How A-Mark’s Forecasts Frame The Gold.com Context
A-Mark Precious Metals sits in a closely related corner of the market to Gold.com, so its analyst assumptions give you a useful reference point for what the sector is currently pricing in. Instead of only focusing on trailing dividends and recent profits, it helps to line up where earnings and revenue are expected to land over the next few years and how that compares with what you are implicitly assuming for Gold.com.
Analysts are building their A-Mark models around revenue expanding by 6.0% each year for the next three years. They also expect current earnings of US$37.9 million to move to a consensus forecast of US$90.3 million by 2028, which is an earnings increase of about US$52 million. The same report assumes profit margins improve from 0.3% today to 0.7% over that period, with the forecast year of reference being 2028.
Those inputs sit behind the valuation work. On the numbers provided, analysts are pairing a 2028 revenue estimate of US$13.1b with projected earnings of US$90.3 million for that same year. They then apply a P/E of 16.5x to those 2028 earnings to reach their A-Mark price target, using a discount rate of 9.7% to bring that future profile back to today.
Gold.com's narrative projects 2028 revenue of US$13.1b and earnings of US$90.3 million, built on 6.0% yearly revenue growth and an earnings increase of about US$52 million from current earnings of US$37.9 million.
A few things matter for you as a Gold.com shareholder or potential investor. One is how comfortable you are with the requirement for both higher sales and meaningfully stronger profitability to justify the forecasts you see in peer names like A-Mark. Another is how you weigh those assumptions against Gold.com's own capital allocation choices, including the recent special dividend and any future preference for buybacks, acquisitions or further cash returns.
Peer expectations also highlight execution risk. For A-Mark, the scenario depends on integrating recent acquisitions, scaling direct to consumer channels and extracting enough cost benefit to lift margins from 0.3% to 0.7%. For Gold.com, the parallel question is whether current wholesale, secured lending and consumer operations can hold or improve margins while still supporting the dividends that have just been announced.
For you, the practical takeaway is to cross check the sort of revenue growth, margin expansion and earnings step up implied in A-Mark's numbers with what you think is realistic for Gold.com. If the assumptions behind peers look aggressive relative to your view on demand for physical metals, collectibles and related services, that may argue for more conservative expectations on what Gold.com can sustainably earn and distribute in cash over time.
Uncover why Gold.com's fair value indicates a 41% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate Gold.com story leans heavily on the special dividend as a signal of confidence. The most optimistic analysts were already working off about US$26.3b of revenue and US$144.4 million of earnings by 2029, with a higher P/E assumption, before this payout was announced. That camp might now see even more upside, while others may question whether those richer expectations still hold. You are looking at very different playbooks, so treat this news as a reason to compare several viewpoints, not just one.
Explore 6 other Gold.com fair value estimates, including one that suggests as much as 90% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Gold.com research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Gold.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gold.com's overall financial health at a glance.
Looking For More Investment Ideas Beyond Gold.com?
Once you have formed a view on Gold.com, it can help to compare it with other opportunities that match your risk tolerance and income goals. The Simply Wall St Screener gives you a way to filter for different styles of stocks, then drill into the data that matters most to you.
- If you are hunting for smaller companies with higher risk but potentially outsized return profiles, start by sizing up 3 elite penny stocks with strong financials that pass fundamental checks.
- If your preference leans toward quality and valuation discipline, scan through our curated 35 high quality undervalued stocks that combine solid cash flows with healthier balance sheets.
- If portfolio income is a key priority, review the 6 dividend fortresses that pair dividend yields above 5% with a focus on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com