


DLocal (DLO) Compliance Push Puts Its Valuation Story Back In Focus
DLocal’s Compliance Partnership With Oscilar
DLocal (DLO) has drawn fresh attention after partnering with Oscilar to deploy an AI-native risk platform across its more than 60 markets, focusing on AML monitoring, sanctions screening, and case management.
The move puts compliance infrastructure in the spotlight for a payments processor that handles complex cross-border flows and gives investors another angle to assess how DLocal manages regulatory demands alongside its payments offering.
DLocal’s compliance announcement lands after a mixed share price stretch, with a 16.85% 90 day share price return and 4.73% 30 day gain offset by a weaker 7 day move, while the 6.44% 1 year total shareholder return sits against a much deeper 3 and 5 year drawdown.
Scan how DLocal’s compliance push compares with peers working on financial resilience and regulation strength by reviewing the hand picked 11 resilient stocks with low risk scores in this space.
DLocal’s compliance shift raises a sharper question. Are investors reacting to a sturdier operating framework, or simply resetting sentiment around a stock that still screens at a discount on several valuation lenses?
Most Popular Narrative: 71% Undervalued
DLocal’s share price of $14.84 sits well below the $50.96 fair value argued in the most followed valuation story, which frames the Oscilar partnership as one more tool for protecting a high cash flow engine rather than a simple compliance upgrade.
DLocal trades below the value implied by discounting its own free cash flow. On a two-stage model running 10 years of +25.0% growth fading to a 2.5% terminal rate, discounted at 9.8%, the shares are worth USD 50.96 against a market price of USD 15.24, a 70% discount, or +234% to fair value. 58% of that value sits in the terminal period, which is the honest caveat, the further out the cash flow, the more the answer is a statement about assumptions rather than about this year. The business earns 37.0% on invested capital on a 20.7% operating margin struck against 36.6% gross margins. Of USD 1.09B in trailing revenue, 40.0% converts all the way to free cash flow, and the balance sheet carries debt at 0.16 times equity, in fact a net cash position of USD 733.78M, which buys the time a levered peer would not have.
See why 4 investors see DLocal as 71% undervalued.
Result: Fair Value of $50.96 (UNDERVALUED)
Still, the DLocal story leans heavily on optimistic cash flow assumptions, and any setback in key Latin American markets or tighter regulation could quickly challenge that thesis.
Find out about the key risks to this DLocal narrative.
Another View On DLocal’s Valuation
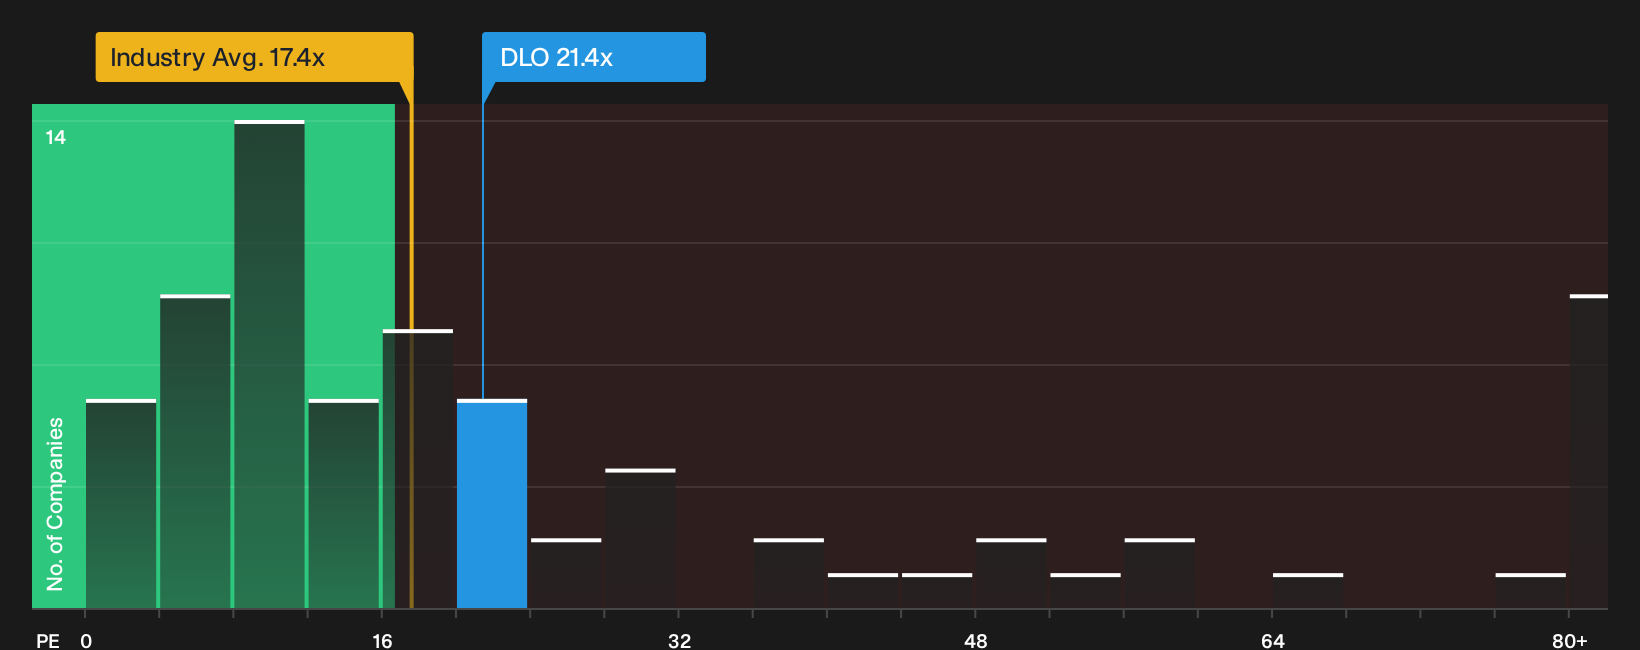
The cash flow story points one way. A different lens based on earnings tells something less one sided. DLocal trades on a P/E of 21.4x, above the US Diversified Financial industry on 17.4x, yet below a 43.8x peer average and a fair ratio of 17.5x. This combination suggests both upside potential and valuation risk if sentiment cools.
Investors weighing that trade off around DLocal’s earnings based valuation can use the See what the numbers say about this price — find out in our valuation breakdown. to explore how this current P/E gap might close over time.
Next Steps
If this mix of caution and optimism around DLocal leaves you on the fence, move quickly, stress test the assumptions, and then weigh up the 4 key rewards
Looking For More Investment Ideas Beyond DLocal?
If DLocal has sharpened your thinking, do not stop here. Broaden your watchlist today so you are not chasing the next opportunity after it moves.
- Target higher potential upside by scanning 3 elite penny stocks with strong financials, which pair small size with stronger balance sheets and cleaner financial profiles.
- Zero in on value by reviewing the 35 high quality undervalued stocks, which combine solid fundamentals with pricing that still looks out of step.
- Build income and resilience by assessing the 6 dividend fortresses, which offer 5%+ yields supported by sturdier payout histories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com