


Will Earnings Upgrade Change Ensign Group (ENSG) Narrative
- Ensign Group was recently upgraded to a Zacks Rank #2 after analysts raised earnings estimates, reflecting stronger expectations for its skilled nursing and senior care operations.
- The renewed earnings outlook highlights how Ensign Group’s post acute care footprint and affiliated healthcare REIT platform are central to its profit potential.
- We will look at how Ensign Group’s investment narrative is influenced by the higher earnings estimates that supported the recent analyst upgrade.
Ensign Group Investment Narrative Recap
To own Ensign Group, you need to be comfortable with a skilled nursing operator that leans heavily on Medicare and Medicaid reimbursement, while working to improve underperforming facilities it has acquired. The recent earnings upgrade points to firmer expectations for the operating footprint, but it does not erase the execution work still required at low-occupancy and clinically challenged sites.
The key near-term swing factor is whether Ensign Group can lift occupancy and skilled mix in those newer operations without allowing staffing costs to escalate. The biggest risk is pressure on reimbursement rates or quality ratings, which could limit pricing power and weaken margins even if volumes remain healthy.
Without a stream of formal company announcements linked to this upgrade, the most relevant development is the underlying pattern in Ensign Group’s earnings forecasts and quality metrics that fed into the Zacks Rank change. Analysts are considering factors such as forecast 12.8% annual earnings growth and the contribution from the Standard Bearer REIT platform when they update their models.
Those expectations intersect directly with the core catalysts. Growing post-acute demand, the turnaround opportunity in recently acquired facilities, and expanding rental income from Standard Bearer all feed into the higher earnings estimates. Any slip in execution on acquisitions, staffing stability, or reimbursement assumptions would sit on the other side of that equation and could challenge the upgraded outlook.
Ensign Group Earnings Assumptions Behind The Upgrade
Ensign Group's narrative projects revenues of US$7.5b and earnings of US$565.1m by 2029. That profile is built on analysts assuming 10.9% yearly revenue growth and an earnings increase of about US$186.4m from current earnings of US$378.7m.
The forecast set out in the stock research is fairly explicit. Analysts are working with revenue growing at 10.9% a year for the next three years, while profit margins are expected to move from 6.9% today to 7.5% by year three. For a skilled nursing operator tied to government reimbursement, that mix of faster top line and slightly wider margins is what underpins the improved earnings outlook that fed into the recent Zacks Rank upgrade.
Earnings today are pegged at US$378.7m, with consensus pointing to US$565.1m by about 2029. That implies roughly US$186.4m more profit over the period. For you as an investor, the key question is whether occupancy lift, case mix, and Standard Bearer rental income can reasonably support that step up without stretching labor or risking quality metrics.
Ensign Group's forecasts also build in only modest share count growth. Analysts assume shares outstanding will rise by 0.48% per year over the next three years. That means most of the projected earnings expansion would need to come from operations rather than financial engineering, which keeps the focus squarely on facility level performance and the REIT platform.
How Ensign Group's Valuation Ties Back To The Forecasts
On valuation, the consensus framework is straightforward. Analysts working on Ensign Group are anchoring a US$220.0 price target on the idea that by 2029, revenue reaches US$7.5b and earnings come in at US$565.1m. Those figures are discounted using a rate around 7.2% to 7.24%, which is intended to reflect the risk profile outlined in the Simply Wall St work.
For that target to line up, Ensign Group would need to trade on a P/E of 28.1x those 2029 earnings, compared with about 26.6x today and a current US Healthcare sector P/E quoted at 24.8x. The framework assumes investors are willing to value the business at a premium to the wider healthcare group in return for its particular mix of post acute exposure, acquisition pipeline, and REIT earnings.
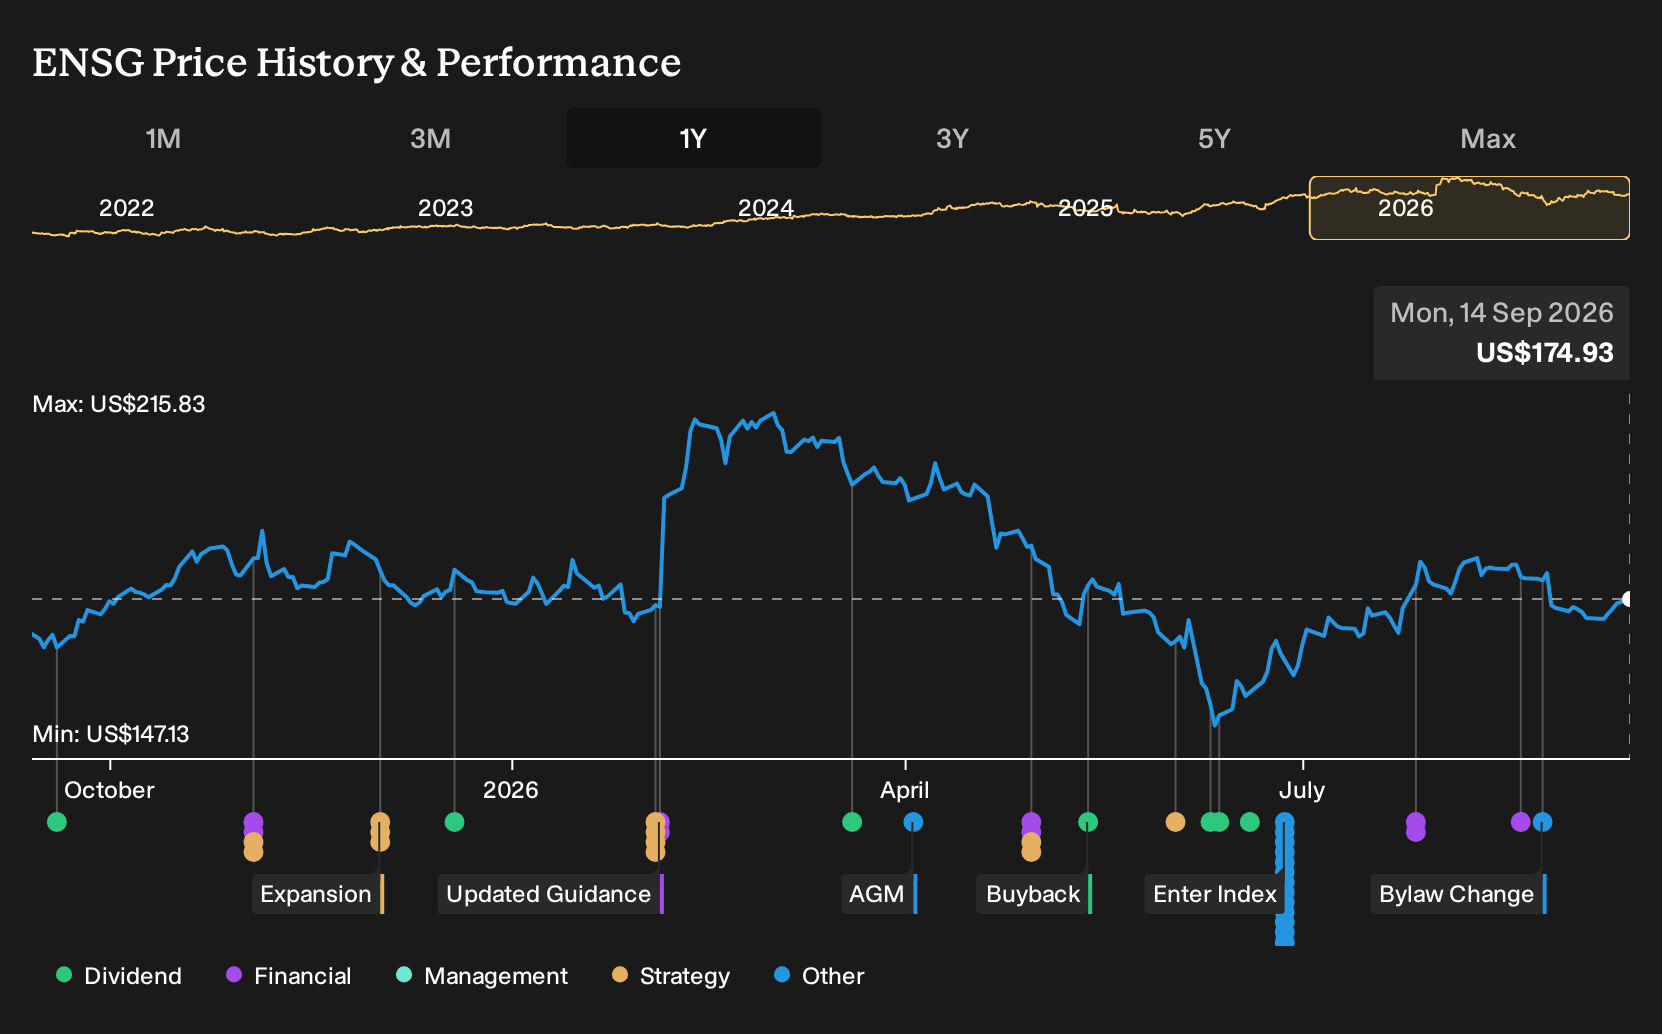
There is a clear gap between the reference share price and the analyst target. With the stock recently at US$174.02, the US$220.0 consensus sits 20.9% higher. That difference essentially measures how much faith the market is expected to place in Ensign Group hitting the US$7.5b revenue and US$565.1m earnings profile while maintaining that richer P/E multiple.
All of these moving parts link back to the same place. If occupancy, reimbursement, staffing, and Standard Bearer trends track close to the assumptions, the earnings path used in the models remains intact. If those inputs weaken, then both the earnings profile and the P/E premium implied for Ensign Group could end up looking too optimistic, which would change how that analyst target reads for your own portfolio work.
Uncover why Ensign Group's fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$199 and US$220, so retail opinions on Ensign Group already span a tight premium to the recent share price. Those views sit alongside clear risks around reimbursement, acquisition turnarounds and staffing, so you may want to compare several community viewpoints before deciding how this earnings story fits your own expectations.
Explore 2 other Ensign Group fair value estimates, including one that suggests it could be worth just $198.98.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ensign Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Ensign Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ensign Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ensign Group?
If Ensign Group has sharpened your focus on earnings quality, reimbursement risk, and balance sheet resilience, it can be useful to cast a wider net across the market using structured filters rather than just ticker-by-ticker research.
- For investors who want potential mispricing paired with financial strength, scan a curated 35 high quality undervalued stocks that screens for quality fundamentals alongside attractive valuations.
- If capital preservation and steadier profiles matter most to you, narrow your watchlist with a 11 resilient stocks with low risk scores that highlights businesses carrying lower overall risk scores.
- When you want to focus on resilient balance sheets first and everything else second, start with a list of solid balance sheet and fundamentals (23 results) filtered for companies that pair financial robustness with sound fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com