


Is Starwood Property Trust (STWD) Fully Valued Even After A 16% Slide?
Starwood Property Trust has seen its share price slide this year, and that drop puts the spotlight squarely on what investors are paying for its earnings stream today. With the stock weaker, the key issue is whether the current valuation still matches what the business is generating in profit terms.
- The share price is down 16.2% year to date, which puts pressure on the case that the current earnings multiple reflects what the market expects from Starwood Property Trust.
- Recent news around Starwood Capital Group's joint venture in student housing highlights how new projects can influence where investors set the bar on future earnings, cash flow timing and required returns for Starwood Property Trust.
- There is a second opinion on Starwood Property Trust worth weighing. See what analysts think Starwood Property Trust's shares could be worth.
The issue now is whether today's price for Starwood Property Trust is justified by the earnings the company is delivering and what investors expect those profits to look like over time.
If you want to stress test the same earnings question you are asking of Starwood Property Trust against a wider field, start by scanning 35 high quality undervalued stocks.
Does Starwood Property Trust Look Pricey on Earnings?
For a mortgage REIT like Starwood Property Trust, earnings are a natural anchor because investors watch how consistently profits cover the dividend and the loan book.
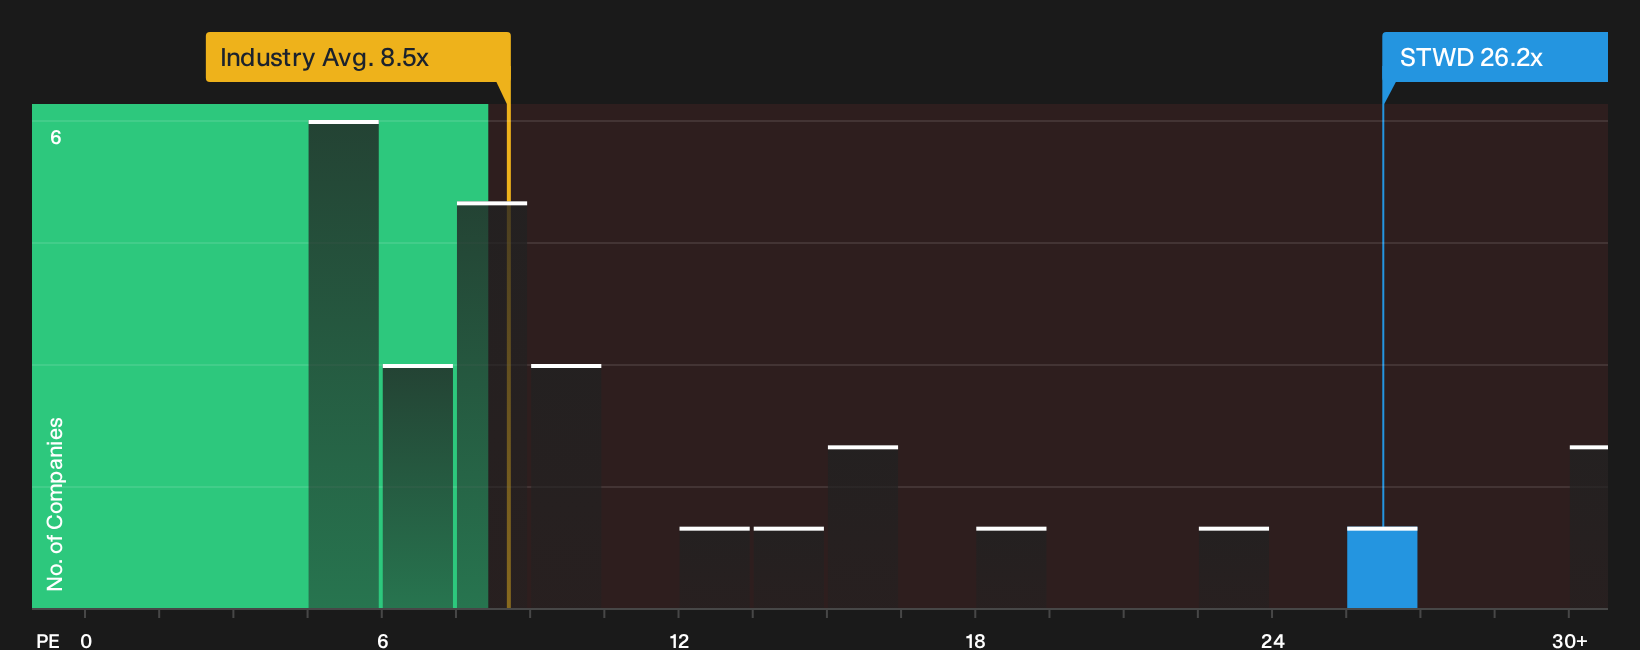
The stock trades on a P/E of 26.2x, which is well above the Mortgage REITs sector average of 8.5x and still below the peer group on about 44.0x. Based on the tailored fair multiple that blends Starwood Property Trust's profitability profile, risk level and industry context, the present P/E screens as overvalued rather than cheap on earnings alone. The excess returns model behind that fair yardstick points to weaker value creation on equity than the current P/E implies.
Despite the fresh student housing joint venture giving Starwood Property Trust a growth project to discuss, the current earnings multiple already asks investors to pay a premium over the modelled fair level for each dollar of profit. Explore the numbers behind Starwood Property Trust's P/E valuation.
The Starwood Property Trust Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Starwood Property Trust valuation puzzle leaves off by spelling out which growth, margin and earnings paths would need to play out for the stock to be worth materially more or materially less than today’s price. Each one treats Starwood Property Trust's implied fair value as a thesis about the business that you can watch over time rather than a one-off snapshot, all housed on the Community page.
One of the top community narratives on Starwood Property Trust: 24% undervalued
"Strong demand from income-seeking investors and sector diversification are set to drive stable, durable earnings and support long-term dividend coverage..."
Discover why this Narrative puts Starwood Property Trust at 24% undervalued.
One important piece of the Starwood Property Trust story is still missing
The valuation only tells part of the story for Starwood Property Trust, because separate checks have raised questions about risks that could change how you weigh the whole opportunity. Take a closer look at 4 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com