


Reddit Finally Gets a Breakout Catalyst. This Could Be Turning Point for the Beaten-Down Stock.
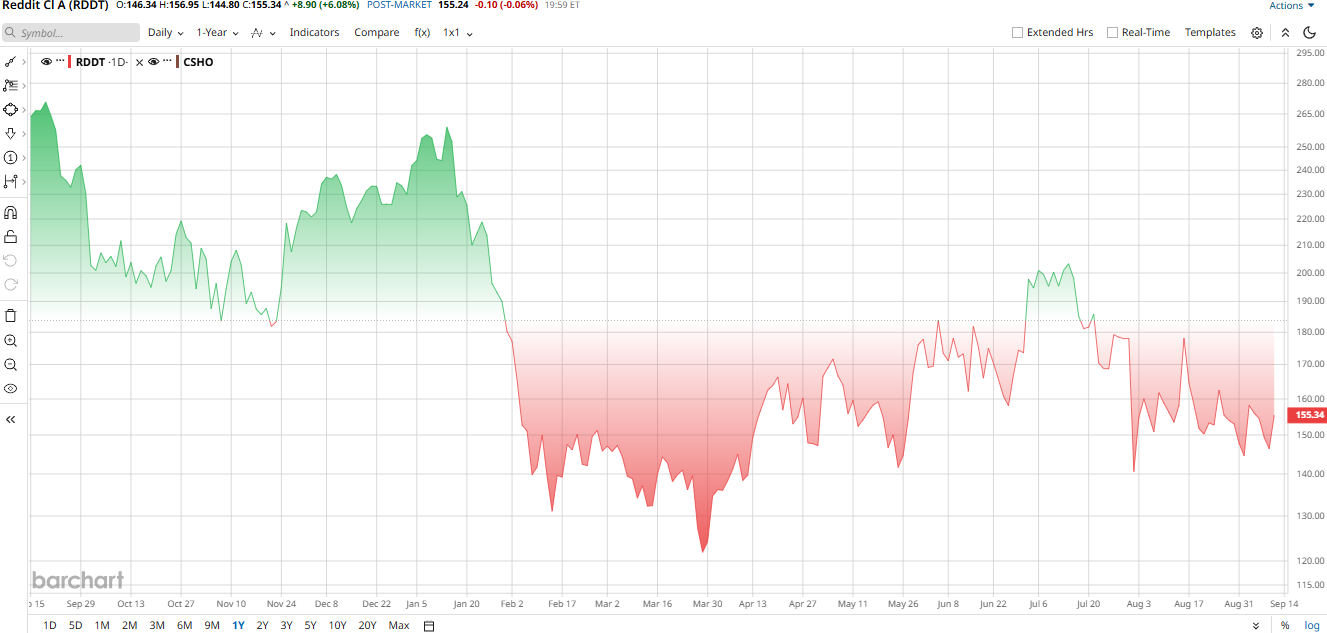
Reddit (RDDT) stock finally gave investors something to cheer about. Shares jumped about 6% on Sept. 10 after Piper Sandler data showed Reddit’s user base grew 8% month over month in August. That marked the company’s strongest monthly gain of 2026 and a sharp reversal from the roughly 2% decline in July.
The move also snapped a four-session losing streak. But there’s still a major problem. Reddit shares remain down 30% in 2026 and down roughly 38% over the past year. The big question now is whether August marked the beginning of a real turnaround or just another short-lived bounce. Let's take a closer look.
August User Growth Could Change the Reddit Stock Story
The August data matters because user growth has become Reddit’s biggest problem with investors.
Piper Sandler said Reddit’s total audience growth accelerated to 18% year-over-year (YOY) in August, up from 12.8% in July. International growth was especially impressive, climbing 29.3% compared with 19% a month earlier. Meanwhile, U.S. users grew 5.2%.
The improvement came mainly from Reddit’s Feed audience, offsetting a decline in Conversation users. That could be important for RDDT stock because Reddit relies heavily on traffic and user engagement to build its advertising business. For months, investors have worried about volatility in search referrals and whether Reddit can keep expanding without depending so heavily on Alphabet's (GOOGL) Google.
August offers an encouraging sign.
Piper Sandler also raised its Reddit advertising-spending forecast by 30 basis points after broader digital ad spending beat expectations. However, the firm expects September audience estimates to fall about 20% because Reddit changed its Ads Manager forecasting methodology. Piper Sandler described that as a one-time measurement reset rather than a deterioration in demand.
For Reddit stock, the key issue is whether the August acceleration will continue over the next few months.
Reddit’s Q2 Results Show the Business Is Still Growing Fast
The latest quarterly numbers give the bulls plenty to work with. Reddit reported second-quarter revenue of $805 million on July 30, up 61% YOY. Advertising revenue climbed 64% to $762 million, while other revenue, including data licensing, rose 24% YOY to $43 million.
Profitability also improved sharply. Net income more than doubled to $253 million, while adjusted EBITDA jumped 106% to $343 million. Free cash flow more than doubled to $261 million, and Reddit ended the quarter with $2.8 billion in cash, cash equivalents, and marketable securities.
User engagement was strong as well. Daily active uniques reached 130.3 million, up 18%, while weekly active uniques climbed 24% to 514.6 million. Global ARPU increased 36% to $6.18, while U.S. ARPU jumped 51% to $11.85.
Management expects Q3 revenue of $860 million to $870 million and adjusted EBITDA of $385 million to $395 million.
The bigger challenge is proving that growth can continue without Reddit becoming overly dependent on Google.
Reddit Is Expanding Beyond Its Traditional Growth Engine
That is why international expansion and the Feed experience could be so important.
Reddit is seeing strong growth outside the U.S., while its Feed audience is helping offset weaker Conversation growth. The company has also been seeing thousands of daily app downloads without Google attribution, according to CEO Steve Huffman.
That could become a major long-term positive.
Reddit is also trying to strengthen monetization as advertising becomes a larger part of the business. International growth gives Reddit more users to monetize, while higher ARPU suggests the platform is getting better at converting engagement into revenue.
At the same time, investors will continue watching Reddit’s data-licensing relationships with artificial intelligence (AI) companies. That business is smaller than advertising today, but future renewals could still have a meaningful impact on the stock.
What Do Analysts Think About Reddit Stock?
Wall Street remains broadly positive, but analysts are clearly becoming more cautious.
Morgan Stanley recently kept an “Overweight” rating while cutting its price target from $240 to $210. Meanwhile, Goldman Sachs has a “Neutral” rating and a $215 target, reflecting valuation concerns despite Reddit’s strong execution.
Raymond James was more optimistic, raising its target to $205 from $200 in August while maintaining a “Strong Buy” rating.
Baird analyst Colin Sebastian recently kept a “Neutral” rating with a $185 target, but argued that the market may already be pricing in a weak outcome for Reddit’s 2027 AI data-licensing renewals. A base-case renewal could add about $10 per share, while a bullish outcome could be worth another $20, according to the analyst.
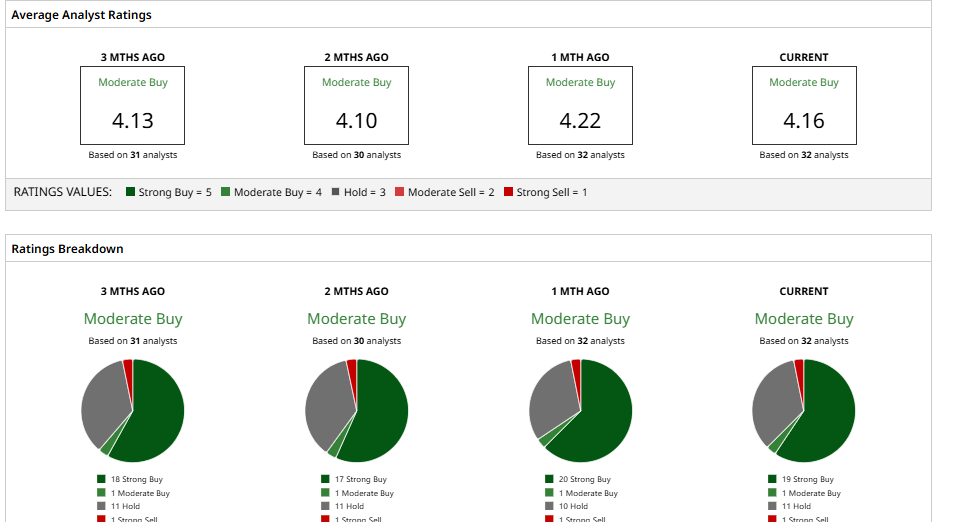
Barchart data shows a consensus "Moderate Buy" rating overall. The average price target of $211.18 implies roughly 34% potential upside from current levels.
For now, August user growth is the biggest reason to be bullish on Reddit stock. But one month is not enough to erase the concerns that have pushed shares down 30% this year. The next few months will show whether August was the start of a trend or simply a temporary relief rally.
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.