


Carvana (CVNA) Expands ADESA Charlotte As Its Valuation Story Comes Back Into Focus
Carvana (CVNA) is back in focus after the company moved to add Inspection and Reconditioning Center capabilities to its ADESA Charlotte auction site, expanding capacity and creating a fresh source of retail inventory.
Carvana’s recent push to expand Inspection and Reconditioning Center capacity comes as the share price trades at US$70.87, with the 1-day share price return up 2.47% but the 30-day move down 6.24%. This hints at mixed near term momentum, alongside a very large 3-year total shareholder return and a more muted 5-year and 1-year total shareholder return profile.
Scan beyond Carvana and focus on other auto and retail plays exhibiting resilient balance sheets and fundamentals with our curated list of solid balance sheet and fundamentals (23 results).
Carvana is pricing fresh IRC expansion at US$70.87 while consensus fair value sits higher. How wide is that gap, and what do the underlying valuation assumptions really point to?
Most Popular Narrative: 14% Undervalued
Carvana’s most followed valuation story pegs fair value at about $82.83, above the last close at $70.87. This comparison puts the new IRC expansion and current share price into sharper context.
The company's scaled logistics and reconditioning infrastructure, bolstered by the integration of ADESA locations, is driving lower delivery and inbound transport costs. As utilization rises, these investments are expected to further enhance operating leverage, improving gross margins and profitability.
See why 56 investors see Carvana as 14% undervalued.
Result: Fair Value of $82.83 (UNDERVALUED)
Still, the bullish Carvana narrative could crack if expansion spending fails to translate into higher unit throughput, or if digital competitors squeeze pricing power and margins.
Find out about the key risks to this Carvana narrative.
Another View: Carvana Looks Expensive On Earnings
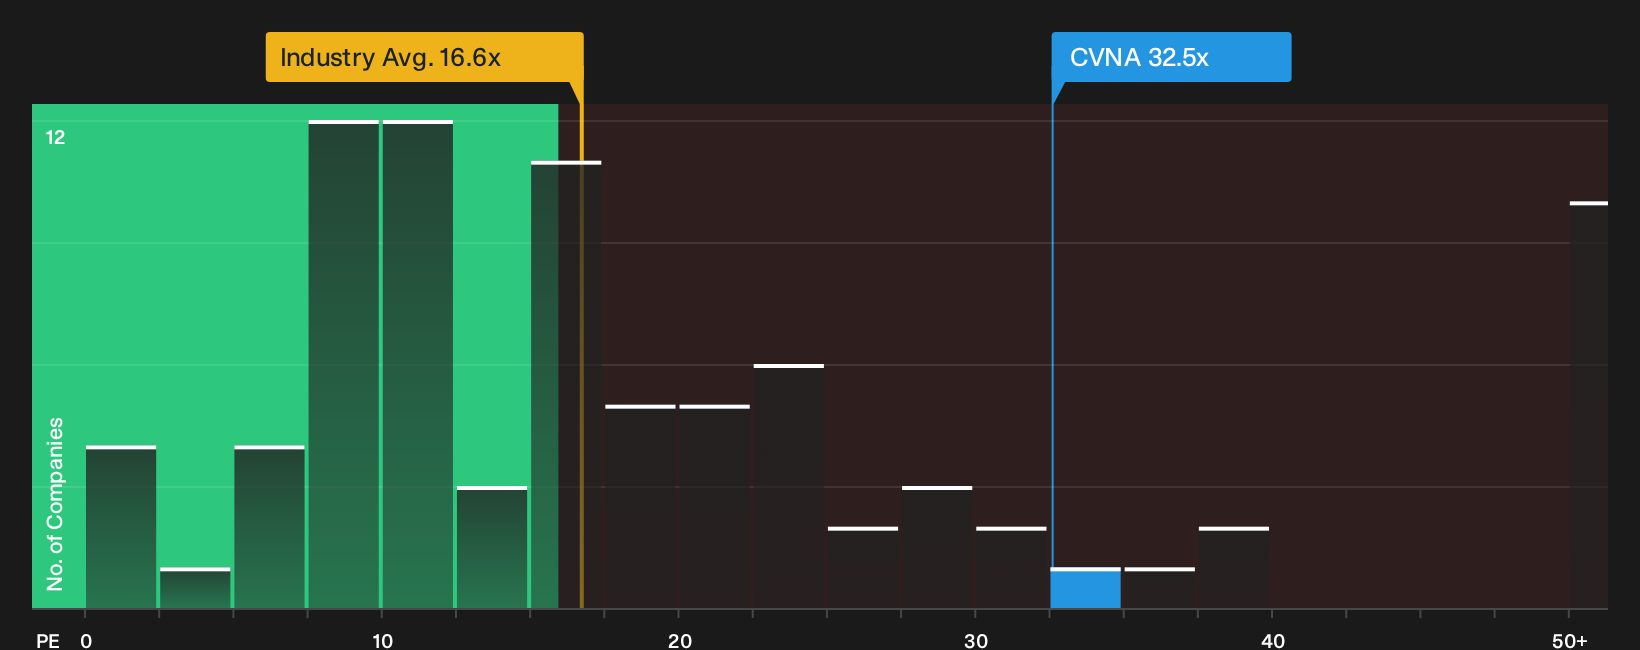
Look at Carvana through a simple earnings lens and the picture flips. The stock trades on a P/E of 32.5x, while the fair ratio sits nearer 26x. Both the US Specialty Retail industry at 16.6x and direct peers at 18.2x are far lower.
That gap implies investors are already paying a heavy premium for Carvana’s growth story. If the market drifts toward the fair ratio or closer to sector norms, valuation risk sits with anyone assuming the current multiple holds up indefinitely.
See what the numbers say about this price with our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown..
For a visual sense of how this premium compares against the broader sector, review
Next Steps
Mixed messages on Carvana’s valuation and fundamentals can be confusing, so move quickly, review the key charts and metrics, then weigh both sides through 2 key rewards and 1 important warning sign.
Looking for more Carvana sized ideas?
If Carvana has your attention, do not stop here. Broaden your watchlist with focused screeners that surface clear, data driven ideas you might otherwise miss.
- Target future growth potential by scanning a curated 15 high quality undiscovered gems that filters for strong fundamentals before wider attention arrives.
- Shield your portfolio from big shocks when you review a 11 resilient stocks with low risk scores that prioritizes resilient balance sheets and steadier return profiles.
- Hunt for mispriced quality using a 35 high quality undervalued stocks built to highlight companies where fundamentals and valuation tell two very different stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com