


Is Domino's Pizza (DPZ) Still Undervalued On Ohio Store Closures?
Domino's Pizza (DPZ) is back in focus after franchise operator Mile High Pizza Company shut 13 locations in North Central Ohio, with the parent franchisor now working to move those stores to new owners.
For Domino's Pizza investors, the short term has been choppy, with the 7 day share price return down 5.1% and the 30 day share price return down 6.5%. The 90 day share price return is slightly positive at 1.0%, while the 1 year total shareholder return is down 26.5%. This points to fading momentum over the past year as the market weighs events like the Ohio franchise closures against the broader expansion story.
Spot patterns in how Domino's Pizza is trading by comparing it with a curated 35 high quality undervalued stocks that pairs pressured share prices with stronger fundamentals.After that kind of drawdown in Domino's Pizza, with rare franchise closures now in the mix, the real issue is whether the current valuation still compensates you for those risks.
Most Popular Narrative: 21% Undervalued
Compared with Domino's Pizza last close of $323.77, the leading valuation narrative pegs fair value at $408.07. This frames the recent share price slide as a potential valuation gap rather than a structural reset.
Domino's Pizza is a great brand, enjoying a wide moat that results in an operating margin of around ~20%. Given the maturity of the business, its revenue growth is below 10% but still modestly above the economy growth rate. Its franchise business model and disciplined capital allocation decisions also result in a stellar ROIC around 10 times its cost of capital. The reduction in shares outstanding over the last five years has also increased each shareholder's ownership stake "pizza slice" in the company.
See why 12 investors see Domino's Pizza as 21% undervalued.
Result: Fair Value of $408.07 (UNDERVALUED)
Still, the Domino's Pizza story could be knocked off course if franchisee stress spreads beyond Ohio, or if long term consumer demand for delivered pizza softens.
Find out about the key risks to this Domino's Pizza narrative.
Another View On Domino's Pizza Valuation
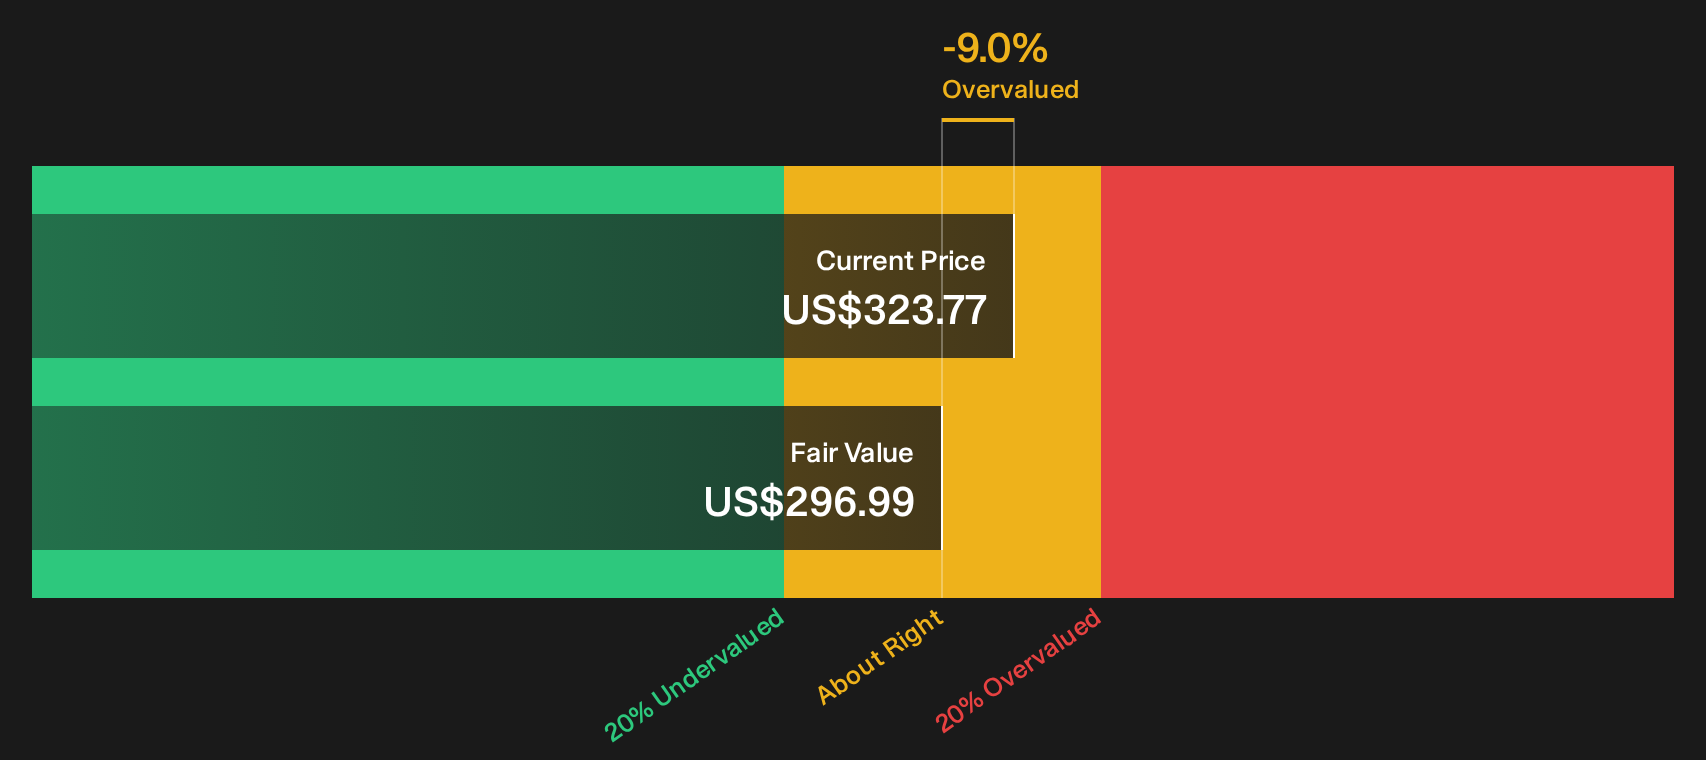
The Simply Wall St DCF model presents a different perspective on Domino's Pizza. At a last close of $323.77, the DCF fair value estimate is $296.99, which frames the stock as overvalued using this cash flow lens. Which story do you consider more reliable: the narrative fair value of $408.07 or the modeled cash flow output?
Our DCF model makes every assumption visible so you can evaluate the inputs rather than focusing only on the headline number. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Domino's Pizza for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
This mixed sentiment around Domino's Pizza, with both pressure points and bright spots in view, is exactly why you should move quickly and test the numbers against your own expectations using the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Domino's Pizza?
If Domino's Pizza has you rethinking your playbook, widen your watchlist now and stress test fresh ideas before the next swing in sentiment catches you off guard.
- Target reliable income streams by reviewing a curated group of 6 dividend fortresses that focus on durability as much as yield.
- Hunt for quality selling at a discount through a focused 35 high quality undervalued stocks that blends strong balance sheets with appealing prices.
- Get ahead of the crowd by scanning a 15 high quality undiscovered gems built to surface under-the-radar businesses with solid fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com