


GeneDx Holdings (WGS) Launches NPC Testing Program Following Collaboration as Valuation Stays In Focus
GeneDx Holdings (WGS) just announced a collaboration with Beren Therapeutics to launch the NPC GenomeComplete Sponsored Testing Program, offering no cost genome sequencing for pediatric patients at risk of Niemann Pick Disease Type C.
The collaboration headlines arrive after a sharp rebound in GeneDx Holdings' share price, with a 1-day share price return of 5.25% and a 90-day share price return of 48.09%. This comes even though the year-to-date share price return has fallen 32.17% and the 1-year total shareholder return is down 26.47%, while the 3-year total shareholder return remains extremely high at more than 20x.
Spot 40 healthcare AI stocks that, like GeneDx Holdings, are trying to turn complex genomics and AI-driven diagnostics into real-world impact for patients and their families.GeneDx Holdings now pairs fast growing rare disease testing with a share price that has already swung hard in both directions. Is this a strong genomics business being mispriced, or has the rebound already done its work?
Most Popular Narrative: 80% Undervalued
GeneDx Holdings closed at $89.74, while the most followed narrative pegs fair value at about $90.44, and yet that same framework still treats the stock as deeply undervalued once long term cash flows are modeled at a 7.24% discount rate.
Rapid expansion into new and underpenetrated markets, including general pediatrics (driven by American Academy of Pediatrics guidelines), NICU, and additional pediatric specialties, positions GeneDx for substantial future volume and revenue growth as adoption of genomics as a frontline diagnostic tool accelerates.
Scaling proprietary AI-powered genomic interpretation platforms and integrating newly acquired Fabric Genomics technology enhances efficiency and accuracy, which should both lower per-sample costs and support margin expansion as the business grows.
See why 26 investors see GeneDx Holdings as 1% undervalued.
Result: Fair Value of $90.44 (UNDERVALUED)
Still, GeneDx Holdings faces real pressure if reimbursement policies tighten or if pediatric and NICU adoption moves more slowly than current analyst models assume.
Find out about the key risks to this GeneDx Holdings narrative.
Another View: What Multiples Say About GeneDx Holdings
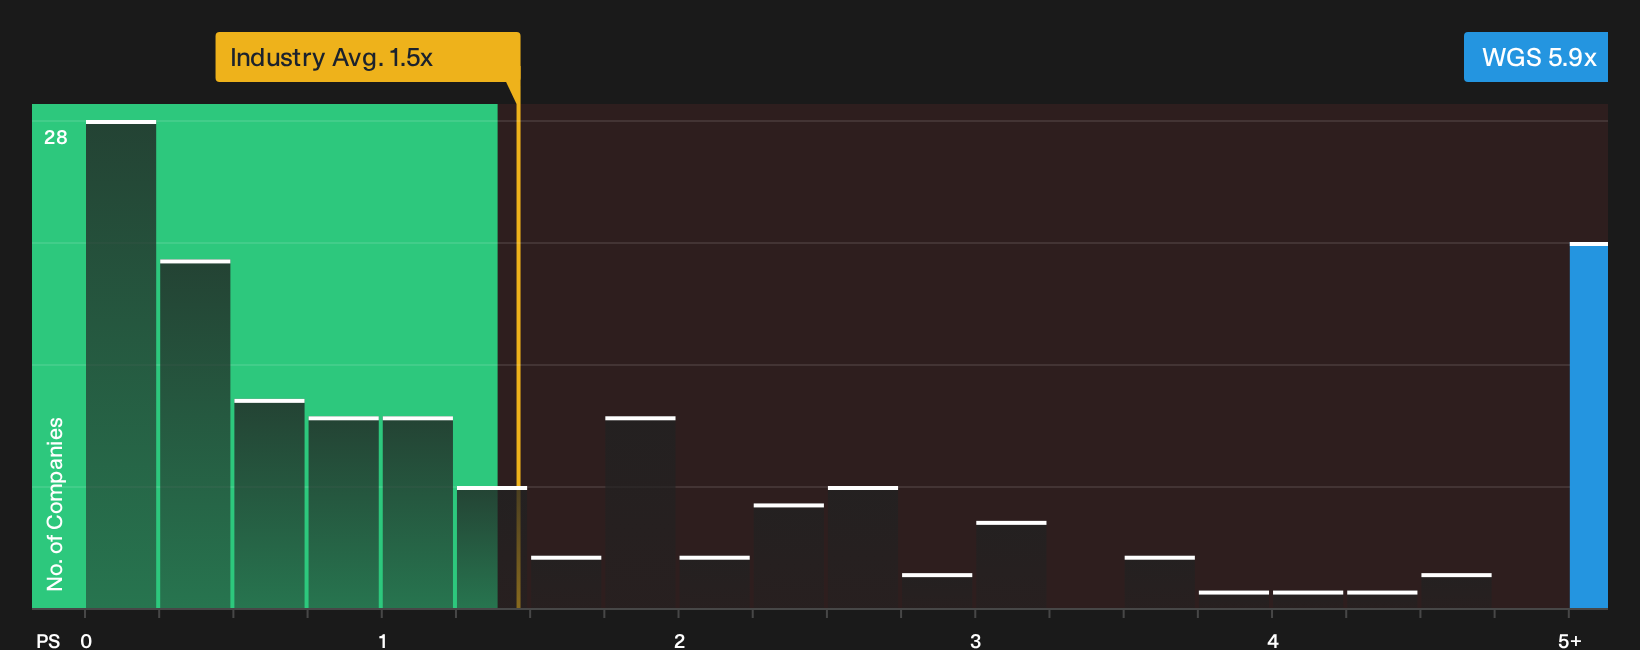
Our DCF work points to GeneDx Holdings trading at a steep discount, yet the market is already attaching a rich tag to current revenues. The stock changes hands at a P/S ratio of 5.9x, compared with 1.5x for the broader US Healthcare industry and 1.3x for direct peers.
The fair ratio sits closer to 4.9x. That gap means investors are already paying a premium against both sector averages and the level our fair ratio suggests the market could drift toward. The key question is whether strong growth expectations justify that premium, or whether it leaves less room for error.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around GeneDx Holdings is clearly divided, which is exactly when fresh data can matter most. Move quickly, review both the upside and the risks, then judge the 2 key rewards
Looking for more investment ideas beyond GeneDx Holdings?
Do not stop with a single genomics story when there are other opportunities that could better match your goals and risk comfort.
- Zero in on quality at a discount by scanning companies screened as 35 high quality undervalued stocks that may offer stronger fundamentals for the price.
- Strengthen the defensive side of your portfolio by reviewing a list of solid balance sheet and fundamentals (23 results) that can help cushion tougher conditions.
- Stay ahead of the crowd by checking a 15 high quality undiscovered gems that flags under-the-radar businesses with solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com