


What AXA Shareholders Should Know About AXA (ENXTPA:CS) New Plan Call
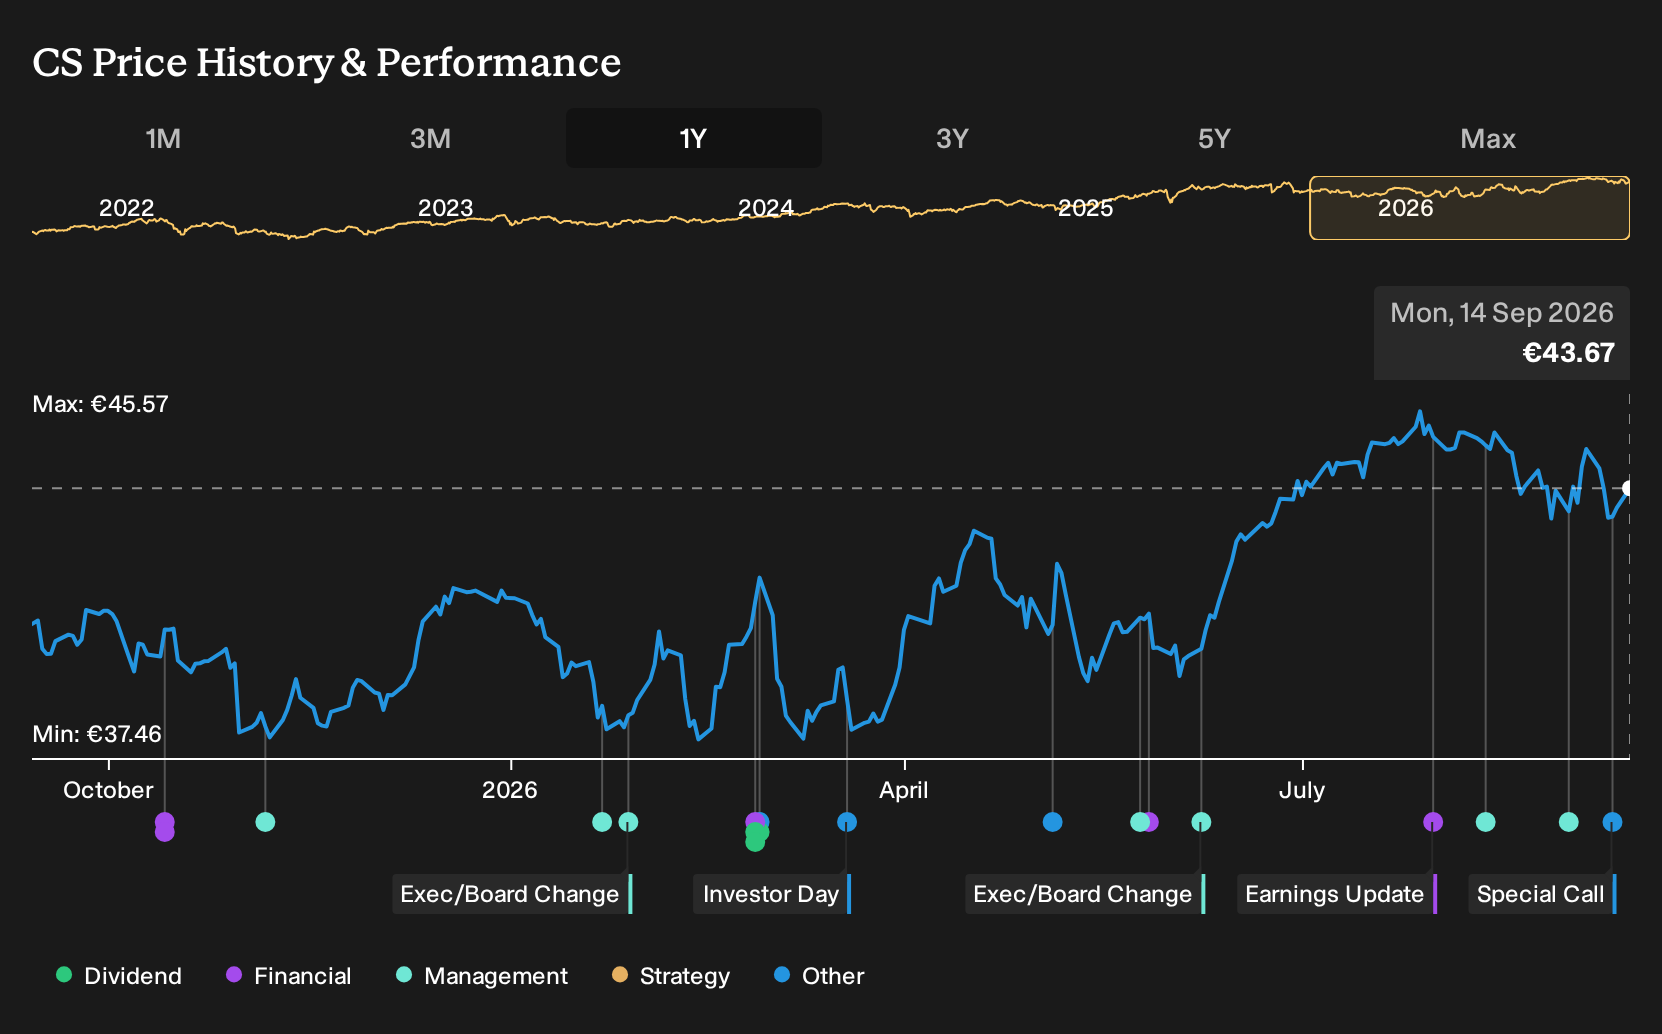
- AXA recently held a special call to present a new strategic plan, outlining management's updated priorities for its insurance, asset management, and related services businesses.
- The new roadmap provides investors with a clearer view of how AXA intends to balance growth, cost discipline, and capital allocation across its core franchises.
- We now examine how AXA's new strategic plan call could reshape the existing investment narrative around efficiency and growth.
Compare AXA's refreshed plan with peers by scanning a curated set of insurers and financials that also score well on capital discipline and balance sheet strength through our list of solid balance sheet and fundamentals (194 results).
AXA Investment Narrative Recap
To own AXA, you need to be comfortable with a story built on steady insurance operations, disciplined use of capital and incremental efficiency gains rather than rapid expansion. The new plan mainly sharpens how management communicates those priorities. It does not radically change the near term focus on underwriting quality, expense control and health and protection lines.
The key near term swing factor still looks like execution on cost and digital projects that are expected to support margins and earnings. The biggest operational risk remains pressure on reinsurance and commercial pricing, combined with climate related claims volatility, which could hold back reported profitability if conditions stay soft.
Among recent themes, management emphasis on digitalization and AI in the plan discussion is most relevant. AXA has already been investing in tools such as its GenAI chatbot Sophia and digital assistant EMMA. The refreshed roadmap ties these efforts more tightly to goals around lower expense ratios and better direct engagement with customers.
For you as a shareholder, that matters because cost discipline and efficient distribution sit right at the center of the current catalysts. Progress on technology and process simplification could influence margins, while any delays, cost overruns or weaker than expected take up from customers would quickly show up in profitability and cash generation.
AXA's analyst narrative points to revenues of €121.9b and earnings of €9.5b by 2029, based on 8.8% yearly revenue growth and an earnings increase of about €2.2b from current earnings of €7.3b.
Uncover why AXA's fair value points to an 11% potential upside to its current price, which could narrow faster than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts focus on AXA’s exposure to new climate and technology related risks as a potential upside swing factor, expecting revenues of about €142.2b and earnings of €10.3b by 2029, compared with consensus views around €121.9b and €9.5b. Those projections were set before this new strategic plan call, so you may see them evolve. Use this gap in expectations as a prompt to compare several narratives and decide which assumptions align most closely with your own.
Explore 3 other AXA fair value estimates, including one that suggests as much as 123% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your AXA research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AXA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AXA's overall financial health at a glance.
Looking for more investment ideas beyond AXA?
Once you have a view on AXA, it often helps to place that thesis alongside a wider watchlist. The Simply Wall St Screener can surface other companies with similar qualities or complementary profiles so you are not relying on a single stock to carry your whole plan.
- If you want to focus on companies that combine strong fundamentals with relatively low valuation multiples, you can scan a curated set of 192 high quality undervalued stocks that may warrant a closer look.
- For readers who care most about stability and capital protection, you might prefer to start with a group of 103 resilient stocks with low risk scores that our filters flag as having more resilient characteristics.
- If you enjoy finding less crowded situations before they hit the mainstream, it could be worth reviewing a hand picked set of 618 high quality undiscovered gems that already show solid financial quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com