


Did New Farm Equipment Launches Just Shift AGCO's (AGCO) Investment Narrative?
- AGCO used the 2026 Farm Progress Show to roll out new high-spec Fendt tractors and planters, alongside Massey Ferguson N-Series split and narrow row planters that combine modular hardware with factory-installed Precision Planting systems.
- The focus on factory integration of precision technology and modular add-ons signals AGCO's push to deepen equipment value while keeping upgrade paths flexible and ownership complexity contained for large producers.
- We will now look at how AGCO's precision-equipped Fendt and Massey Ferguson launches could influence the company's long-term investment narrative.
AGCO Investment Narrative Recap
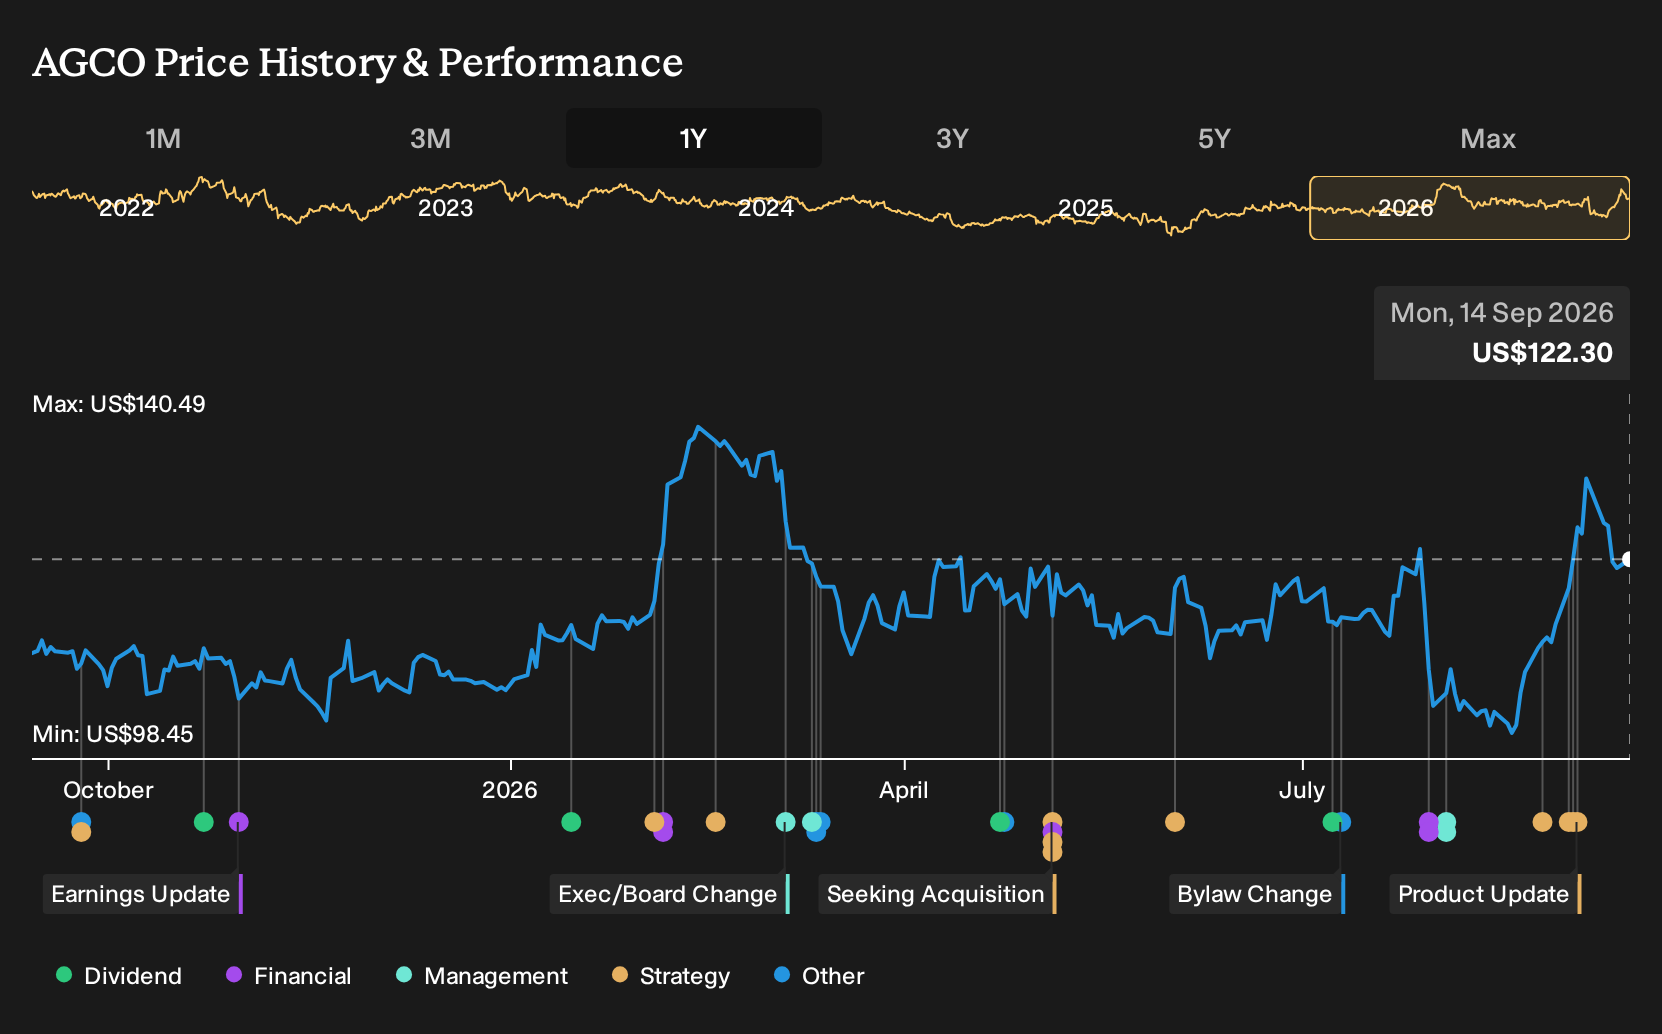
To own AGCO, you need to believe that premium equipment and precision technology can offset softer demand in key markets over time. The recent Farm Progress launches and the upcoming Morgan Stanley Laguna appearance point to management leaning into that higher spec mix. The biggest near term swing factor remains how quickly dealer inventories and order rates in North America and Europe normalize.
The key risk still sits with weaker farmer sentiment and policy noise that could keep fleets parked longer and pressure margins, especially with a high debt load. The latest product cycle does not erase that exposure. It mainly raises the stakes on AGCO executing cleanly on pricing, production and aftermarket pull through.
The Fendt 1100 Vario MT Gen2 Track Tractor and Momentum 80 foot planter announcement is the clearest operational tie in to these catalysts. Both products cluster around large farms that care about uptime, fuel efficiency and precision planting, which links directly to AGCO's push into higher margin technology and services rather than pure horsepower alone.
For you as an investor, the question is whether this premium, precision heavy portfolio can support earnings quality even if unit volumes stay under pressure. Execution risk is real, from tariff related cost pressure to dealer profitability. The upcoming Morgan Stanley Laguna conference should help clarify how management sees these launches feeding into mix, margins and capital allocation over the next few years.
AGCO's current analyst narrative points to US$12.3b in revenue and US$879.9m in earnings by 2029, based on an assumed 6.0% yearly revenue growth rate and an earnings increase of about US$346.5m from US$533.4m today.
Uncover why AGCO's fair value indicates performance that is in line with its current price.
Exploring Other Perspectives
One alternate view zooms in on long term demand risk. The most cautious analysts see slower equipment needs and model only 2.6% yearly revenue growth, with earnings at about US$665.9m by 2029 instead of the US$879.9m consensus. Those estimates were set before AGCO’s Farm Progress launches and the Laguna conference, so you may want to compare these contrasting assumptions and decide which story feels closer to how you see the next decade playing out.
Explore 2 other AGCO fair value estimates, including one that suggests it could be worth just $125.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AGCO research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AGCO. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AGCO's overall financial health at a glance.
Looking For More Ideas Beyond AGCO?
If the AGCO story has sharpened your thinking, you can broaden the watchlist by scanning other businesses that fit the kind of quality, resilience or upside you are looking for using the Simply Wall St Screener.
- For investors who want potential upside without paying up for quality, start by reviewing 35 high quality undervalued stocks that combine solid fundamentals with more appealing entry prices.
- If capital preservation and smoother portfolio swings matter most to you, focus on companies screened for resilience using our 11 resilient stocks with low risk scores that put balance sheet strength and stability front and center.
- When you want to get ahead of the crowd and research stories that are not yet widely followed, scan our 15 high quality undiscovered gems with strong underlying metrics but limited market attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com