


How Earnings Miss Will Impact Cal Maine Foods Stock Investors
- Cal-Maine Foods reported quarterly revenue of $552.6 million, which was 49.9% lower year on year and missed analyst expectations on sales, gross margin, and earnings.
- The weaker quarter puts more attention on Cal-Maine Foods' efforts to adjust its product mix and maintain a strong balance sheet in a volatile egg market.
- This revenue shortfall and margin disappointment raises questions about Cal-Maine Foods' broader investment narrative.
Cal-Maine Foods Investment Narrative Recap
To own Cal-Maine Foods, you need to believe this egg producer can turn a highly cyclical commodity business into a steadier mix of specialty eggs and prepared foods, supported by tight cost control and strong biosecurity. The recent revenue and margin miss puts more pressure on that transition, but it does not change the basic thesis.
In the near term, the key swing factor is whether Cal-Maine Foods can stabilise profitability while egg pricing and volume remain choppy. The biggest risk remains disease and industry oversupply, which can quickly hit pricing and farm level costs. The weak quarter keeps that risk front of mind rather than introducing a new one.
The new US$250 million senior unsecured revolving credit facility is the most relevant fresh data point alongside the weak quarter. Cal-Maine Foods currently has no borrowings under this agreement, with only US$5.9 million in standby letters of credit drawn, so it functions as liquidity insurance rather than active leverage.
For you as a shareholder, this matters because it gives the business flexibility to fund working capital, capex or acquisitions if egg markets stay volatile, without relying on issuing equity. The covenants around leverage and minimum tangible net worth also act as guardrails, which can limit balance sheet risk but may constrain aggressive expansion if results soften.
Cal-Maine Foods' current earnings sit at US$695.0 million, with analysts forecasting earnings of US$102.8 million by 2029 on revenue of US$2.7b. This implies revenue declining 8.0% per year and an earnings drop of US$592.2 million over that period.
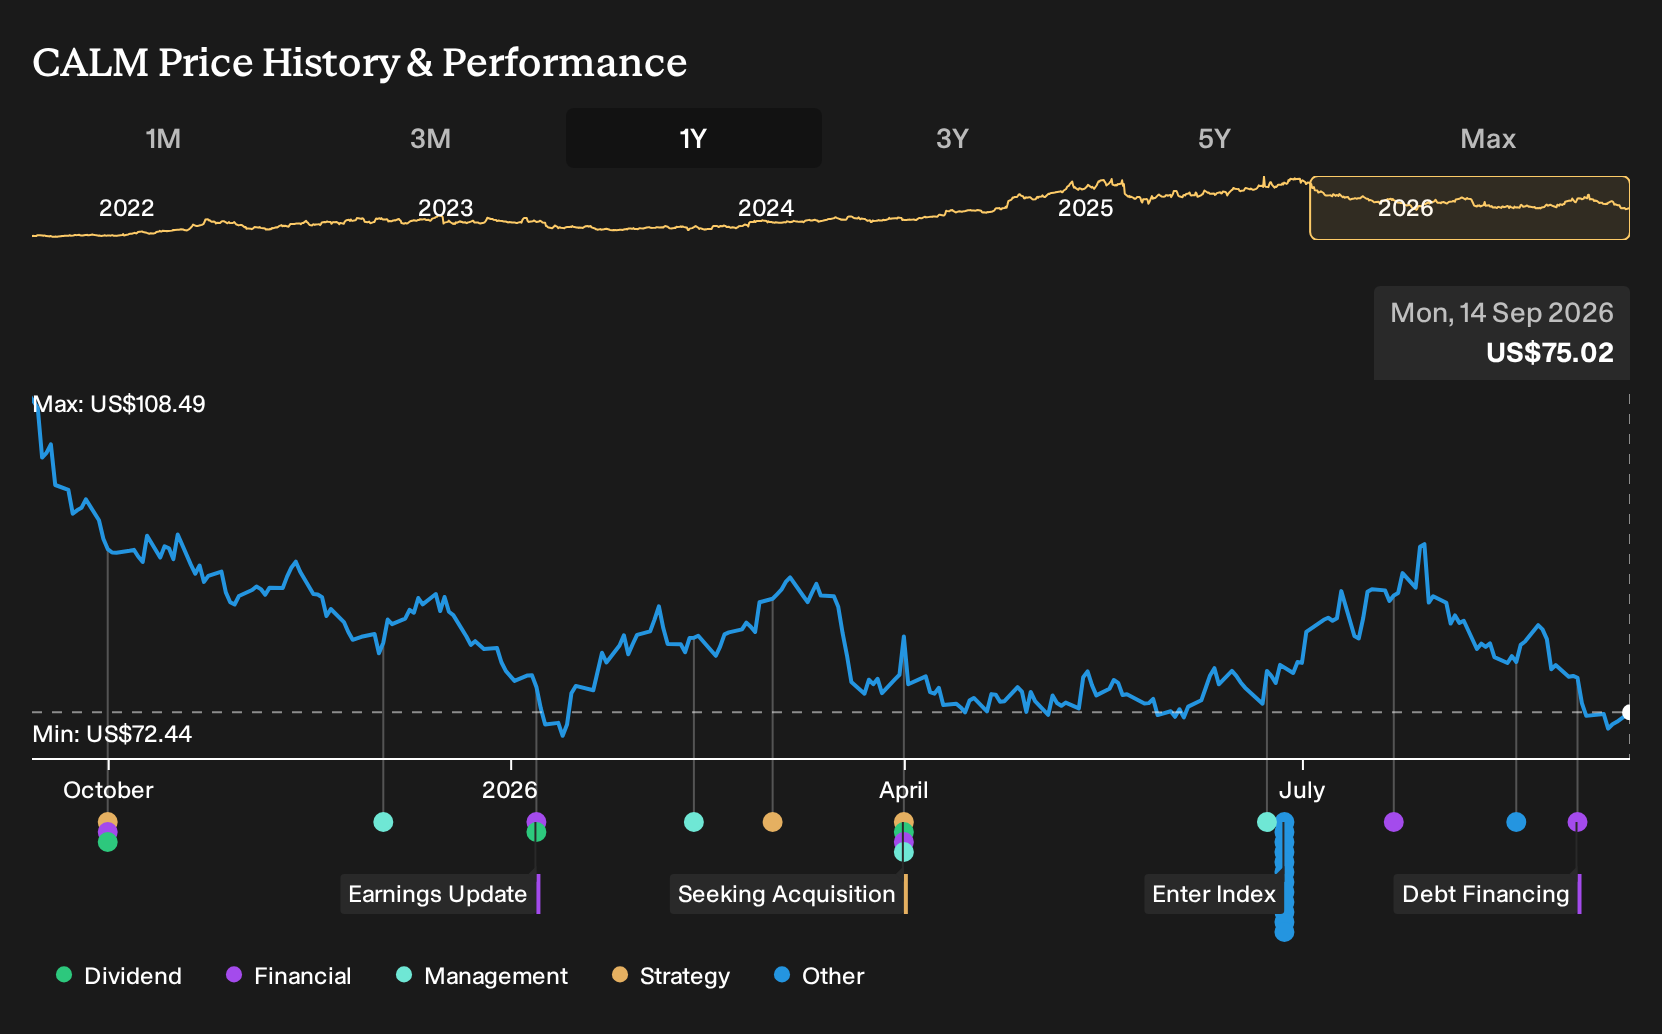
Uncover why Cal-Maine Foods' fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community cluster between about US$75.62 and US$104 per share, so retail views on Cal-Maine Foods already span a wide band. Those opinions do not yet reflect the new US$250 million revolving credit facility, which could reshape how investors think about balance sheet resilience and earnings risk. It may be useful to explore the full spread of community views rather than relying too heavily on any single forecast.
Explore 5 other Cal-Maine Foods fair value estimates, including one that suggests as much as 39% higher than the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cal-Maine Foods research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cal-Maine Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cal-Maine Foods' overall financial health at a glance.
Looking for more investment ideas beyond Cal-Maine Foods?
If the Cal-Maine Foods story has you thinking about portfolio balance, it can help to scan a wider field of stocks that match your risk and income preferences using the Simply Wall St Screener.
- For investors who want potential upside without paying up for quality, consider reviewing our list of 15 high quality undiscovered gems that already show solid fundamentals and room for broader market attention.
- If capital preservation and steady operations matter most to you, focus on businesses with strong finances by filtering for a list of solid balance sheet and fundamentals (23 results) to find companies with healthier cushions against shocks.
- For those building a portfolio around regular cash returns, scan income ideas by checking out 6 dividend fortresses that combine higher yields with a focus on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com