


Sonos (SONO) Shares Climbed, So What Is Behind The Move?
Sonos (SONO) just tied a major software update to a fresh hardware lineup and a new global brand push, putting the Sonos 27 platform along with the Beam Ultra and Ace Ultra launch at center stage for investors.
Against this product and software rollout, Sonos shares closed at US$15.58 on 13 September and have seen a 3.04% 1-day share price return and a 4.99% 90-day share price return. Total shareholder return is roughly flat over one year and positive over three years but still well below five-year levels. This points to momentum rebuilding from a low base as investors reassess growth potential and risk around the new platform and hardware cycle.
Scan how Sonos fits into the wider audio and AI hardware story by lining it up against 60 AI infrastructure stocks shaping the next wave of connected home systems.
Sonos now trades below both analyst targets and one estimate of intrinsic value after this product reset. Is that a simple discount, or a fair warning label on the story investors are being asked to pay for next?
Most Popular Narrative: 1% Overvalued
At a last close of $15.58, the most followed narrative pegs Sonos fair value at $15.50, implying only a slight premium that puts execution, not big mispricing, in focus.
Sonos's efforts to differentiate via platform and software are constrained by higher research and development costs, while diminishing marginal returns on innovation make it difficult to achieve significant margin expansion. This ultimately limits future growth in both earnings and net profit.
The growing prominence of sustainability regulations and right-to-repair laws could require costly product and supply chain redesigns, raising operating expenses and extending development timelines. This would further pressure net margins and delay the realization of new revenue streams.
See why 1 investors see Sonos as 1% overvalued.
Result: Fair Value of $15.50 (OVERVALUED)
Still, a stronger Sonos platform story and a sizeable net cash position could yet shift sentiment if software traction and cost discipline emerge in coming updates.
Find out about the key risks to this Sonos narrative.
Another View: Sonos Through A Cash Flow Lens
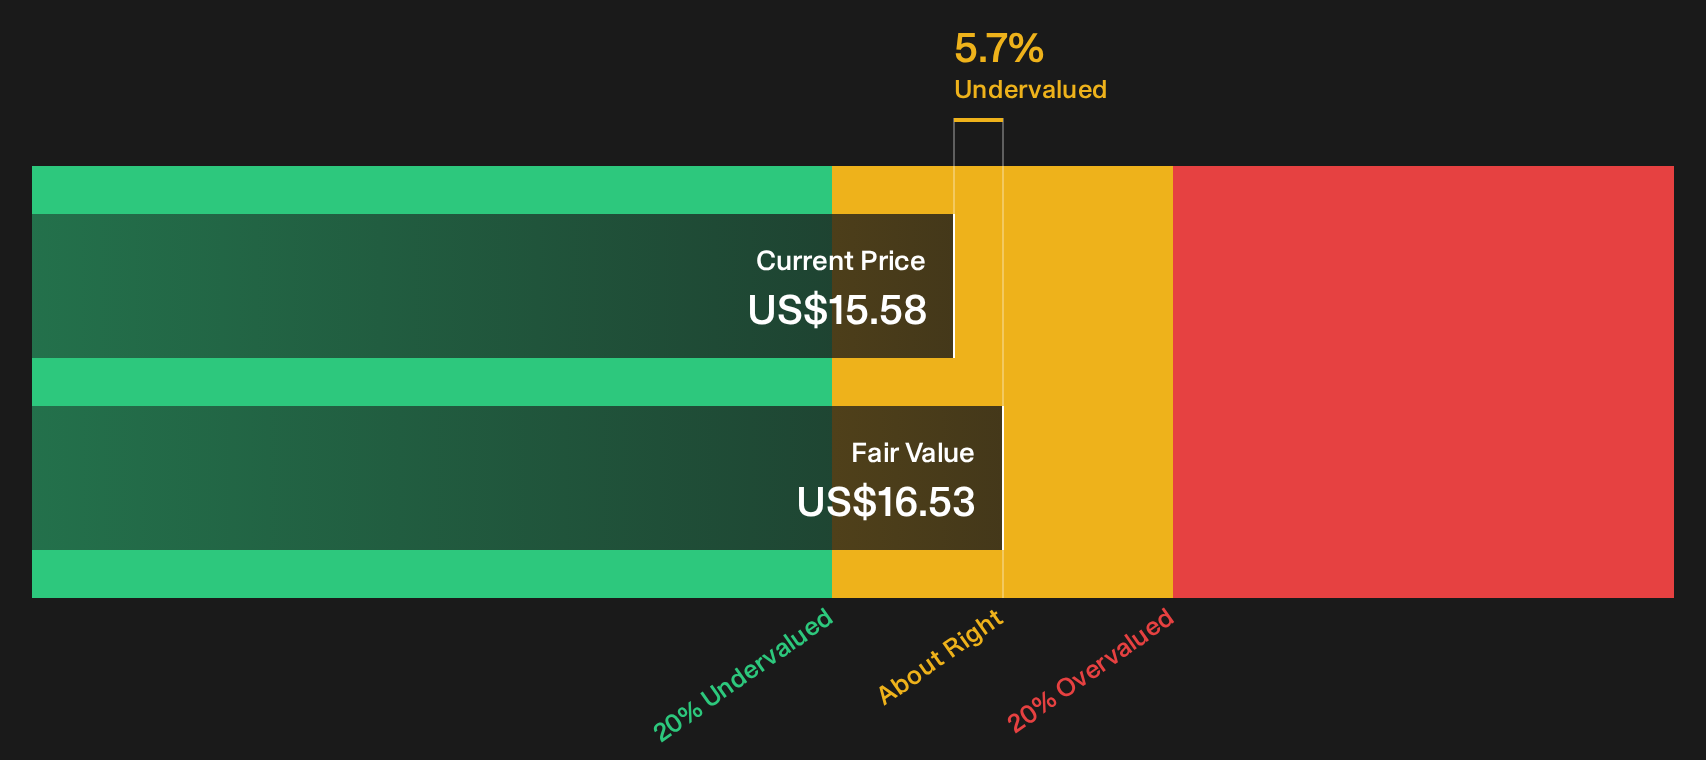
Where the prevailing Sonos narrative leans on earnings and multiples, the SWS DCF model tells a slightly different story. At $15.58, the stock sits about 5.7% below an estimated future cash flow value of $16.53, which frames it as modestly undervalued rather than overvalued. That gap is small, yet it raises a simple question: Which set of assumptions do you trust more, the earnings-based fair value of $15.50 or the cash flow view pointing a little higher?
For anyone weighing those two signals, it can help to see how the SWS DCF model connects cash generation, discount rate, and terminal expectations to that $16.53 figure. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sonos for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Sonos is mixed, so it helps to move quickly, pull up the key positives, and decide whether the upside justifies the risk profile. To see the specific bright spots investors are watching, start with the 3 key rewards.
Looking for more investment ideas beyond Sonos?
If Sonos has sharpened your focus on where to deploy your next dollar, do not stop here. You owe it to yourself to compare options.
- Target resilient growth by scanning a 35 high quality undervalued stocks that combines quality fundamentals with pricing that still looks reasonable on the numbers.
- Prioritise staying power by reviewing a list of solid balance sheet and fundamentals (23 results) so you can focus on businesses with stronger financial footing when conditions get tougher.
- Hunt for tomorrow's potential outliers through a curated 15 high quality undiscovered gems before the wider market starts paying closer attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com