


ASICS (TSE:7936) Is Back In The Spotlight, But What Is Driving It?
ASICS (TSE:7936) has announced a new share buyback after its board approved a plan to repurchase up to 20,000,000 shares for ¥70,000 million, with the program running through January 31, 2026.
The new ASICS buyback comes after a choppy stretch for the share price. The 1-day share price return was 0.86% and the 7-day share price return was 1.41%. These shorter-term gains followed a 30-day share price return that declined 22.25%. The year-to-date share price return of 6.68% compares with a 1-year total shareholder return of 1.68% and a very large 5-year total shareholder return. This suggests that long term holders have seen strong compounding even as recent momentum has faded and the market reassesses the risk and reward trade off at around ¥4,106 per share.
Capitalize on ASICS's new buyback spotlight and scan a curated 74 high quality undiscovered gems that may be flying under the radar in similar consumer-focused niches.The recent pullback and fresh ASICS buyback raise a sharper question. Is most of the easy upside already in the rear-view mirror, or do current prices still leave room for meaningful value?
Price-to-Earnings of 22.7x: Is it justified?
The valuation on ASICS currently leans toward the expensive side, with a P/E of 22.7x against a share price of ¥4,106 and a recent pullback that has already reset some expectations.
The P/E ratio compares what investors pay per share with the earnings that ASICS generates per share. For a consumer durables group with global brands and meaningful profitability, this metric often reflects how much growth and earnings quality the market is willing to pay for.
Right now, the P/E of 22.7x sits above the estimated fair P/E of 22.1x. That gap is small in absolute terms, but it still points to investors assigning a premium over where the market could settle if sentiment or growth assumptions cool.
The premium looks more pronounced when stacked against the JP Luxury industry average P/E of 15.2x. That is a clear signal that buyers are paying a materially higher multiple for ASICS than for peers with similar sector exposure.
Explore the SWS fair ratio for ASICS.
Result: Price-to-Earnings of 22.7x (OVERVALUED)
Still, ASICS faces clear risks if consumer demand softens in key regions or if the new buyback does not offset any future swings in sentiment.
Find out about the key risks to this ASICS narrative.
Another View on ASICS: Cash Flows Tell a Different Story
The earlier P/E check pointed to ASICS looking a bit expensive at 22.7x earnings. The SWS DCF model comes at it from a different angle and suggests the shares at around ¥4,071 trade below an estimated future cash flow value of roughly ¥5,263. That gap implies cash flows paint a more generous picture than the current earnings multiple, which leaves you asking which signal deserves more weight.
Look into how the SWS DCF model arrives at its fair value.
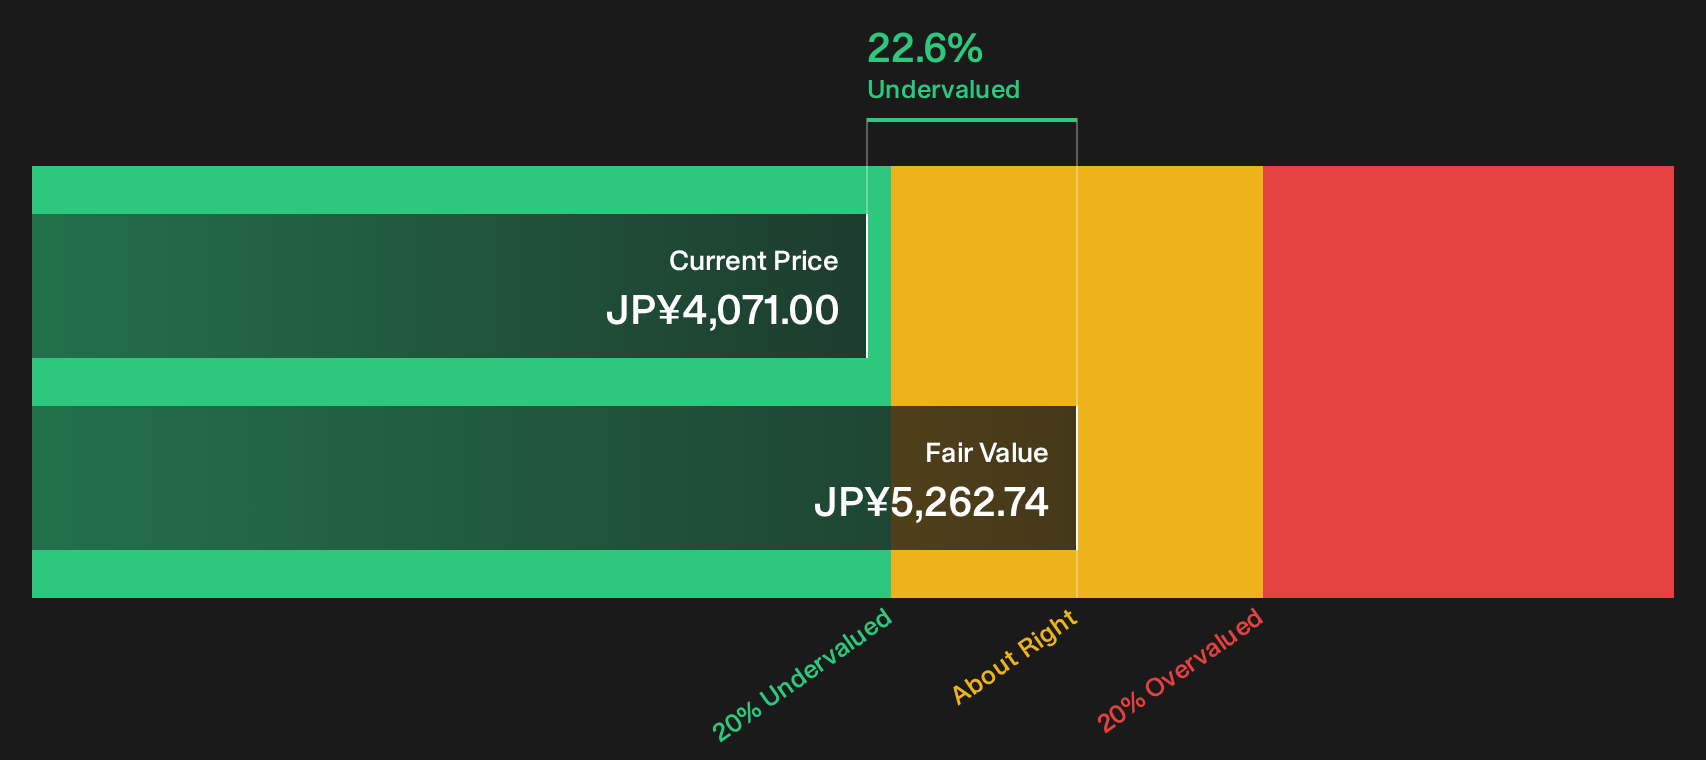
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ASICS for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ASICS do not settle the debate for you; they just frame it. Act while the data is fresh and weigh both sides by checking the 4 key rewards and 1 important warning sign.
Looking for more ASICS sized investment ideas?
ASICS gives useful clues, but your next move comes from widening the opportunity set. Use the Simply Wall Street Screener to test fresh ideas with clear numbers behind them.
- Hunt for quality at a discount by scanning a curated 17 high quality undervalued stocks that filters for fundamentals the market may be underpricing.
- Lock in potential income streams by reviewing a focused 18 dividend fortresses that highlights companies offering yields with supporting financials.
- Dial back potential volatility by assessing a carefully filtered 12 resilient stocks with low risk scores that focuses on businesses with more resilient profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com