


How Green Bond Issuance At Hokkaido Electric Power Company Stock Has Changed Its Investment Story
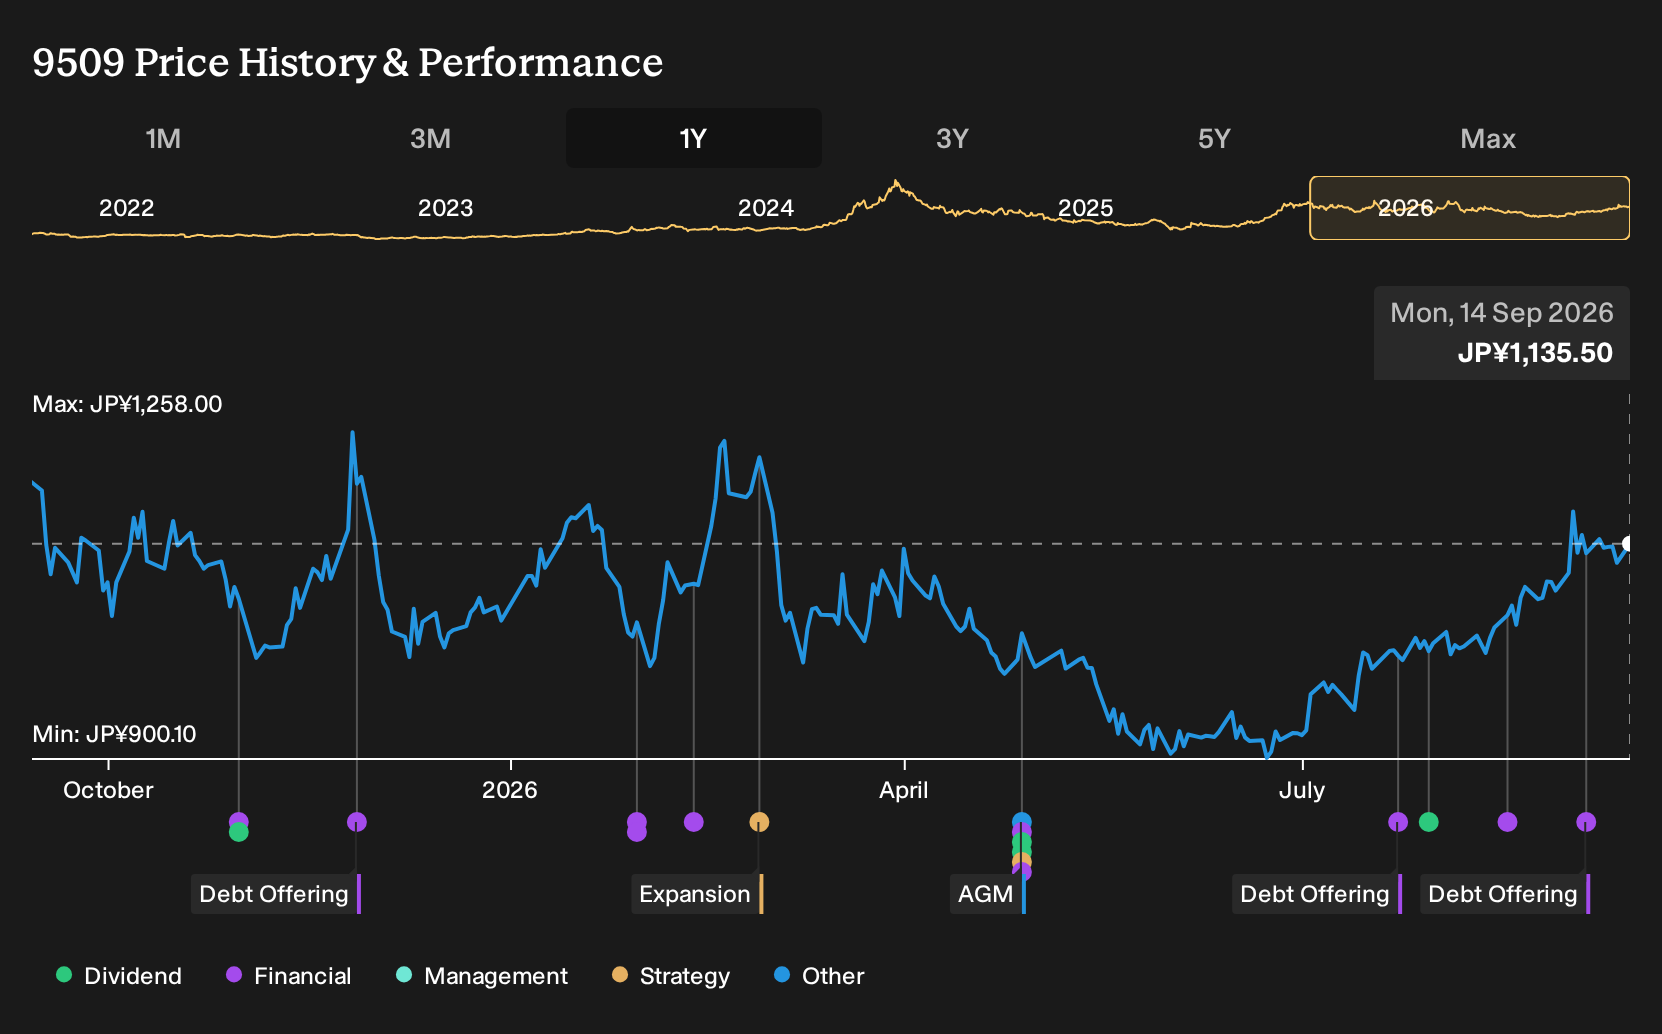
- Hokkaido Electric Power Company, Incorporated completed a ¥30 billion fixed income issuance of unsecured straight green bonds due September 25, 2036, priced at 100% of principal.
- The green bond structure signals a focused funding pool for climate related projects, which could influence how investors assess Hokkaido Electric Power Company's long term capital allocation and sustainability plans.
- We will now look at how Hokkaido Electric Power Company's green bond funding move could shape its broader investment narrative for investors.
Scan how Hokkaido Electric Power Company's green bond move compares with peers by zeroing in on 38 power grid technology and infrastructure stocks aligned with long term infrastructure and grid upgrade themes.
What Is Hokkaido Electric Power Company's Investment Narrative?
To own Hokkaido Electric Power Company, you need to be comfortable with a capital intensive utility that earns relatively low but currently growing margins and leans heavily on external borrowing. Earnings are forecast to grow 16.9% a year while revenue is expected to rise 2.5% a year, so the story hinges on execution, cost control and stable demand rather than rapid top line expansion. The recent ¥30 billion green bond fits that picture as another funding tool rather than a short term earnings catalyst.
What changes near term is the funding mix and interest burden. Debt is already not well covered by operating cash flow, and the dividend around 2.91% is not well supported by free cash flow, so more unsecured borrowing raises the bar on operational delivery. The stock trades on an 8.8x P/E, below the wider Japan market but above some peers. That puts even more attention on whether management can protect its 3.1% profit margin after last year’s drop from 6.9%.
Yet there is one funding related wrinkle that could matter more than the coupon on this green bond once you look at ...
There's only one way to know the right time to buy, sell or hold Hokkaido Electric Power Company. Head to Simply Wall St's company report for the latest analysis of Hokkaido Electric Power Company's Fair Value.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hokkaido Electric Power Company research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hokkaido Electric Power Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hokkaido Electric Power Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hokkaido Electric Power Company?
If you want to put Hokkaido Electric Power Company in context, compare it with other opportunities using the Simply Wall St Screener before deciding where your next yen should go.
- For investors who care most about price versus quality, scan a curated mix of attractively priced businesses through 17 high quality undervalued stocks that already pass strict fundamental checks.
- If resilience matters more than rapid growth, focus on capital preservers by reviewing a 12 resilient stocks with low risk scores that aims to keep balance sheets and risk profiles front and center.
- For those hunting for less crowded ideas, broaden your watchlist with a 74 high quality undiscovered gems that highlights companies with strong fundamentals yet limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com