


Navan (NAVN) Could Be 31% Undervalued Following Earnings And New Guidance
Navan earnings and guidance in focus
Navan (NAVN) just reported second quarter results alongside new guidance that now stretches through fiscal 2027, giving investors more concrete revenue markers to track.
Second quarter sales were US$232.79 million, compared with US$171.95 million a year earlier. The business still reported a net loss of US$29.12 million, versus US$38.62 million in the prior year period.
Basic loss per share from continuing operations for the quarter was US$0.11, compared with US$0.83 a year ago. For readers watching dilution, that per share figure helps frame how headline losses translate at the individual share level.
Across the first six months to July 31, 2026, Navan reported sales of US$453.02 million, compared with US$329.41 million a year earlier. Net loss for the half was US$49.62 million, versus US$99.88 million in the same period last year.
Basic loss per share from continuing operations over the six month period was US$0.20, compared with US$2.15 a year ago. That gap between total loss and per share loss can matter for investors assessing how share count and reported performance interact.
On the outlook side, management now expects third quarter revenue between US$253 million and US$255 million, which it describes as implying 30% year over year growth at the midpoint. Full year revenue guidance has been raised to a range of US$927 million to US$933 million, which the company characterizes as 32% growth at the midpoint.
Navan’s stock has swung sharply around these headlines, with a 1-day share price return of 1.67%, a 7-day share price return that fell 23.07%, and a 30-day share price return down 26.95%. The year-to-date share price return is still up 31.51%, suggesting that longer term momentum has held up better than the recent pullback might imply.
Compare Navan’s latest swing in guidance and share price with a curated set of peers by scanning 15 high quality undiscovered gems that may be flying under most investors’ radar.
Navan’s shares have slid while analyst targets and intrinsic value estimates sit much higher, leaving a wide gap on the table. How far does fair value really sit from today’s price?
Most Popular Narrative: 31% Undervalued
Against the last close at $21.37, the most followed narrative puts Navan’s fair value closer to $30.80. This anchors a sizable valuation gap that rests on specific growth, margin and discount rate assumptions rather than sentiment alone.
Growing reliance on integrated corporate payments and card based spend control in travel programs, combined with Navan’s strengthened post IPO balance sheet and lower cost of capital, should enable higher payments attach rates and better unit economics. This may boost net margins and interchange driven earnings over time. Globalization of business travel and increasing focus on real time visibility, duty of care and policy compliance favor Navan’s international footprint and direct supplier network. These factors can expand hotel and air attach, sustain usage yield near 7% and support ongoing gross margin expansion.
See why 9 investors see Navan as 31% undervalued.
Result: Fair Value of $30.80 (UNDERVALUED)
Still, the bullish Navan story could be knocked off course if business travel weakens for longer, or if larger AI and travel platforms compress pricing power.
Find out about the key risks to this Navan narrative.
Another View on Navan’s valuation
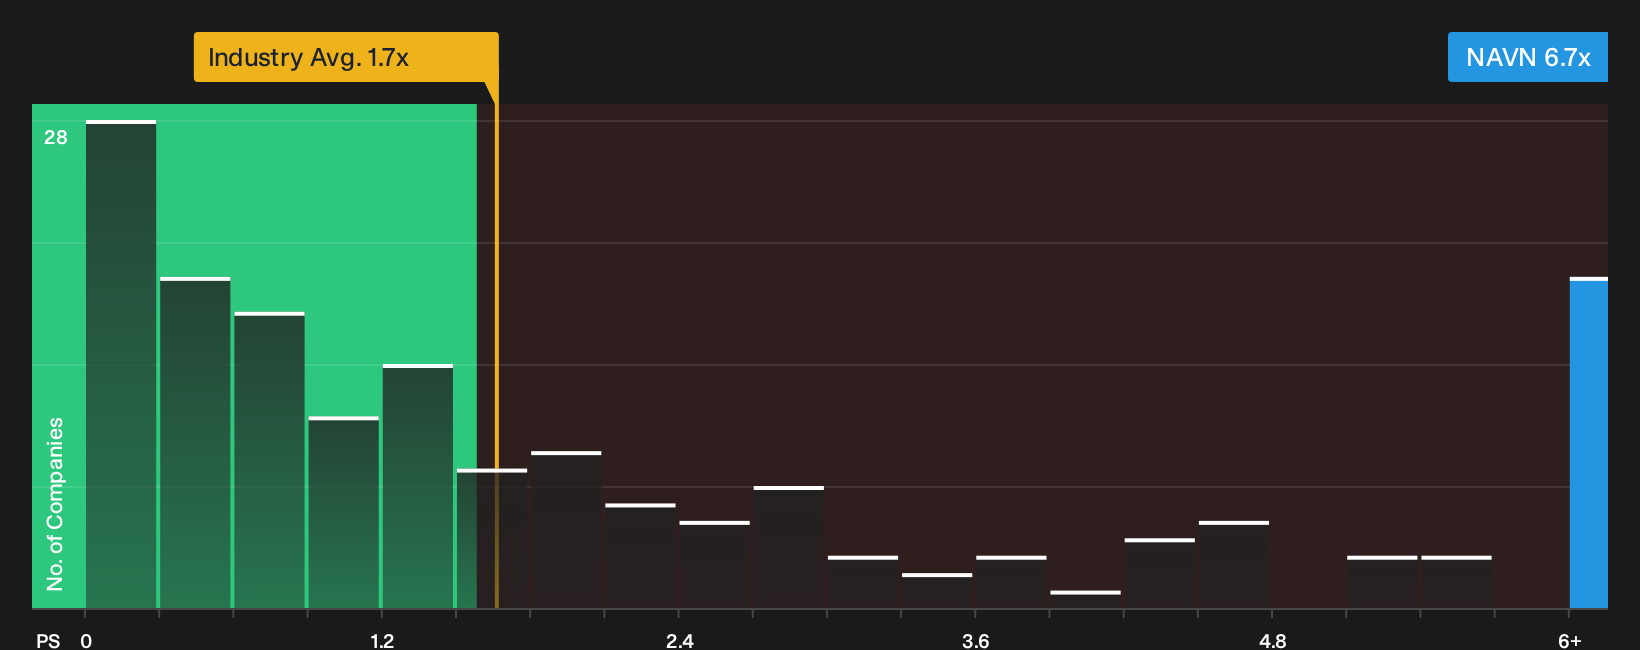
While the narrative and analyst targets frame Navan as about 31% undervalued on future earnings assumptions, the current P/S ratio of 6.7x sends a different message. That multiple sits well above both peers at 3.1x and a fair ratio of 3.2x. This points to meaningful valuation risk if sentiment cools.
To see how this price gap lines up with the underlying numbers, take a closer look at the detailed valuation work in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Navan can create pressure to react quickly, but a better approach is to review the data and decide where you stand. To weigh both sides clearly, take a closer look at 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Navan?
If Navan’s story has your attention, do not stop here. Broaden your watchlist now so you are not late to the next opportunity.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results), which can help anchor a portfolio when volatility picks up.
- Hunt for potential value opportunities by reviewing the 35 high quality undervalued stocks, filtered using cash flows and balance sheet strength rather than headline hype.
- Prioritize stability and income potential by checking out the 6 dividend fortresses, which focuses on higher yielding businesses with robust profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com