


What Chipotle Shares First Seoul Opening Means For Shareholders
- Chipotle Mexican Grill has opened its first restaurant in Asia in Seoul through a joint venture with Sangmidang Holdings, with South Korea serving as a reference market for further regional expansion and additional sites planned in the country and Singapore.
- The appointment of former KFC chief executive Sabir Sami to Chipotle’s Board adds deep global restaurant expertise at the same time the business is building an Asian foothold, aligning boardroom experience with on-the-ground international execution.
- We will look at how Chipotle’s investment narrative is influenced by using South Korea as a reference market for Asian expansion.
Chipotle Mexican Grill Investment Narrative Recap
To own Chipotle Mexican Grill, you need to believe that its core U.S. restaurant engine, digital channels and menu pipeline can keep offsetting consumer softness, higher tariffs on ingredients and heavier competition. The short term swing factor still looks like transaction trends. The Seoul opening and Asia plans help the long term story but do not materially change near term demand risk.
The biggest current threat is margin pressure from tariffs and build out costs at a time when net profit margins are already below last year and earnings growth recently turned negative. Execution on efficiency projects like new equipment and produce slicers matters if Chipotle wants to protect returns on new restaurants globally.
The most relevant development here is Sabir Sami joining the Chipotle Mexican Grill board. His time leading KFC globally and across Asia puts more operational depth around the new Seoul joint venture and any follow on sites in South Korea and Singapore, where brand fit, menu adaptation and local sourcing all need tight control.
For you that links directly back to catalysts already flagged. International expansion is a key growth lever, but it comes with higher capital needs and execution risk, especially when tariffs and construction costs are concerns. A board that blends global restaurant experience with an already experienced director group could help the business balance pace of rollout, unit economics and margin discipline.
Chipotle Mexican Grill's current analyst narrative points to revenues of $16.7b and earnings of $2.1b by 2029, based on 10.4% yearly revenue growth and an earnings increase of about $700m from $1.4b today.
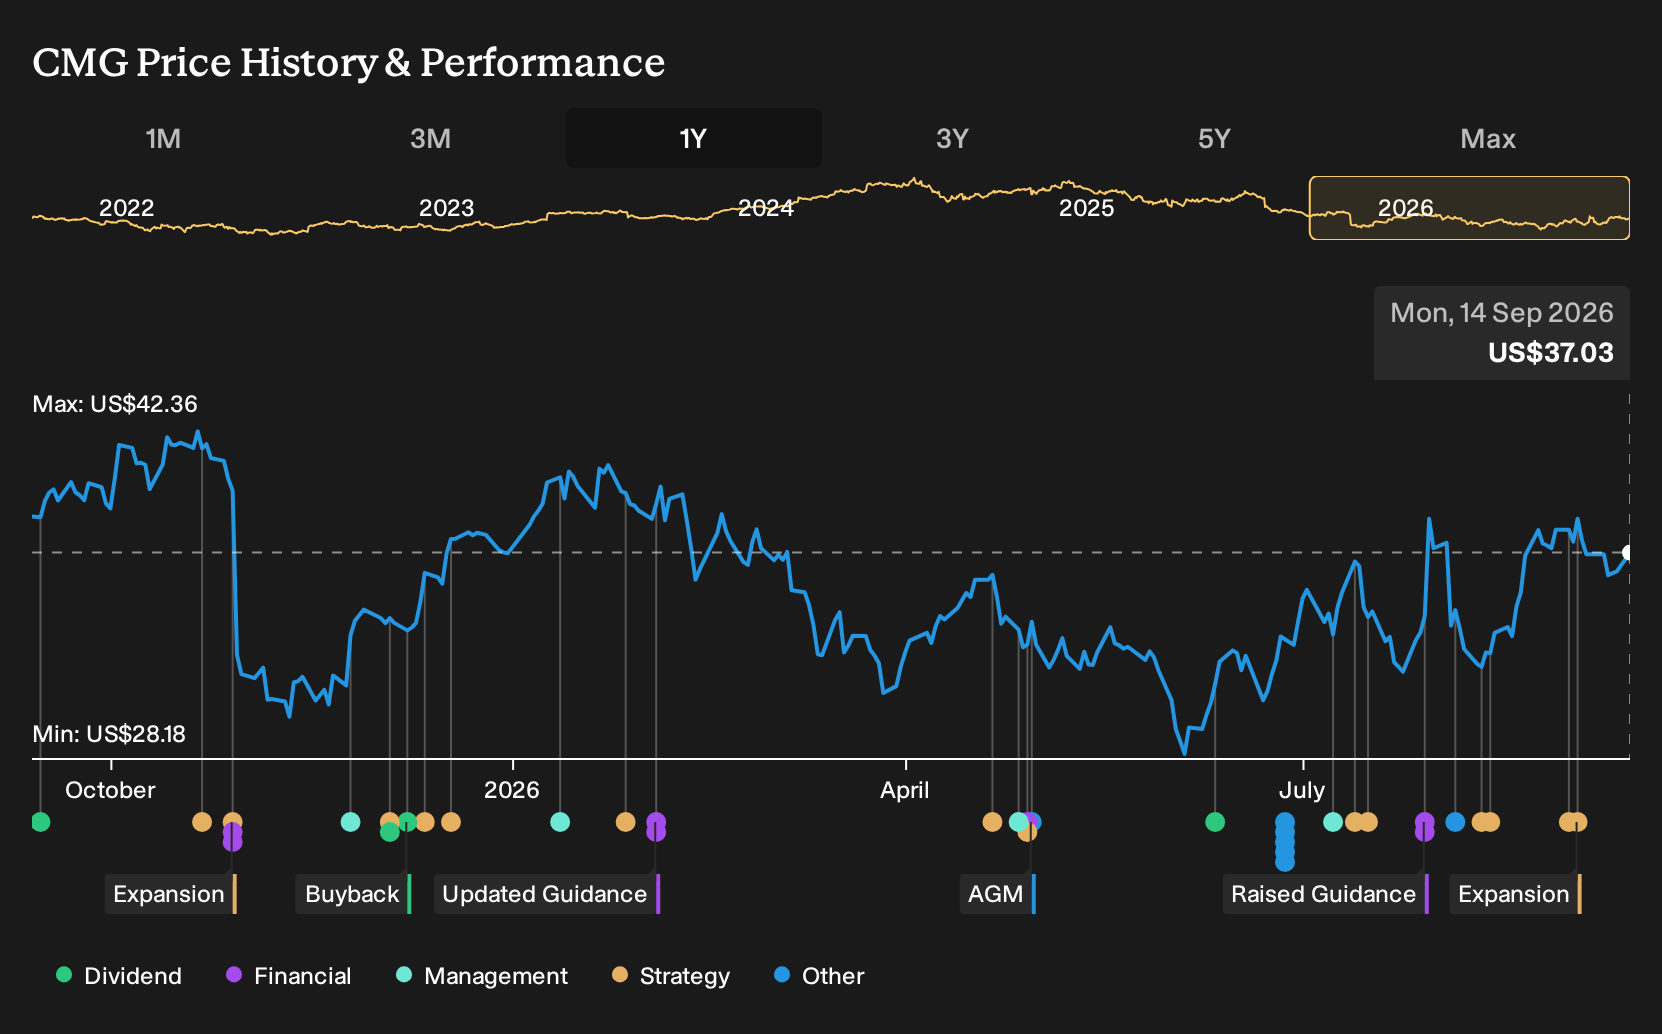
Uncover why Chipotle Mexican Grill's fair value indicates a 19% potential upside to its current price and why this gap could narrow quickly.
Exploring Other Perspectives
One alternate read on Chipotle Mexican Grill focuses less on tariffs and more on the risk that rapid Asia expansion could strain operations. The most cautious analysts were already penciling in revenue of about $16.1b and earnings of $2.0b by 2029. Those views may shift as the Seoul launch and Sabir Sami’s board role play out.
Explore 9 other Chipotle Mexican Grill fair value estimates, including one that suggests as much as 25% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Chipotle Mexican Grill research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Chipotle Mexican Grill. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chipotle Mexican Grill's overall financial health at a glance.
Looking For More Investment Ideas Beyond Chipotle Mexican Grill?
Chipotle Mexican Grill might be the starting point for your work, but your portfolio benefits when you compare it with other businesses that have very different risk and return profiles. The Simply Wall St Screener lets you quickly filter for traits that matter to you, whether that is value, balance sheet strength or income potential.
- If you are hunting for potential value opportunities with stronger fundamentals, scan through 35 high quality undervalued stocks that already clear key quality checks.
- For investors who care most about resilience and capital preservation, focus on 11 resilient stocks with low risk scores that score well on volatility and balance sheet strength.
- If income is a priority, zero in on 6 dividend fortresses that combine higher yields with more durable business models.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com