


Warner Music Group Stock And Music Royalties Under Pressure From AI Streaming Rules
AI generated tracks flooding streaming platforms are now meeting real resistance, as major labels tighten rules to protect royalty pools and crack down on fraud. That shift puts long established music rights holders in a very different position compared with smaller AI driven outfits and high volume distributors. This piece explains how that tension plays out in markets and highlights three stocks that appear especially exposed to this new rulebook.
The three stocks below are just a sample of what this pressure on AI driven music output means for listed rights holders. The full screen surfaces 43 more companies with equally detailed narratives that are not covered here.
If you want to identify and analyze the highest conviction ideas in this corner of the market, head straight to the Global Music Rights Holders and Major Music Labels screener.
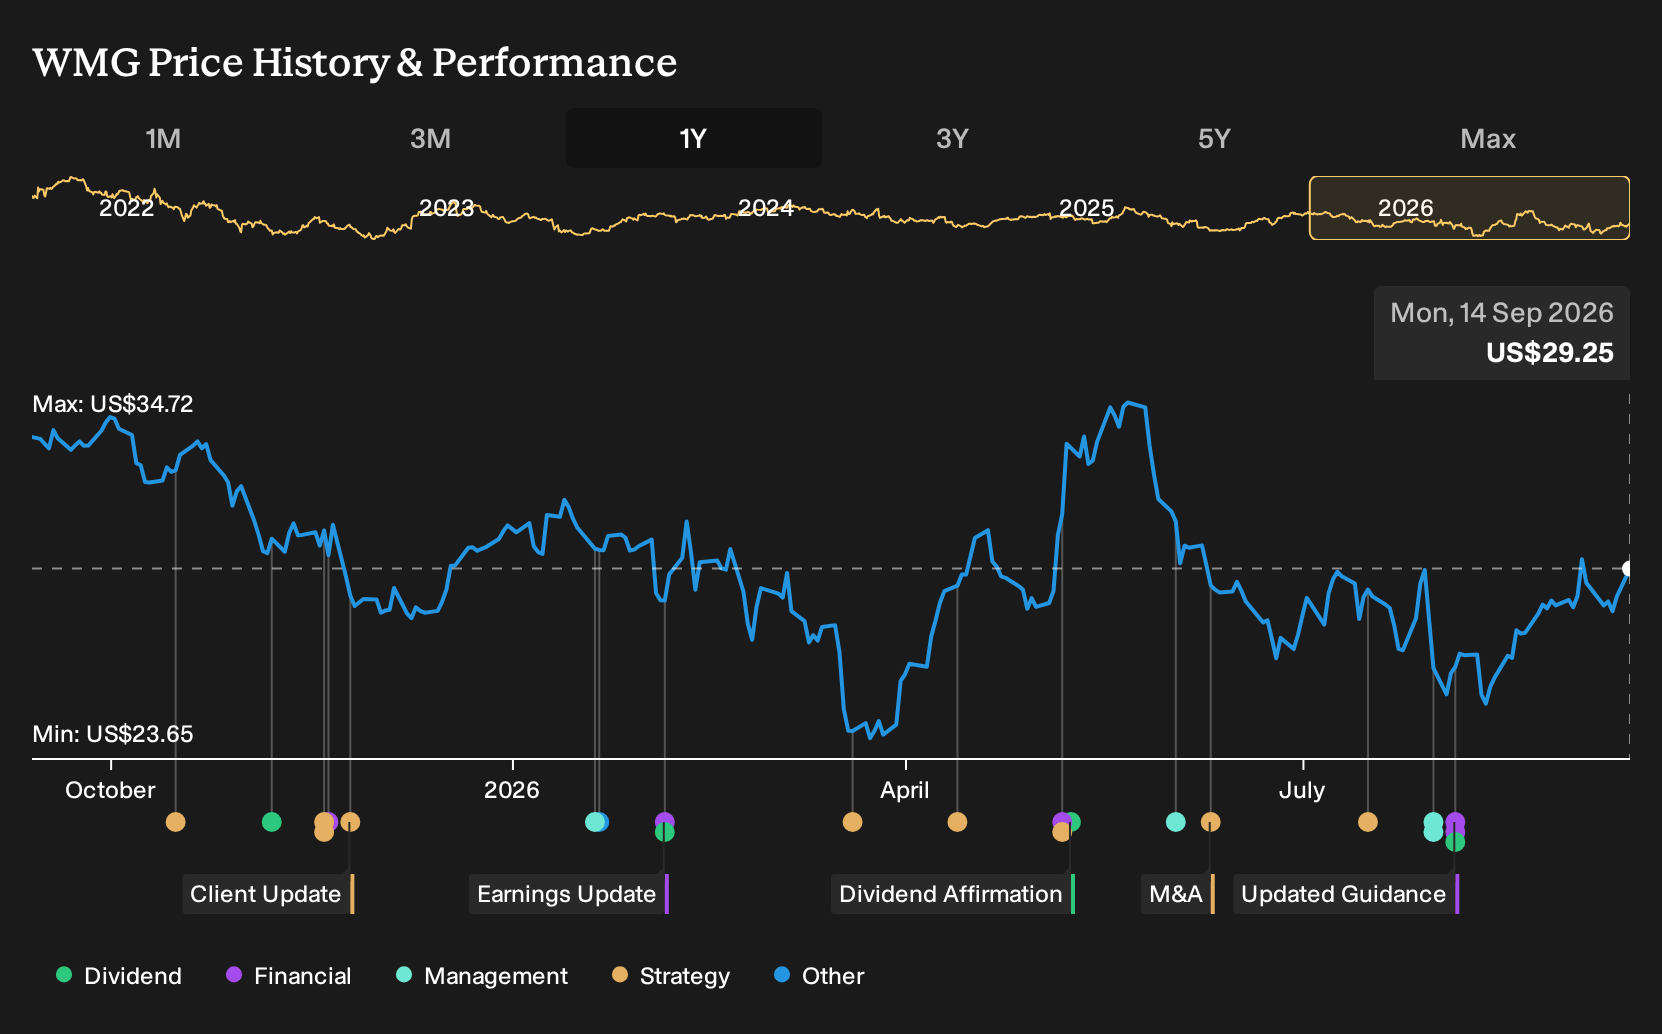
Warner Music Group (WMG)
Warner Music Group is one of the heavyweight music rights owners in this screener, with recorded tracks and publishing royalties deeply tied to how fairly streaming platforms treat human made content. This is why its response to AI and fraud rules really matters.
Warner Music Group runs a global music entertainment operation built around recorded tracks and publishing rights, earning about US$5.9b from Recorded Music and US$1.4b from Music Publishing, and carries a market value of roughly US$14.8b.
"The digital monetization landscape is broadening, with advancements in low-friction micropayments and ongoing efforts to introduce superfan and premium-tier offerings, alongside renewal of streaming contracts at higher rates. These trends are positioning Warner to capture new income streams and improve net revenue per user."
What happens if a single pressure point in those streaming economics shifts at the same time that Warner leans harder into higher value fans?
If that shift in leverage is what you care about, start with the full narrative for Warner Music Group to see how Warner Music Group could be decoupling from pure volume growth.
Universal Music Group (ENXTAM:UMG)
Universal Music Group is the pure-play giant many investors look for in this screener, with a catalogue-heavy royalty engine that ties directly into how tightly streaming platforms protect human-made recordings and how much power independents really take at the edges.
"Independent distribution share increased from approximately 20.64% at midyear 2025 to 23.06% at midyear 2026, having already risen from 19.92% to 22.65% in Q1. Downtown contributed approximately €202 million of Q2 revenue and around €10 million of adjusted EBITDA, roughly a 5% EBITDA margin."
The real swing factor for Universal Music Group is what happens if that quiet shift in where music flows starts to influence pricing power.
Universal Music Group N.V. is a €26.8b pure-play music rights heavyweight, with €9.8b from Recorded Music, €2.3b from Music Publishing, and €774m from Merchandising and Other, making it central to how protected streaming royalties show up in listed markets.
That pricing shift is exactly where full narrative for Universal Music Group digs in, showing how Universal Music Group’s scale could turn streaming pressure into accelerating royalty power.

Saregama India (BSE:532163)
Saregama India is a pure-play way to tap the Global Music Rights Holders theme, because its business is built around owning and monetising a vast Indian music library across streaming, devices and content formats.
Saregama India Limited runs four businesses built on entertainment rights, anchored by music royalties that fit directly into the screener’s focus on catalog owners. The Music unit brings in about ₹7.2b, with Artist Management at roughly ₹1.5b, Video at about ₹897m and Events at around ₹728m, supporting a market value of roughly ₹96.9b.
"Accelerating digital content consumption, driven by rapid internet penetration and smartphone adoption in India, is significantly expanding Saregama's addressable market for music licensing, streaming, and digital video. This is expected to drive recurring revenue growth as the company leverages its diverse regional and language catalogue."
What happens to Saregama India’s earnings power if one quiet shift in how platforms share the streaming royalty pool changes that subscription math?
If that shift in subscription math is what you are really testing, move next to the full narrative for Saregama India to see how Saregama India’s royalty engine could accelerate.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities often move first, and the best setups can be gone once momentum is caught by the crowd. Scan these under the radar lists while it matters and consider acting early.
- Target steady income candidates using the curated 6 dividend fortresses before yield hunters start crowding into the same high payout opportunities.
- Track potential participants in the next leg of the AI wave with hand picked 60 AI infrastructure stocks positioned for rising data demand and hardware build outs.
- Spot resilient balance sheets through a refined list of solid balance sheet and fundamentals (23 results) focused on strong cash positions, low leverage, and consistent fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com