


Undervalued Asian Small Caps With Insider Action For September 2026
In September 2026, Asian markets are navigating a complex landscape characterized by rising oil prices and inflation concerns, driven by geopolitical tensions and economic shifts. As small-cap stocks often offer unique opportunities for growth, particularly in volatile environments, identifying those with strong fundamentals and insider activity can be key to capitalizing on potential market inefficiencies.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
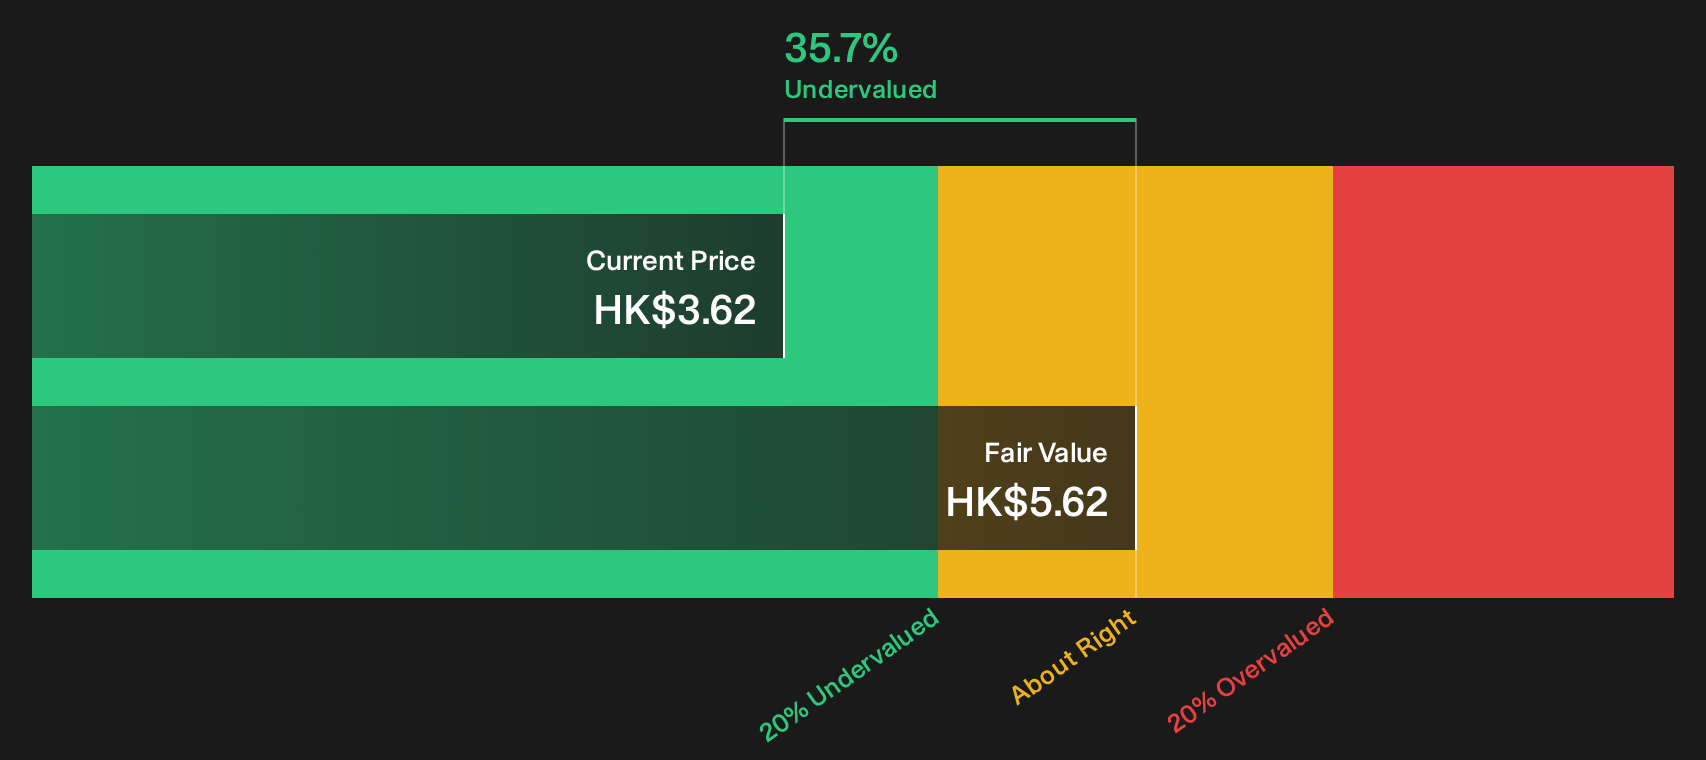
| China Aircraft Leasing Group Holdings | 7.3x | 1.0x | 35.69% | ★★★★★☆ |
| Credit Corp Group | 8.9x | 2.0x | 43.78% | ★★★★★☆ |
| SHAPE Australia | 18.5x | 0.5x | 45.47% | ★★★★☆☆ |
| DMCI Holdings | 6.2x | 0.9x | 41.46% | ★★★★☆☆ |
| Australian Finance Group | 8.1x | 0.3x | 17.73% | ★★★★☆☆ |
| ReadyTech Holdings | NA | 1.4x | 48.25% | ★★★★☆☆ |
| Jumbo Group | 23.6x | 0.8x | 49.50% | ★★★☆☆☆ |
| China Yongda Automobiles Services Holdings | NA | 0.0x | -72.78% | ★★★☆☆☆ |
| Hong Fok | 23.7x | 6.8x | 30.16% | ★★★☆☆☆ |
| Paragon Care | NA | 0.1x | -4.00% | ★★★☆☆☆ |
We're going to check out a few of the best picks from our screener tool.
Lifestyle Communities (ASX:LIC)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Lifestyle Communities focuses on the development and management of residential communities, with a market cap of A$2.16 billion.
Operations: The company generates revenue primarily from property development and management, with the most recent reported figure being A$204.82 million. The net income margin has shown significant fluctuations, reaching a high of 65.72% in June 2021 before experiencing negative margins in subsequent periods. Gross profit margin has varied over time, recently recorded at 14.87% as of June 2026 following a period of negative margins. Operating expenses have consistently impacted profitability, with general and administrative expenses being a notable component within these costs.
PE: 12.3x
Lifestyle Communities, a smaller player in the market, recently reported impressive financial results for the year ending June 30, 2026. Sales increased to A$52.36 million from A$47.73 million, while net income swung to A$46.92 million from a significant loss previously. Insider confidence is evident with Kevin Tucker's purchase of over 4 million shares worth approximately A$20.41 million between July and August 2026, reflecting belief in future growth despite reliance on external borrowing for funding needs.
China Aircraft Leasing Group Holdings (SEHK:1848)
Simply Wall St Value Rating: ★★★★★☆
Overview: China Aircraft Leasing Group Holdings is a company that provides aircraft leasing services, with a market cap of HK$2.89 billion.
Operations: The company generates revenue primarily from aircraft leasing services, with recent figures showing a revenue of HK$2.78 billion. Operating expenses significantly impact net income, as reflected in the net income margin of 13.27% for the latest period. Gross profit margin has been observed at 68.59%, indicating a considerable cost associated with generating revenue.
PE: 7.3x
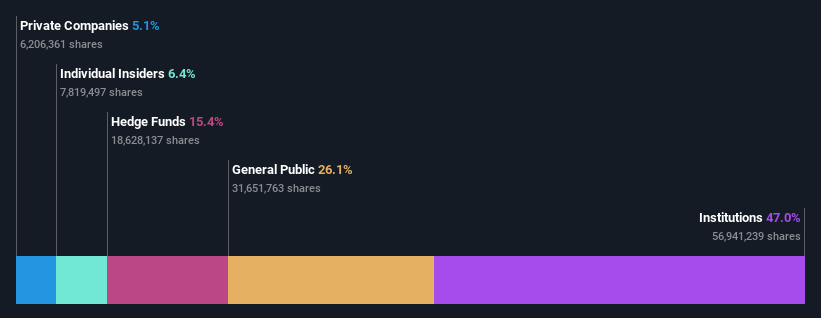
China Aircraft Leasing Group Holdings has seen a significant rise in sales, reaching HK$829.4 million for the half-year ending June 2026, up from HK$136.43 million the previous year. Revenue also climbed to HK$3.91 billion from HK$2.47 billion, with net income at HK$171.37 million compared to last year's HK$140.53 million, reflecting strong operational performance despite reliance on external borrowing for funding needs. Insider confidence is evident as insiders recently purchased shares, indicating potential growth optimism amidst an increasing dividend of HKD 0.14 per share announced in August 2026.
UltraGreen.ai (SGX:ULG)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: UltraGreen.ai focuses on developing sustainable AI solutions across global markets, with a market cap of $1.25 billion.
Operations: The company's revenue model is driven by its DxG segments in the Americas and Rest of World, totaling $211.73 million after adjustments. The gross profit margin shows an upward trend, reaching 85.88% by mid-2026. Operating expenses have increased over time, with significant contributions from general and administrative costs.
PE: 9.9x
UltraGreen.ai's recent insider confidence is evident as Founder Ravinder Sajwan purchased 961,538 shares, reflecting a significant 116% increase in their holdings. Despite the company's volatile share price over the past three months and reliance on higher-risk external borrowing, its earnings are projected to grow at nearly 12% annually. With first-half sales rising to US$87 million from US$67 million last year and net income jumping to US$39 million, UltraGreen.ai anticipates full-year revenues between US$175-185 million.
- Navigate through the intricacies of UltraGreen.ai with our comprehensive valuation report here.
Understand UltraGreen.ai's track record by examining our Past report.

Make It Happen
- Investigate our full lineup of 55 Undervalued Asian Small Caps With Insider Buying right here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Discover a world of investment opportunities with Simply Wall St's free app and access unparalleled stock analysis across all markets.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com