


MP Materials (MP) Stock Looks Above Fair Value On Its 142% Run
MP Materials has seen its share price move sharply in recent years, which puts a spotlight on whether the current US$50.51 quote is adequately grounded in the sales the business is generating. With rare earths policy and geopolitics in the headlines again, an open question is how much of MP Materials' valuation is tied to its actual revenue base rather than shifting sentiment.
- Over the past 3 years, MP Materials has delivered a share price gain of 142.5%, which raises the stakes on whether the current valuation can still be reconciled with its sales.
- Federal support for critical minerals projects and MP Materials' role as a beneficiary can shape expectations for future rare earths demand, which may support higher planned investment and influence how investors think about the level of sales needed to back today's stock price.
- The analysts covering MP Materials have run their own numbers. See what analysts think MP Materials's shares could be worth.
The issue now is whether MP Materials' current share price is justified by the sales it is generating when judged against the Fair Ratio benchmark for this lens.
To see how MP Materials compares with other rare earth and critical minerals plays, line it up next to the 27 best rare earth metal stocks.
Does MP Materials Look Pricey on Sales?
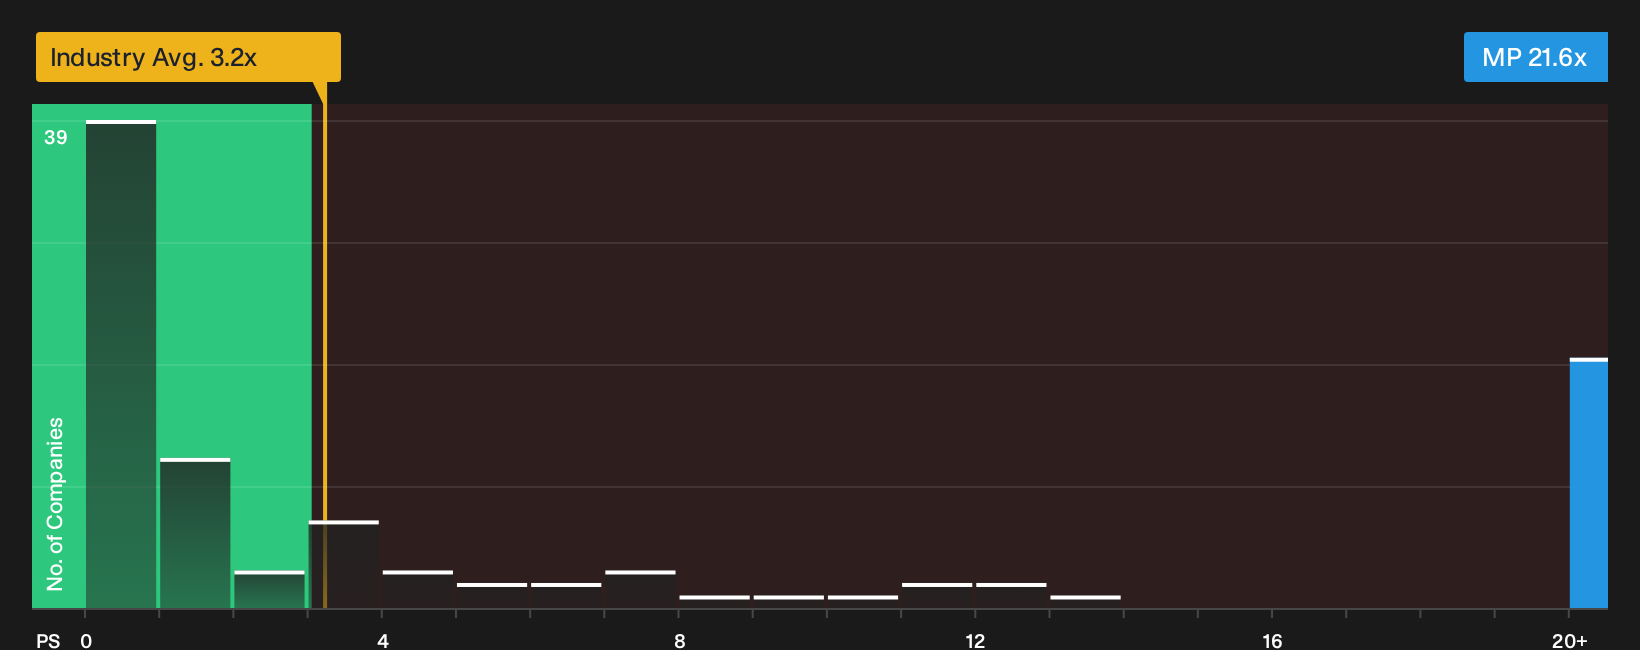
P/S fits MP Materials because revenue is still the cleanest anchor while earnings and free cash flow remain volatile. On this yardstick, the stock trades on a P/S of 21.6x, which is far above the broader Metals and Mining industry average of 3.2x and well ahead of the 3.6x peer group level given here for rare earth and critical minerals players.
The Fair Ratio model, which adjusts the target multiple for MP Materials' growth profile, margins, scale and risk, flags the current 21.6x as overvalued and shows the figure well above what would usually be expected. Because the model is heavily penalising recent losses and cash burn, that gap is better read as a warning that the shares screen very expensive on this framework rather than a precise fair-value estimate. Despite federal backing and sector attention supporting sentiment, the valuation still assumes a lot of future revenue delivery already. Explore the numbers behind MP Materials's P/S valuation.
The MP Materials Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for MP Materials pick up where the valuation puzzle leaves off and explain what path for growth, profitability and earnings would need to occur for the stock to be worth materially more or less than it is today on the market. Rather than presenting a single output from a model or ratio, they describe the future that figure relies on so you can watch how closely MP Materials' actual progress tracks those assumptions on the Community page.
One of the top community narratives on MP Materials: 33% undervalued
"Government-backed contracts and partnerships with major tech firms secure stable revenue and improve long-term earnings visibility, insulating against market fluctuations..."
Discover why this Narrative puts MP Materials at 33% undervalued.
MP Materials' share price is only one side of the story
Market ratios show what investors pay today, but analyst projections for MP Materials a few years out offer a different lens on what the business might be earning and how that compares. Explore where analysts expect MP Materials to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com