


Hirose ElectricLtd (TSE:6806) Pullback Raises A Fresh Question On Valuation
Recent price pressure in Hirose ElectricLtd (TSE:6806), with the stock down over the past week, month and past 3 months, has pushed the shares to a last close of ¥23,980.
For context, Hirose ElectricLtd shares have retreated in the short term, with the 30-day share price return down 12.19% and the 90-day move down 14.98%, yet the year-to-date share price return remains positive at 35.90% and the 1-year total shareholder return is 28.26%. This points to fading near-term momentum after a stronger run earlier in the year.
Scan beyond Hirose ElectricLtd's recent pullback and compare it with a hand-picked list of solid balance sheet and fundamentals (19 results) that may offer similar resilience with different price paths.
The pullback in Hirose ElectricLtd after a strong year-to-date run presents a clear decision point for investors. Is this a reasonable entry now, or does the valuation still argue for patience?
Price-to-Earnings of 23.6x: Is it justified?
On simple numbers, Hirose ElectricLtd trades on a P/E of 23.6x, which already bakes in a fair amount of earnings power at the current ¥23,980 share price.
The P/E ratio links what you pay today to the profits the business is generating. For a connector manufacturer with global exposure across consumer, automotive and industrial machinery applications, that earnings anchor matters because profit cycles can be tied to broader electronics demand.
Investors looking at Hirose ElectricLtd see a mixed signal. The stock is described as good value against a peer average P/E of 39.8x, yet it is also labelled expensive versus an estimated fair P/E of 19.6x and the wider JP Electronic industry average of 15.5x. That suggests the market is assigning a premium that could compress if sentiment cools or could prove resilient if forecast earnings growth of 12.7% per year and revenue growth of 8.1% per year occur as expected.
Compared with the sector, the 23.6x P/E is significantly richer than the industry’s 15.5x level. This implies investors are currently willing to pay more for Hirose ElectricLtd’s earnings stream than for the typical JP Electronic stock. Against the estimated fair P/E of 19.6x, the multiple also screens as stretched, which hints at a valuation level that could move closer to that fair ratio if expectations reset.
Explore the SWS fair ratio for Hirose ElectricLtd.
Result: Price-to-Earnings of 23.6x (OVERVALUED)
Still, Hirose ElectricLtd’s premium P/E and exposure to swings in electronics demand could quickly work against you if end markets soften or if sentiment reverses.
Find out about the key risks to this Hirose ElectricLtd narrative.
Another View on Hirose ElectricLtd: Cash Flows Tell a Different Story
The P/E workup presents Hirose ElectricLtd as expensive, yet the SWS DCF model indicates something different. At ¥23,980, the stock trades about 16.6% below an estimated future cash flow value of roughly ¥28,757. That suggests investors are not fully paying for the projected cash generation.
For anyone weighing these two signals, the question is straightforward: Does the earnings multiple still matter more to you than what the cash flow math is implying?
Look into how the SWS DCF model arrives at its fair value.
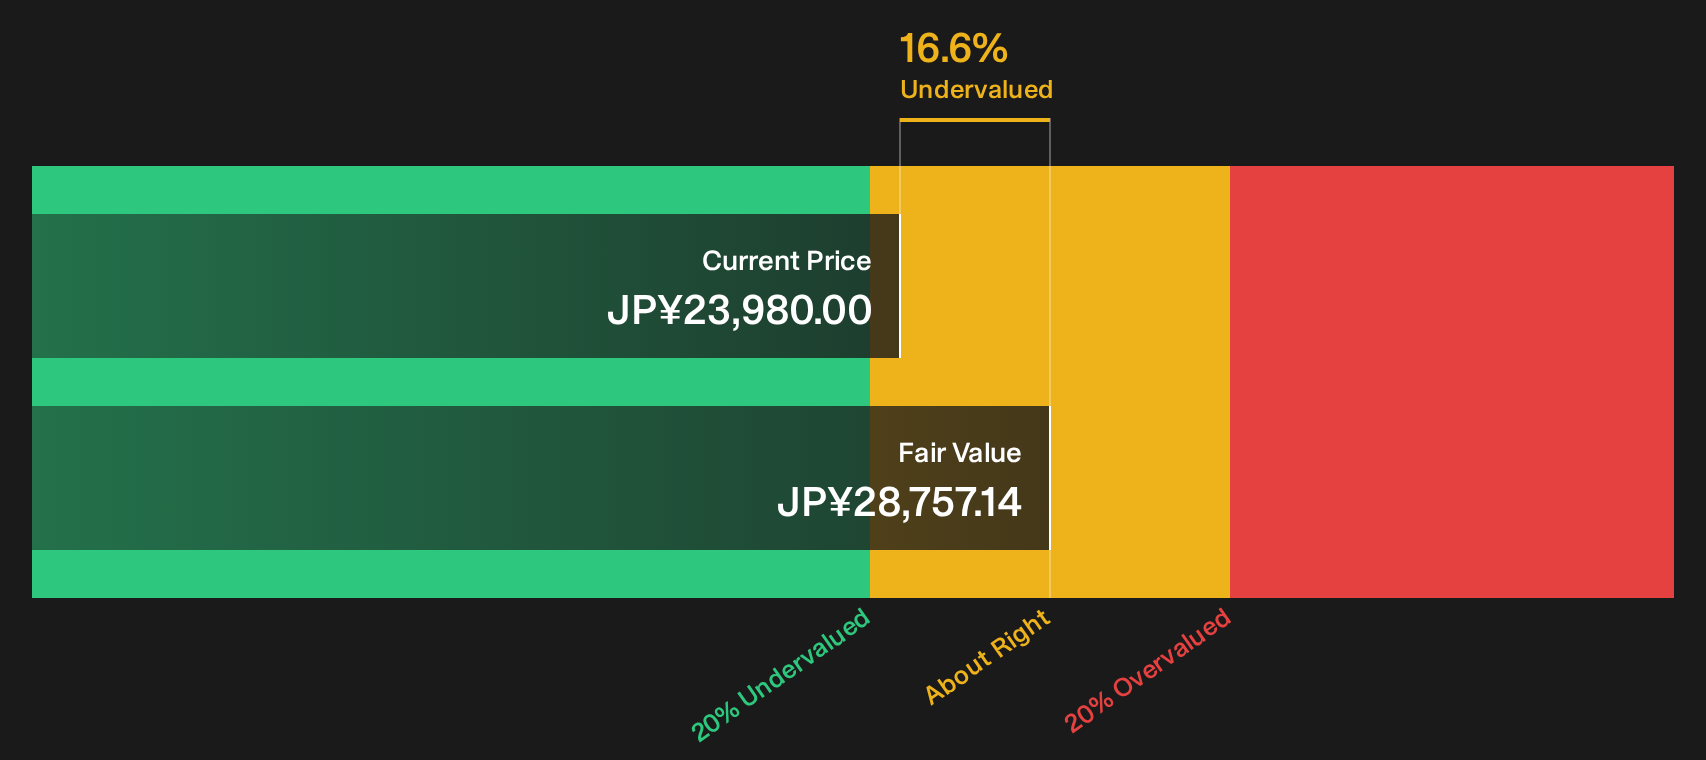
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hirose ElectricLtd for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hirose ElectricLtd so far. If you want to move quickly and judge the balance of risk and upside for yourself, start with the 4 key rewards and 1 important warning sign.
Looking for more ideas beyond Hirose ElectricLtd?
If Hirose ElectricLtd feels finely balanced on risk and reward, do not stop here. Use the screener to spot other opportunities before the crowd does.
- Target quality at a reasonable price by scanning for companies that combine strong fundamentals with appealing valuations through the 17 high quality undervalued stocks.
- Secure more predictable income streams by checking out the 18 dividend fortresses that focuses on higher yielding payouts with resilient profiles.
- Dial back portfolio downside risk by filtering for sturdier businesses using the 12 resilient stocks with low risk scores that focuses on more resilient balance sheets and earnings profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com