


Top Growth Companies With Strong Insider Ownership September 2026
In the last week, the United States market has been flat, yet over the past 12 months it has experienced a 14% rise with earnings forecasted to grow by 17% annually. In this environment, identifying growth companies with strong insider ownership can be a key strategy for investors looking to align with management interests and potentially capitalize on future growth opportunities.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Uxin (UXIN) | 34.3% | 69.4% |
| Upstart Holdings (UPST) | 14.2% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 61.3% |
| Precigen (PGEN) | 11.7% | 55.4% |
| Nu Holdings (NU) | 22.8% | 21.8% |
| Karman Holdings (KRMN) | 14.4% | 54% |
| Himax Technologies (HIMX) | 29.2% | 70.2% |
| Dave (DAVE) | 16.9% | 23.2% |
| Carlyle Group (CG) | 27.4% | 20.5% |
| Almonty Industries (ALM) | 10.8% | 38% |
Here we highlight a subset of our preferred stocks from the screener.
Esquire Financial Holdings (ESQ)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Esquire Financial Holdings, Inc. is the bank holding company for Esquire Bank, National Association, offering commercial banking products and services to legal and small businesses as well as commercial and retail customers in the United States, with a market cap of $1.41 billion.
Operations: Esquire Financial Holdings generates revenue primarily through its community banking segment, which amounted to $149.31 million.
Insider Ownership: 11.5%
Return On Equity Forecast: N/A (2029 estimate)
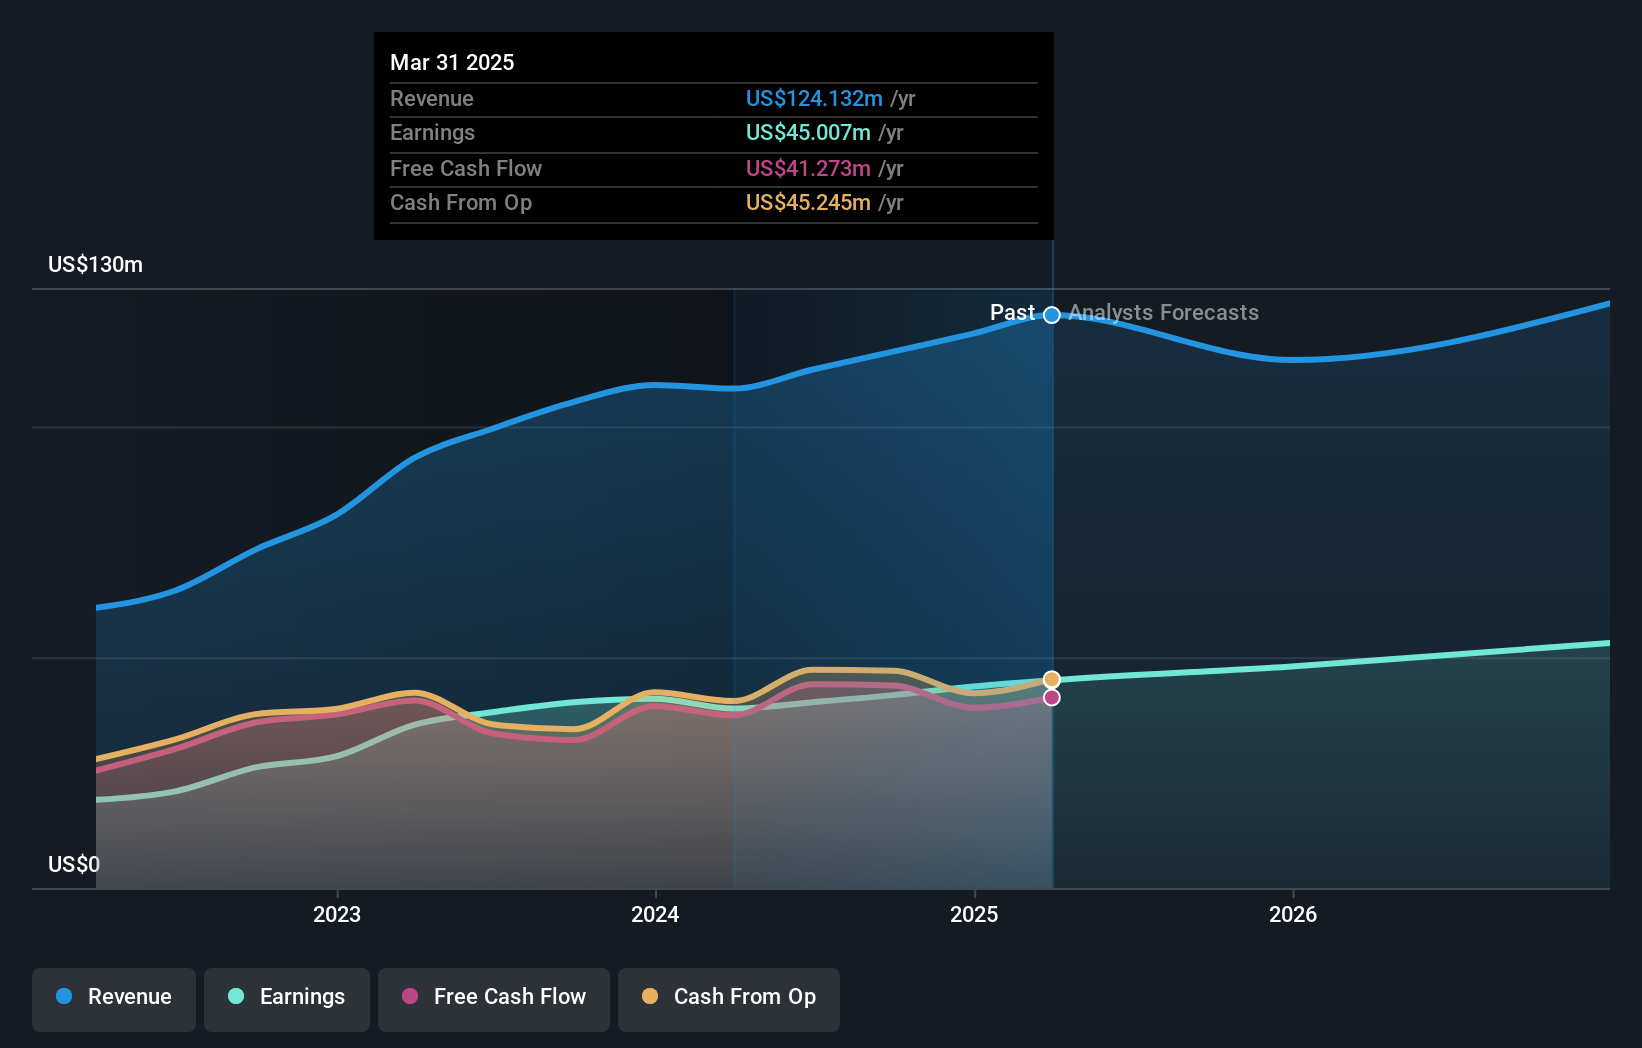
Esquire Financial Holdings demonstrates strong growth potential with earnings forecasted to grow significantly faster than the US market. The company recently completed a merger with Signature Bancorporation, which may bolster its strategic position. Despite past shareholder dilution, insider ownership remains high without substantial recent insider buying or selling activity. Recent financial results show increased net income and interest income, supporting its growth trajectory. Esquire's revenue is expected to outpace the broader market considerably.
- Dive into the specifics of Esquire Financial Holdings here with our thorough growth forecast report.
- The valuation report we've compiled suggests that Esquire Financial Holdings' current price could be inflated.
Mission Produce (AVO)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Mission Produce, Inc. is involved in the sourcing, farming, packaging, marketing, and distribution of avocados, mangoes, and blueberries to food retailers, wholesalers, and foodservice customers both in the United States and internationally with a market cap of approximately $1.14 billion.
Operations: The company's revenue segments include $93.70 million from blueberries, $123.70 million from international farming, and $1.20 billion from marketing and distribution.
Insider Ownership: 24.2%
Return On Equity Forecast: N/A (2029 estimate)
Mission Produce is experiencing significant insider buying, indicating confidence in its future prospects. Despite recent financial challenges, including a net loss of US$6.5 million in Q3 2026, the company forecasts robust earnings growth of 196.5% annually, outpacing the broader market. Revenue is expected to grow at 13.8% per year, slightly above market averages. The recent share buyback reflects management's commitment to shareholder value despite past dilution and current debt concerns not fully covered by operating cash flow.
- Unlock comprehensive insights into our analysis of Mission Produce stock in this growth report.
- Our valuation report here indicates Mission Produce may be overvalued.

ERock (EROC)
Simply Wall St Growth Rating: ★★★★★★
Overview: ERock, Inc. specializes in designing, deploying, selling, operating, and maintaining distributed power generation systems for commercial and industrial customers in the United States with a market cap of $3.47 billion.
Operations: The company's revenue segment includes Electric Equipment, which generated $162.19 million.
Insider Ownership: 26.3%
Return On Equity Forecast: 73% (2029 estimate)
ERock, Inc. demonstrates strong growth potential with forecasted revenue growth of 44.4% annually, significantly outpacing the US market average. Despite a recent net loss of US$55.82 million in Q2 2026 and volatile share prices, analysts anticipate a 77.2% price increase, suggesting undervaluation at current trading levels. The company aims for profitability within three years, supported by high insider ownership and strategic board appointments post-IPO restructuring in June 2026.
- Click to explore a detailed breakdown of our findings in ERock's earnings growth report.
- Insights from our recent valuation report point to the potential undervaluation of ERock shares in the market.

Turning Ideas Into Actions
- Discover the full array of 177 Fast Growing US Companies With High Insider Ownership right here.
- Contemplating Other Strategies? We've found 7 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com