


3 US Bank Stocks That Could Look Different If Rate Hike Talk Returns
Rate hike talk is back on the table, and that shifts the ground under big bank stocks in a way that can matter for your portfolio. When borrowing costs move, money flows differently through lenders, markets, and balance sheets, which can create pockets of opportunity and pockets of risk. This article walks through three US large cap bank stocks exposed to this Fed story. It explains how the same headline can mean very different things for each one.
The stocks covered below are a sample. The full screen surfaced 27 more large cap US bank and financial names with equally interesting stories that are not unpacked in this article.
If you want to go straight to the broader opportunity set, use the US Large-Cap Bank Stocks screener to identify, analyze, and focus on the higher conviction ideas that best match your risk and return preferences.
Nicolet Bankshares (NIC)
Overview: Nicolet Bankshares is a regional bank holding company offering traditional lending, deposit, and wealth services to customers across Wisconsin, Michigan, and Minnesota.
Operations: Nicolet Bankshares generates about US$510 million in revenue from consumer and commercial banking services, all earned within the United States.
Market Cap: US$3.6b
Nicolet Bankshares is closely linked to the US interest rate environment, with traditional loans and deposits that directly reflect each Federal Reserve move on borrowing costs and the yield curve. Recent results show higher net interest income and solid profitability. However, investors still need to watch what happens when one less-visible pressure on its margins and earnings quality shifts.
As that pressure point shifts, review the 3 key rewards and 2 important warning signs (1 is major!) to see where Nicolet Bankshares’ margin story could be quietly improving or stalling.

Columbia Financial (CLBK)
Overview: Columbia Financial is a New Jersey based bank holding company offering deposits, loans, and financial services to households and businesses.
Operations: Columbia Financial generates US$267 million in revenue from financial services entirely within the United States, reflecting a traditional interest driven banking model.
Market Cap: US$3.1b
Columbia Financial fits this US large cap bank screen as a classic balance sheet lender. Its earnings are closely tied to interest rate moves. Earnings growth has been very strong, revenue is projected to advance faster than the wider US market, and net interest income is already higher. This puts more focus on what happens when one unresolved pressure on valuation and governance finally shifts.
That unresolved pressure is exactly what shows up in the 3 key rewards and 1 important warning sign, where valuation and governance could be quietly decoupling from headline earnings strength.
Futu Holdings (FUTU)
Overview: Futu Holdings runs the Futubull and Moomoo platforms that let investors trade securities, use margin, and access digital wealth products globally.
Operations: Futu Holdings generates about HK$24.1b in revenue from online brokerage and margin financing services, primarily through its digital platforms.
Market Cap: US$15.8b
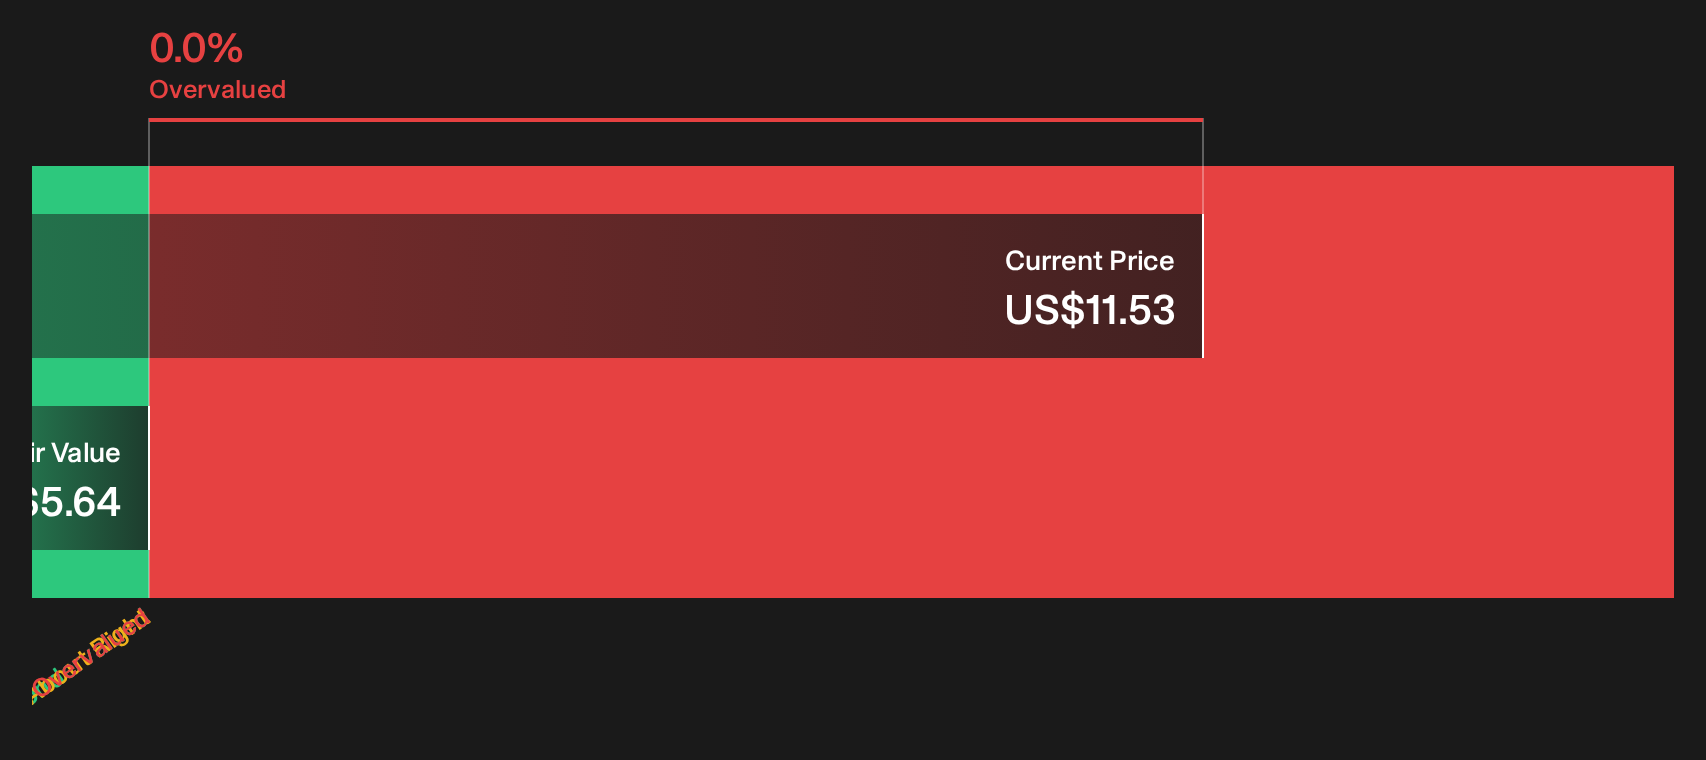
Futu Holdings adds a digital brokerage twist to this large cap bank themed screen, with earnings linked to both trading activity and how client cash and margin balances react when rate expectations change.
"The rapid growth in funded accounts, especially from international markets such as Singapore, the U.S., Malaysia, and Japan, signals ongoing global expansion and diversification of Futu's user base. This positions the company to capture rising middle-class wealth and digital financial adoption in Asia, supporting long-term revenue and AUM growth."
What really matters next is how regulatory and funding pressures shape the balance between that growth and future profitability.
Those cross currents are exactly what the full narrative for Futu Holdings unpacks, explaining how Futu Holdings’ expansion, regulation, and funding pressures could be quietly reshaping the risk reward profile.

Seeking Fresh Alternatives Before They Fly
Markets move fast, and the best breakout stories rarely stay under the radar for long. Scan fresh momentum, spot quietly dropping risks, and position before the crowd while it matters. Act now.
- Target steadier cash flows and capital strength by filtering for companies on the list of solid balance sheet and fundamentals (23 results) that keep funding flexibility front and center.
- Chase early-stage upside with disciplined filters that spotlight the 21 elite penny stocks with strong financials already showing stronger quality and cleaner financials than the typical microcap.
- Ride structural demand for secure energy by tracking infrastructure players inside the 91 nuclear energy infrastructure stocks before that theme attracts broader momentum money.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com