


Should Broadband Software Push Require Action From Harmonic (HLIT) Investors?
- Harmonic recently introduced its cOS SensAI intelligence fabric and a suite of broadband access upgrades, including DOCSIS 4.0 demos and high-density fiber hardware, showcased at Connected Britain and SCTE TechExpo 2026.
- The focus on vendor agnostic data unification and automated operations speaks directly to broadband operators’ cost pressure, skill gaps and need for clearer network visibility.
- We will now assess how Harmonic's new cOS SensAI intelligence fabric could influence the broader investment narrative around its broadband transition.
Harmonic Investment Narrative Recap
To own Harmonic, you need to believe that broadband operators keep investing in virtualized access, fiber and DOCSIS upgrades, and that Harmonic’s software centric model translates into steadier recurring revenue over time. The near term watchpoint is execution on this broadband transition while margins sit at 5.9%, well below the 18.1% level reported last year.
The biggest short term catalyst is turning the broadband portfolio and Video SaaS pipeline into sustained earnings growth, given forecasts for 32.6% annual profit expansion. The key risk remains customer concentration and potential capex delays, which could matter more than any single product announcement if ordering patterns soften.
The launch of cOS SensAI is the clearest operational link to that catalyst. Harmonic is pitching a vendor agnostic intelligence layer that unifies network data and helps operators cut truck rolls, lower repeat tickets and manage multi vendor access more cleanly. That aligns directly with operator cost pressure and skill gaps described in recent commentary.
If SensAI wins adoption, it could deepen Harmonic’s role inside customer networks and support the shift toward higher margin software subscriptions. Execution risk remains, especially with fast moving standards and open source competition, and SensAI will need to prove it can replace fragmented tools at scale before it meaningfully changes the broader risk profile.
What The Current Harmonic Forecasts Assume
Harmonic's narrative projects US$609.8 million in revenue and US$92.1 million in earnings by 2029. That profile is built on analysts looking for 15.3% yearly revenue growth and an earnings increase of about US$83.6 million from US$8.5 million today.
Explore why Harmonic's fair value suggests a 27% potential upside to its current price, which could narrow quickly.
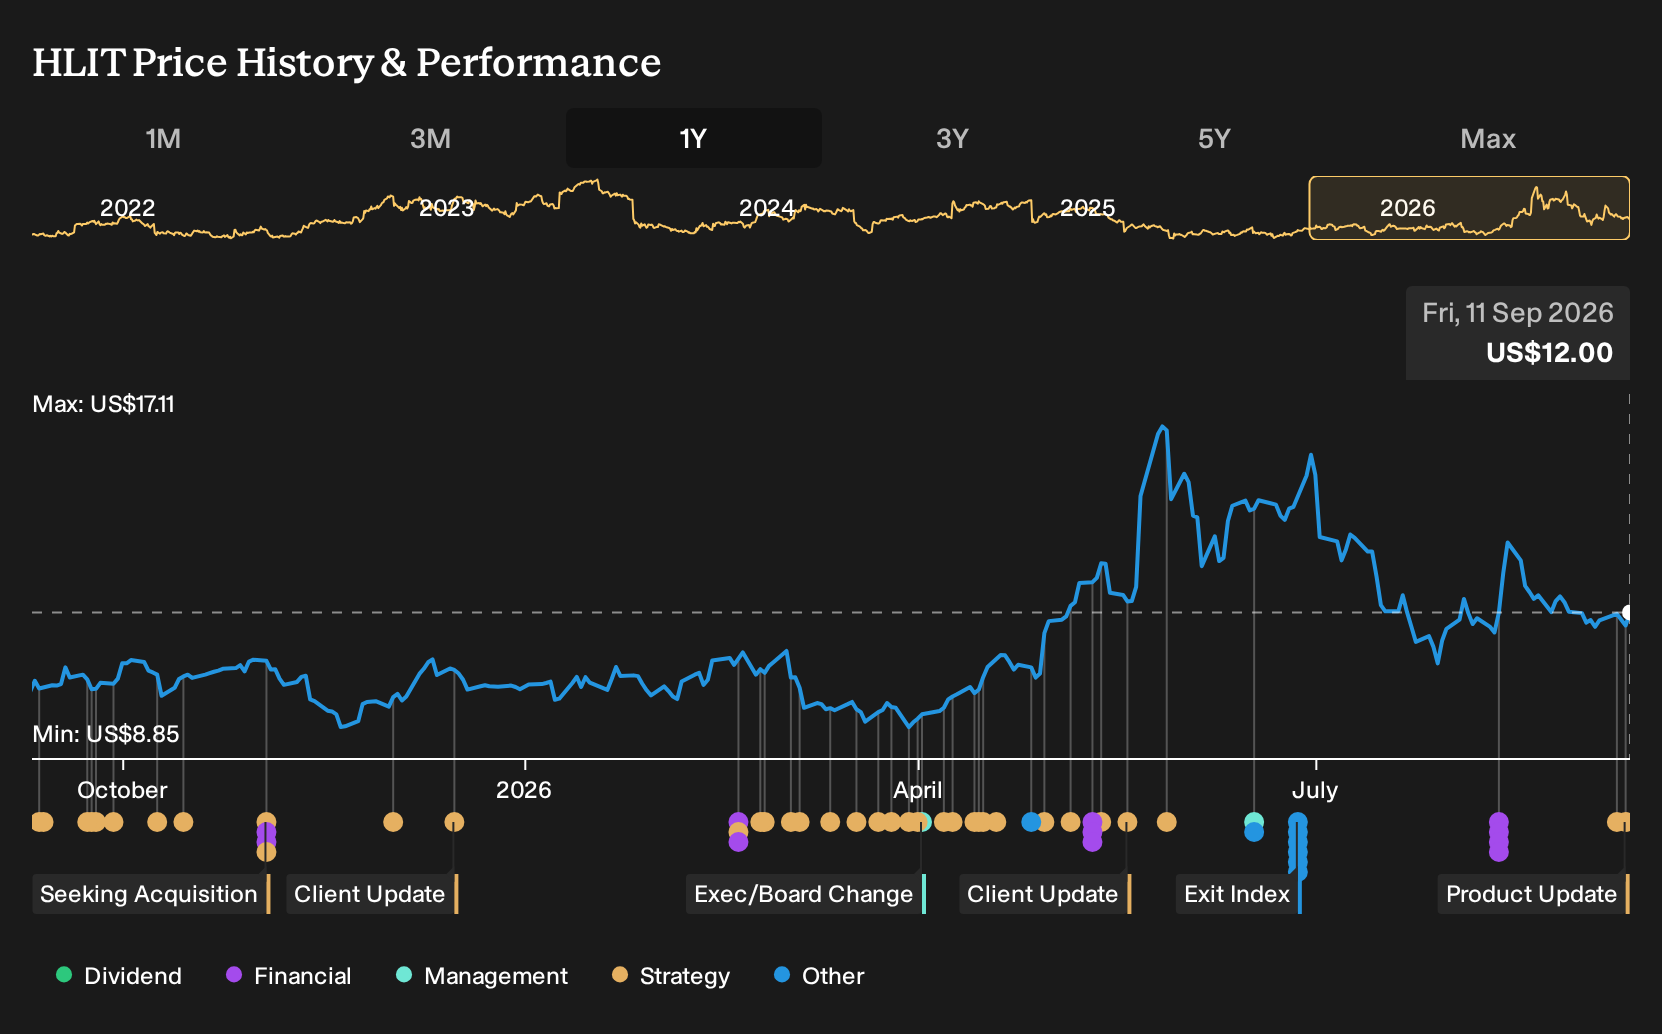
Exploring Other Perspectives
One alternate angle on Harmonic focuses on regulatory tailwinds as the real swing factor for you. The most optimistic analysts were already modeling about US$580.4 million of revenue and US$68.9 million of earnings in 2029, before this SensAI news. That group clearly expects policy driven buildouts to reshape these forecasts, which could shift again as you review fresh data.
Explore 3 other Harmonic fair value estimates, including one that suggests there could be as much as 67% upside potential from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Harmonic research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Harmonic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harmonic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Harmonic?
If Harmonic has sharpened your thinking around broadband, AI and subscription led models, it can help to line that up against a wider watchlist. The Simply Wall St Screener can surface other stocks with different risk profiles so you are not relying on a single story.
- For investors who want potential mispricing with quality fundamentals, scan a curated set of 32 high quality undervalued stocks that may warrant a closer look alongside Harmonic in your portfolio research.
- If capital preservation and calmer price swings matter more to you than aggressive upside, narrow your search to 11 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- When you are hunting for tomorrow's potential standouts rather than widely followed blue chips, consider building a watchlist from 15 high quality undiscovered gems that still fly under most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com