


Leadership Reshuffle Might Change The Case For Investing In Zimmer Biomet (ZBH)
- Zimmer Biomet Holdings reshaped its senior ranks in September 2026, promoting Gary Campbell, Brian Hatcher and Bradley Kessler while Group President Kevin Thornal departed as part of a wider Americas and robotics focused restructuring.
- The shift places long serving insiders over core orthopedics and high tech robotics and data units, which may influence resource allocation, execution priorities and how Zimmer Biomet balances mature implant lines with newer technology platforms.
- We will now explore how Zimmer Biomet's investment narrative could be affected by promoting internal leaders to head key Americas businesses.
Scan how Zimmer Biomet Holdings’ leadership reshuffle compares with other medtech operators stepping up automation by reviewing our hand picked list of 38 robotics and automation stocks.
Zimmer Biomet Holdings Investment Narrative Recap
Zimmer Biomet Holdings appeals to shareholders who buy into a straightforward idea. The business needs to keep hips, knees and broader orthopedics steady while scaling robotics, data platforms and acquired assets like Paragon 28 and Monogram. The biggest near term catalyst remains clean execution on these higher tech offerings without losing share in core reconstructive products.
The key risk still sits in execution and pricing. Industry wide pressure on selling prices, heavy use of debt funding and tighter reimbursement can weigh on margins if integration of acquisitions or US commercial efforts misfire. The new leadership structure looks important but not transformative on its own.
The appointment of Bradley Kessler as President, Americas Robotics, Technology and Data ties directly into Zimmer Biomet Holdings existing push into ROSA, ZBEdge and the Monogram platform. You want that unit tightly focused on surgeon adoption, uptime and integration across hospitals and ambulatory surgery centers, because those are the levers that tend to influence robotics revenue quality.
This move also comes as rivals like Stryker promote their own autonomous robotic capabilities. Strong leadership over Zimmer Biomet Holdings robotics and data business can help execution around regulatory timelines, product rollouts and service quality. It may not remove competitive or reimbursement risk, but it can shape how effectively the company converts its R&D and acquisitions into usable tools for surgeons.
Zimmer Biomet Holdings' narrative projects US$9.4b revenue and US$1.3b earnings by 2029. That profile assumes revenue rising at about 3.4% per year and an earnings increase of roughly US$493m from US$806.7m today.
Discover how Zimmer Biomet Holdings' fair value indicates a 15% potential upside to its current price that may not last much longer.
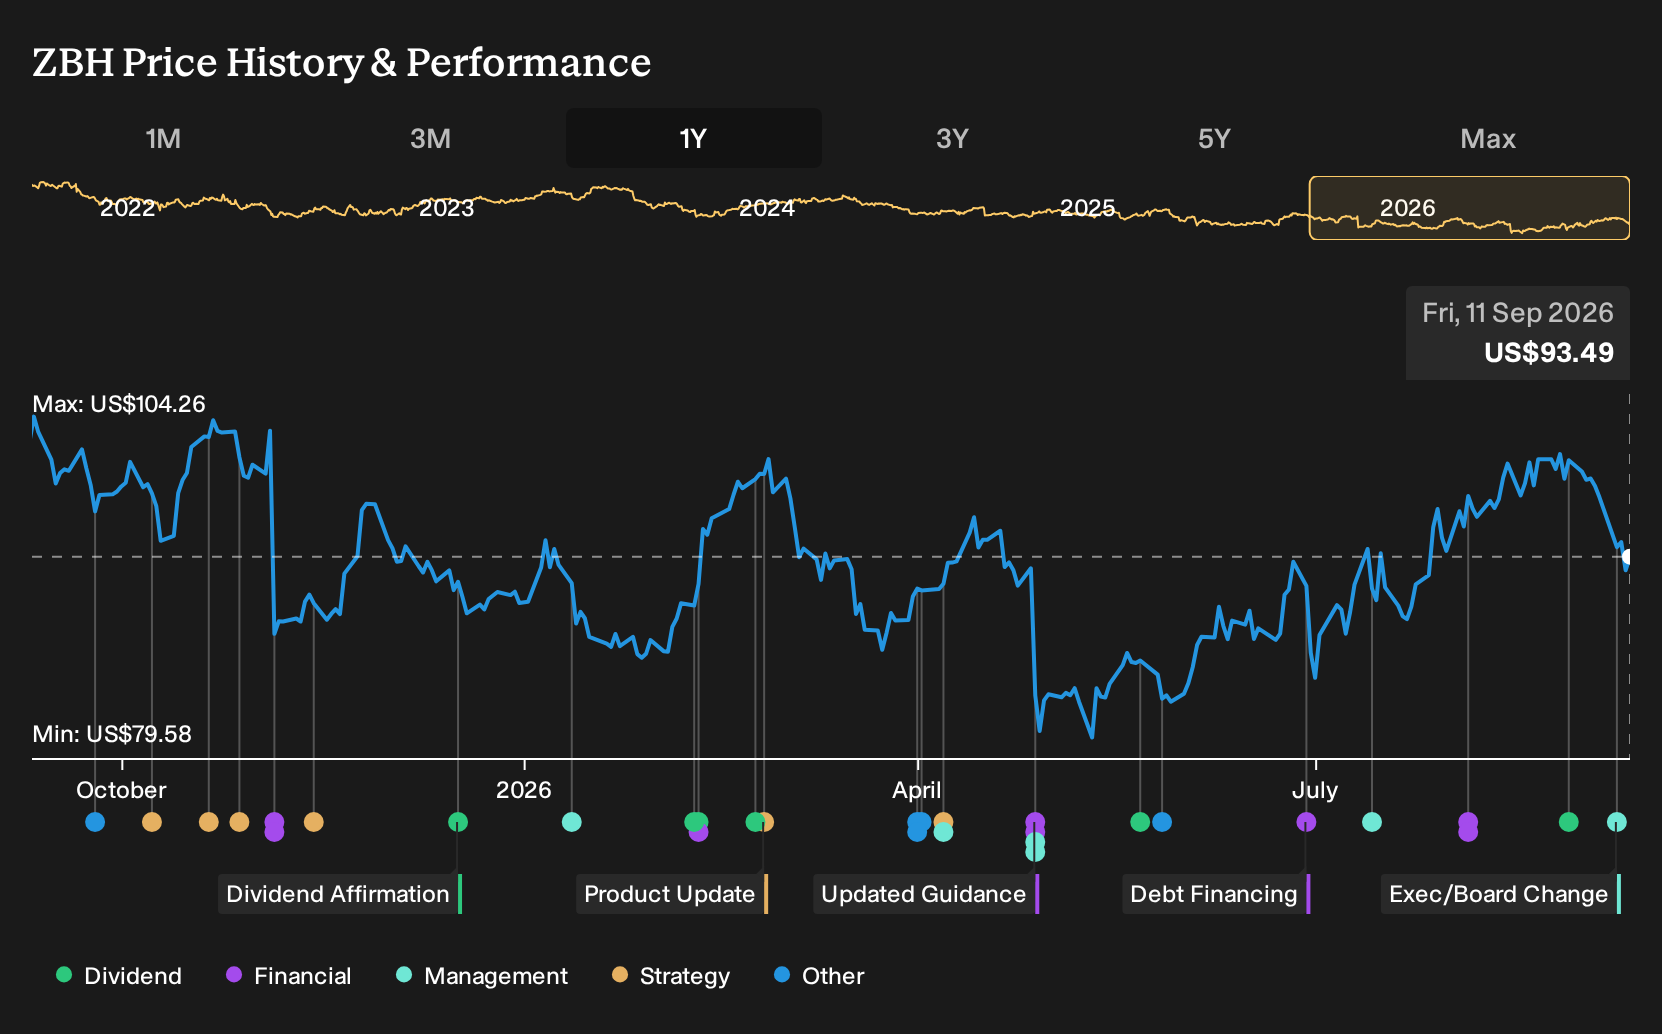
Exploring Other Perspectives
The Simply Wall St Community offers four fair value views for Zimmer Biomet Holdings, stretching from about US$107.57 to roughly US$227.81, so you are seeing a wide spread in expectations. That diversity now faces a real world test. The leadership reshuffle, together with execution risks around acquisitions and robotics, could affect how future performance aligns with any of those numbers.
Explore 3 other Zimmer Biomet Holdings fair value estimates, including one that suggests potential upside of as much as 144% from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zimmer Biomet Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zimmer Biomet Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zimmer Biomet Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Zimmer Biomet Holdings?
If Zimmer Biomet Holdings has sharpened your focus on quality and execution, it can be helpful to scan a wider set of companies that match different risk and income profiles using the Simply Wall St Screener.
- If you want potentially higher upside but can tolerate more volatility, review 21 elite penny stocks with strong financials that already show stronger balance sheets and business quality than many peers.
- For investors who prefer quality at a reasonable entry point, check out 32 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect their underlying metrics.
- If portfolio income is on your mind, focus on 6 dividend fortresses that combine higher yields with an emphasis on resilience and cash generation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com