


Quanta Services (PWR) Wins An AI Grid Upgrade, Is It Still Below Fair Value?
Piper Sandler’s recent upgrade of Quanta Services (PWR) to Strong Buy put fresh attention on the stock as investors weighed data center grid work, a record US$53.4b backlog, and board changes.
Quanta Services has seen brisk short term momentum around the upgrade, with a 1 day share price return of 5.15% lifting the stock to US$650.58 and a 7 day share price return of 4.19%. This comes even though the 30 day share price return declined 5.13% and the 90 day share price return fell 9.55%. Recent board changes and the dividend affirmation come against a backdrop of a 47.97% year to date share price return and a 1 year total shareholder return of 68.83%, building on 3 year and 5 year total shareholder returns of 230.28% and 461.86% as investors reassess both growth potential and risk around its grid and data center exposure.
Spot 89 AI infrastructure stocks that, like Quanta Services, are tied into the heavy power and grid buildout needed to keep AI data centers running.After a sharp run to US$650.58 on the upgrade and a record US$53.4b backlog in hand, is Quanta Services still offering enough upside to justify the risks buyers are taking from here?
Most Popular Narrative: 8% Undervalued
The leading narrative on Quanta Services pegs fair value at about $710 per share, compared with the recent $650.58 close. This implies investors are being asked to weigh quality and growth against a still-full price tag.
The long case is simple: Quanta sits at the intersection of several unusually durable spending waves: aging grid replacement, transmission expansion, utility hardening, manufacturing reshoring, renewable interconnection, and AI-driven power demand. The company’s scale, labor base, customer relationships, and expanding “total solutions” model make it one of the few contractors able to execute very large, complex programs.
See why 63 investors see Quanta Services as 8% undervalued.
Result: Fair Value of $710 (UNDERVALUED)
Still, this story breaks quickly if Quanta Services stumbles on execution for large AI related grid projects, or if backlog growth slows from today’s record base.
Find out about the key risks to this Quanta Services narrative.
Another View On Quanta Services Valuation
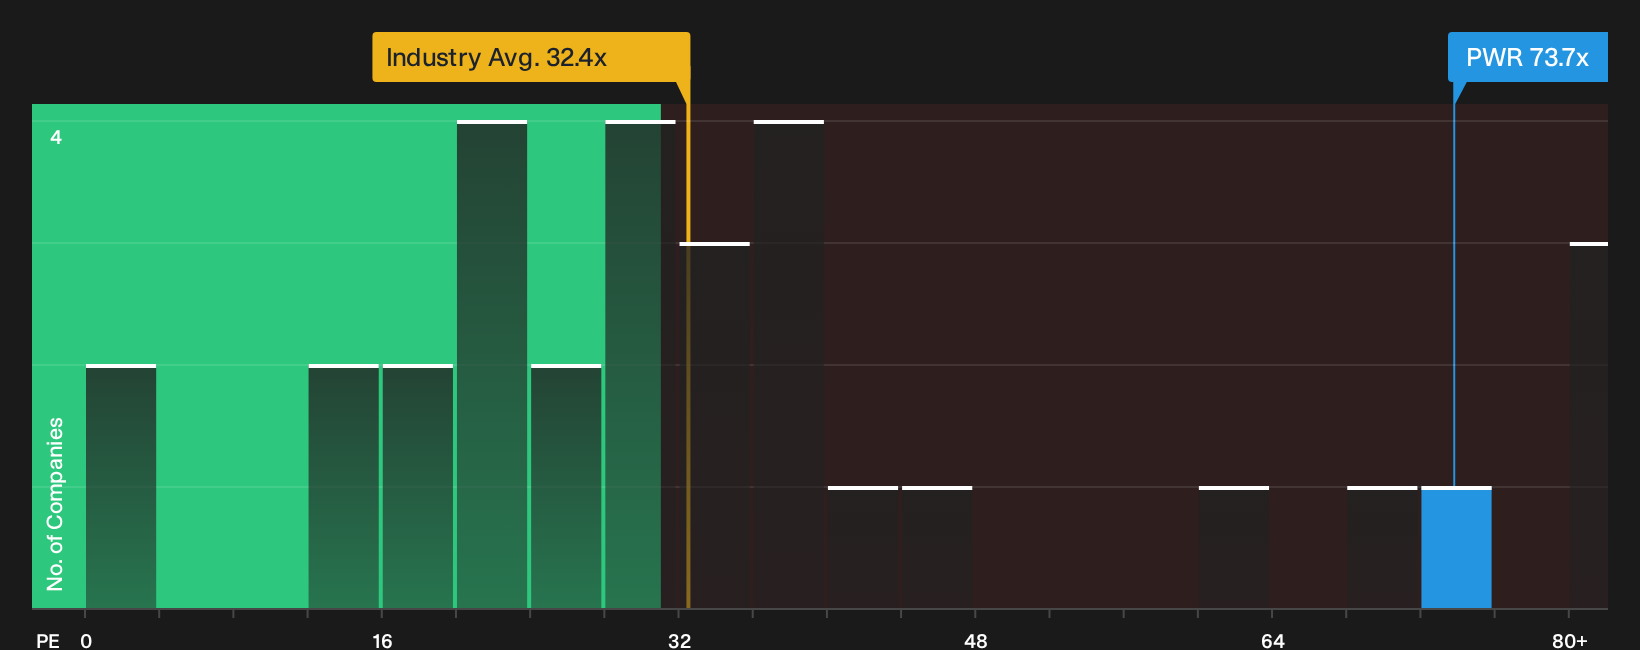
The user narrative sees Quanta Services as about 8% undervalued around $650, but the market multiples tell a different story. PWR trades on a P/E of 73.7x versus 32.4x for the US Construction industry and 35x for peers, while the fair ratio is 38.8x. That gap points to real valuation risk if expectations cool even slightly. Investors may want to consider how comfortable they are paying roughly double the fair ratio for this growth story.
For a closer look at how this pricing stacks up using earnings based benchmarks, including how that rich P/E compares with the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Quanta Services valuation and risk can feel messy, so move quickly, review the data for yourself, and weigh both sides through 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Quanta Services?
If Quanta Services has you thinking harder about where the next edge could come from, do not stop with a single ticker. Use targeted screeners to widen your opportunity set with discipline and structure.
- Target potential mispricing by scanning a refined universe of companies through the 32 high quality undervalued stocks and compare their fundamentals with what you see in Quanta Services.
- Strengthen your focus on resilience by running the 11 resilient stocks with low risk scores and lining up businesses that pair steadier risk scores with balance sheets you can live with.
- Hunt for underfollowed potential by checking the 15 high quality undiscovered gems so you are not only reacting to stocks that already dominate the headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com