


Does Higher Dividends Change The Bull Case For Brady (BRC)?
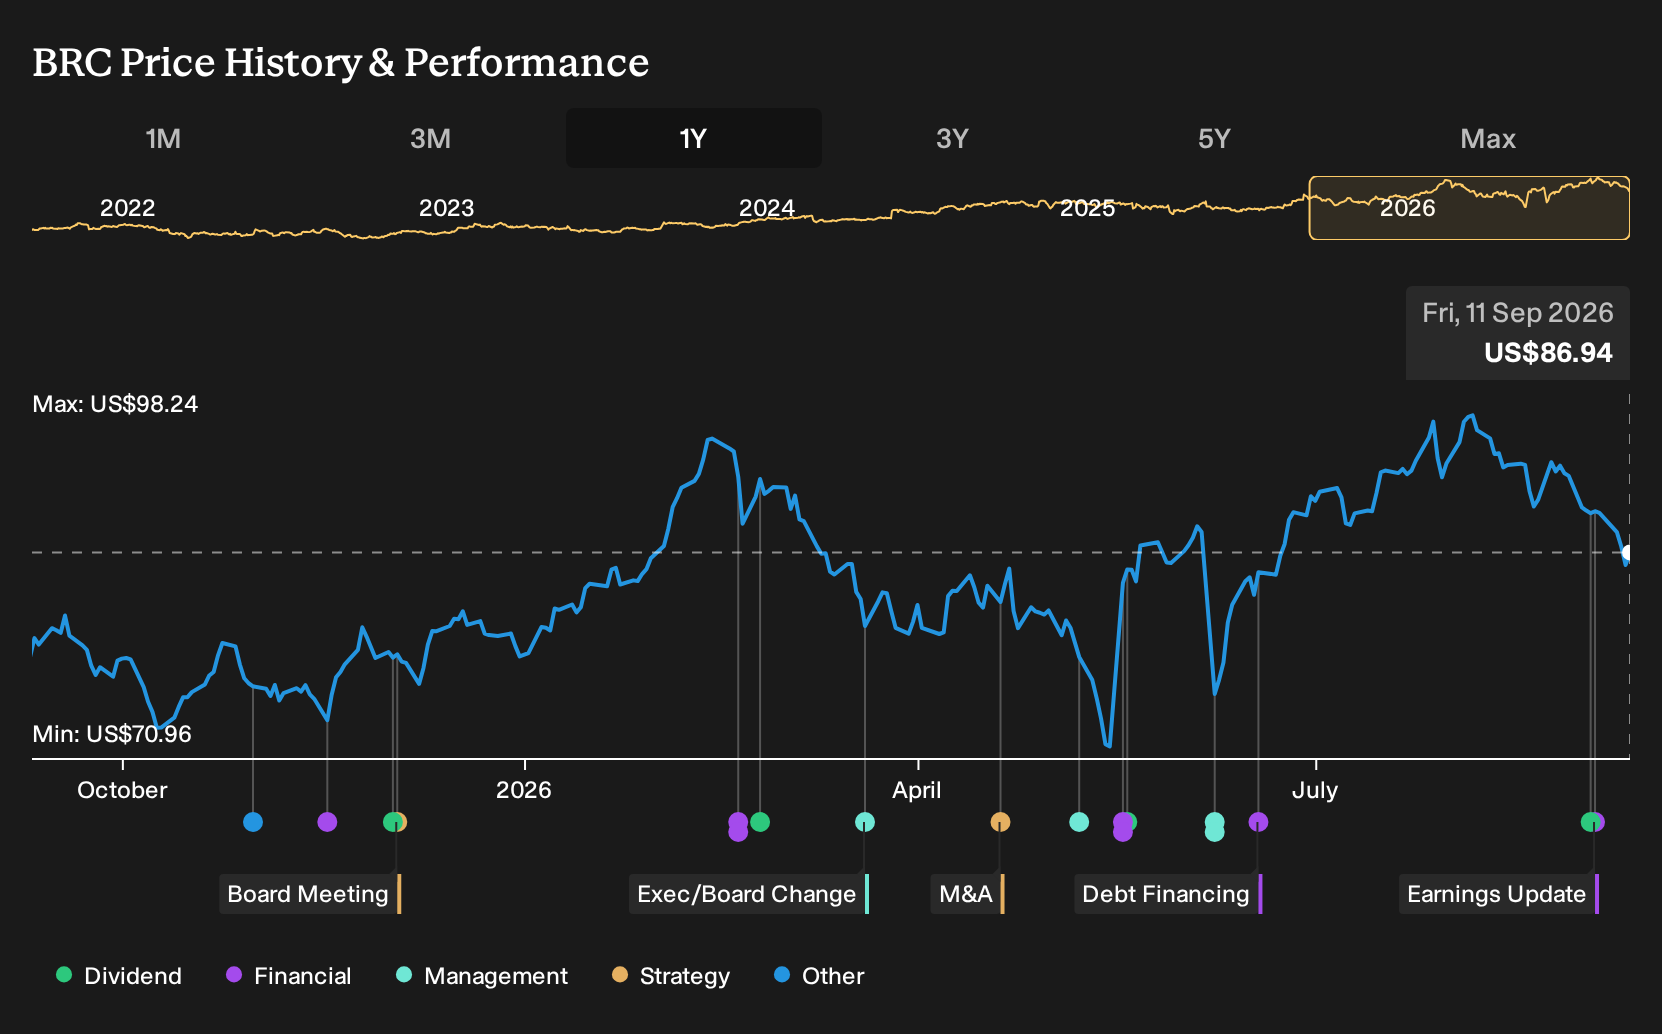
- Brady Corporation reported fourth quarter sales of US$436.9 million and net income of US$45.59 million, with full year sales of US$1.66 billion and profit of US$205.38 million, and also detailed progress on its share repurchase program.
- Management paired higher full year earnings with a larger dividend and a completed buyback tranche, which together indicate a focus on returning cash while still funding the identification and workplace safety operations that underpin Brady’s core business.
- We will now look at how Brady’s higher annual dividend fits into the wider investment narrative around its cash generation and growth.
Brady Investment Narrative Recap
To own Brady, you need to be comfortable with a manufacturing story built on consistent labeling and safety demand, plus steady execution rather than big swings. The latest year shows sales at US$1.66b and profit at about US$205m, which points to a business that is still generating cash while absorbing tariff pressure and uneven demand in Europe and Australia.
In the short term, the key swing factor is whether Brady can keep lifting organic revenue while holding margins as trade costs bite and some regions soften. Current results signal incremental progress rather than a step change. That means the biggest risk, sluggish growth in mature markets and pressure on printers and consumables, remains very much live.
The dividend increase to US$1.00 per share each year is the cleanest signal in this set of announcements. Management has effectively indicated they see the earnings base as solid enough to support slightly higher cash distributions while still funding R&D, acquisitions and ongoing restructuring.
For you as an investor, the raised payout ties directly into the existing catalyst that matters most: whether Brady can turn its spend on new products and traceability solutions into faster recurring revenue. If earnings progress stalls or tariffs and competition bite harder, that dividend looks less comfortable. If execution on new printers, software and safety systems keeps pace with the current earnings profile, the higher distribution simply reflects that underlying progress.
Brady's narrative projects US$3.7b in revenue and US$381.3 million in earnings by 2029. This assumes revenue growth of 31.5% per year and an earnings increase of about US$172 million from US$208.9 million today.
Uncover how Brady's fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community put Brady anywhere between US$75 and about US$228 per share, which is a wide spread. That gap sits beside tariff risk, slow organic growth in some regions and big R&D bets. Use these contrasts to test your own Brady thesis against other investors.
Explore 3 other Brady fair value estimates, including one that suggests as much as 162% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Brady research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Brady. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brady's overall financial health at a glance.
Looking For More Ideas Beyond Brady?
If Brady's mix of steady cash generation and measured capital returns appeals to you, it can help to compare it with other businesses that share similar traits or offer a different balance of income, quality and risk.
- For investors who want resilient balance sheets and solid fundamentals, review the list of solid balance sheet and fundamentals (23 results) and see which companies match that profile.
- If the goal is to focus on financial strength combined with potential mispricing, scan the 32 high quality undervalued stocks and compare how those stocks stack up against Brady on quality and valuation checks.
- When you want to broaden the watchlist with less widely followed opportunities, take a look at the 15 high quality undiscovered gems and see which overlooked businesses merit a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com