


Does Softer Half Year Results Change The Bull Case For Interparfums (ENXTPA:ITP)?
- Interparfums SA reported half year 2026 results with sales of €414.29 million and net income of €65.46 million, both lower than the prior year period, and basic and diluted EPS from continuing operations of €0.7429 compared with €0.8312 a year earlier.
- The combination of softer sales and compressed earnings at Interparfums points to pressure on profitability, which can raise questions about cost control, pricing power and demand trends across its fragrance portfolio.
- We will now examine how Interparfums SA's investment narrative is affected by the weaker half year sales and net income performance.
Compare Interparfums' softer first half with peers facing similar profit pressure by scanning our curated list of list of solid balance sheet and fundamentals (194 results) to identify potential alternatives with sturdier financial footing.
What Is Interparfums' Investment Narrative?
The core belief for owning Interparfums is that its portfolio of licensed fragrance brands can keep pulling in steady demand across regions while management keeps execution tight. The latest half year numbers cut against that story. Softer sales and lower earnings, plus slightly thinner net margins than last year, show that pricing, promotions and cost control are all under pressure at the same time.
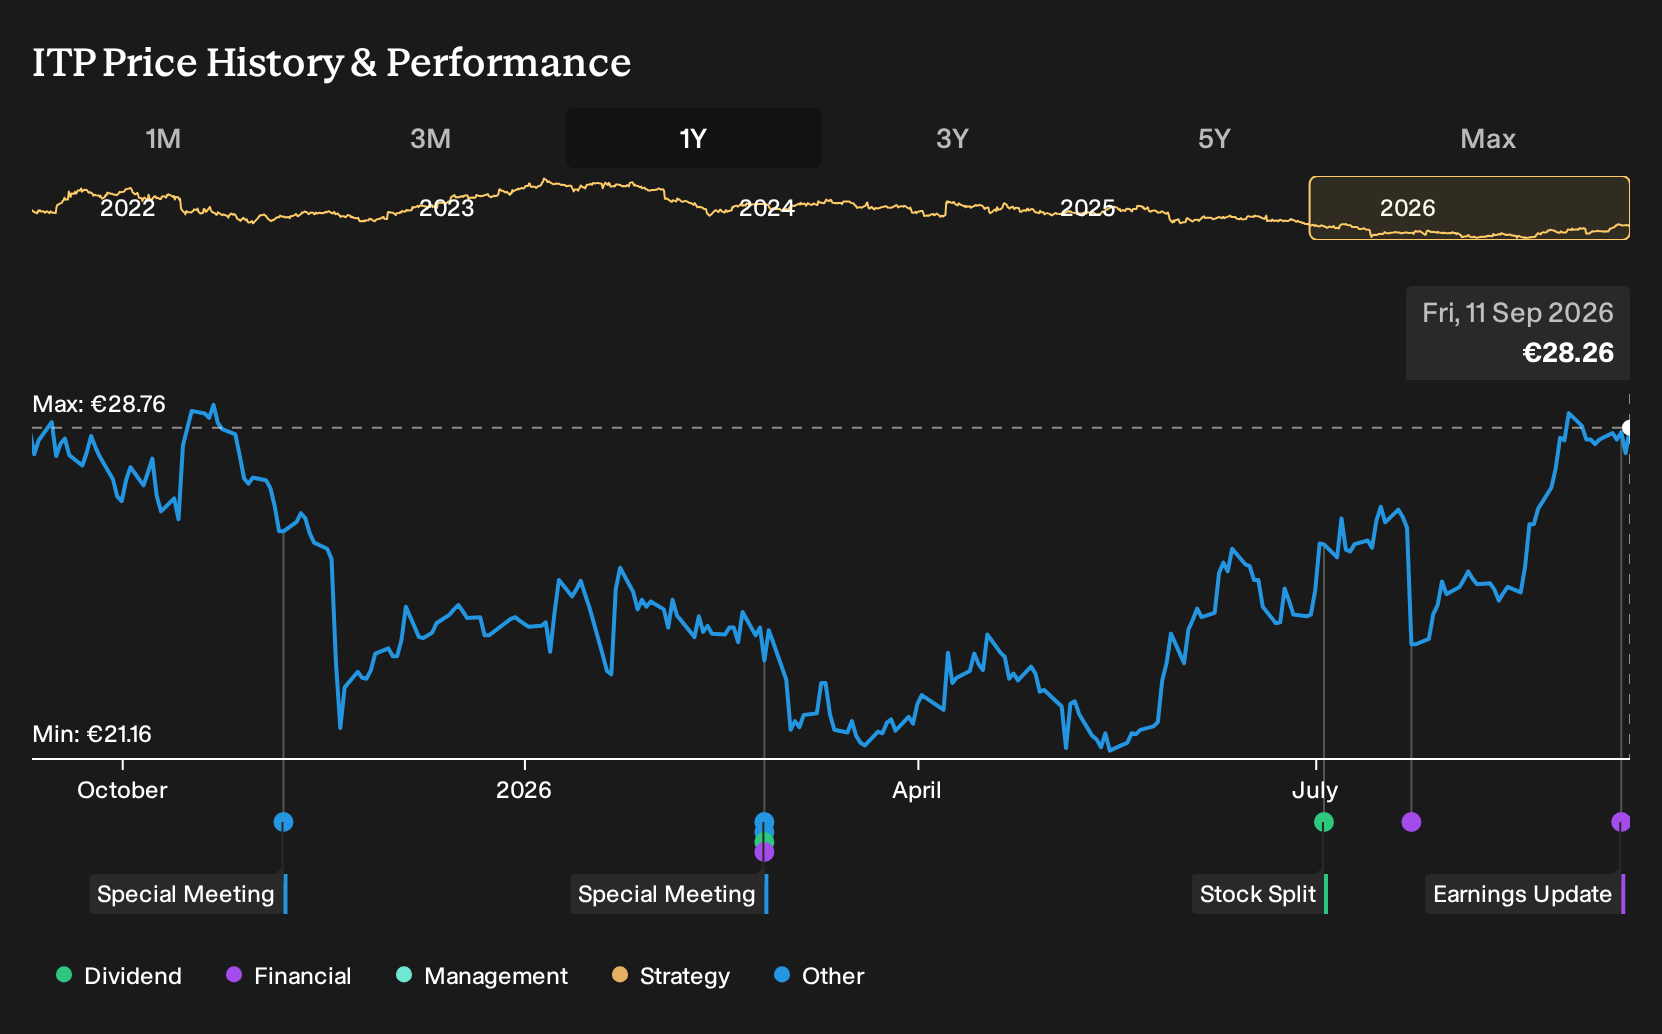
In the short term, the key question is whether this is a bump or a reset for Interparfums. Forecasts still point to mid single digit annual growth in revenue and earnings, yet the stock already trades on a P/E of 20.9x, above the wider European personal products group and only slightly below peer averages. Any wobble in brand momentum or higher capital needs, especially with funding skewed to external borrowing, could matter more now that profit growth has stalled.
That said, there is one quieter issue in the Interparfums story that could prove more important than the earnings miss if ...
There's only one way to know the right time to buy, sell or hold Interparfums. Head to Simply Wall St's company report for the latest analysis of Interparfums's Fair Value.
Exploring Other Perspectives
Interparfums attracts three fair value views from the Simply Wall St Community, with estimates clustering between €28.70 and about €36.25 per share. Those retail forecasts were set before the weaker half year profit number, so treat them as a pre-earnings snapshot and use them as a starting point to explore sharply different opinions on the stock.
Explore 2 other Interparfums fair value estimates, including one that suggests up to 28% potential upside from the current price!
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Interparfums research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Interparfums. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interparfums' overall financial health at a glance.
Looking For More Investment Ideas Beyond Interparfums?
If Interparfums is only one piece of your watchlist, it can help to scan a wider set of companies that match the type of balance sheet strength, value or income profile you prefer. The Simply Wall St Screener lets you filter for specific characteristics so you can build a shortlist that fits your own risk tolerance and style.
- For investors who want potential value coupled with quality fundamentals, review our curated set of 182 high quality undervalued stocks that may warrant a closer look.
- If resilience matters most to you, consider companies highlighted in our 100 resilient stocks with low risk scores and see which businesses score well on financial stability.
- For those focused on reliable income, scan the 162 dividend fortresses and see which high yielding payers match your return and risk preferences.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com