


Performance Food Group (PFGC) Could Be 24% Undervalued As Margin Expansion Drives The Story
Performance Food Group (PFGC) has drawn fresh attention after recent share price weakness, with the stock down about 12% over the past month and roughly 10% over the past 3 months.
For context, Performance Food Group’s recent slide comes after a stronger stretch, with the share price still showing a 6.69% year to date gain but a 1 year total shareholder return that is down 9.72%. The 3 and 5 year total shareholder returns of 53.17% and 107.83% indicate longer term holders have seen much stronger outcomes than those focused on the latest pullback. This suggests the recent weakness reflects a shift in shorter term sentiment rather than a complete reset of the longer term story.
Scan how Performance Food Group compares with other distributors and wholesalers under pressure by reviewing a curated set of 11 resilient stocks with low risk scores that have held up more consistently through recent swings.
After a pullback that leaves Performance Food Group still ahead on a 3 and 5 year view but under water over 12 months, the puzzle is simple: Has most of the upside already played out, or is the recent slide setting up fresh value?
Most Popular Narrative: 24% Undervalued
Against a last close of $93.94, the most followed valuation narrative for Performance Food Group points to a fair value near $123.62. This frames the recent pullback as a pricing gap rather than a complete rethink of the business.
PFG's ongoing shift toward higher-margin independents, specialty, and foodservice categories, along with targeted procurement synergies from recent acquisitions, supports incremental margin expansion and improved operating leverage. This creates upside in both net margin and EBITDA growth.
See why 3 investors see Performance Food Group as 24% undervalued.
Result: Fair Value of $123.62 (UNDERVALUED)
Still, the bullish script for Performance Food Group can unravel if softness in the convenience channel lingers or if acquisition integrations drag longer than analysts currently build into their models.
Find out about the key risks to this Performance Food Group narrative.
Another View On Performance Food Group Valuation
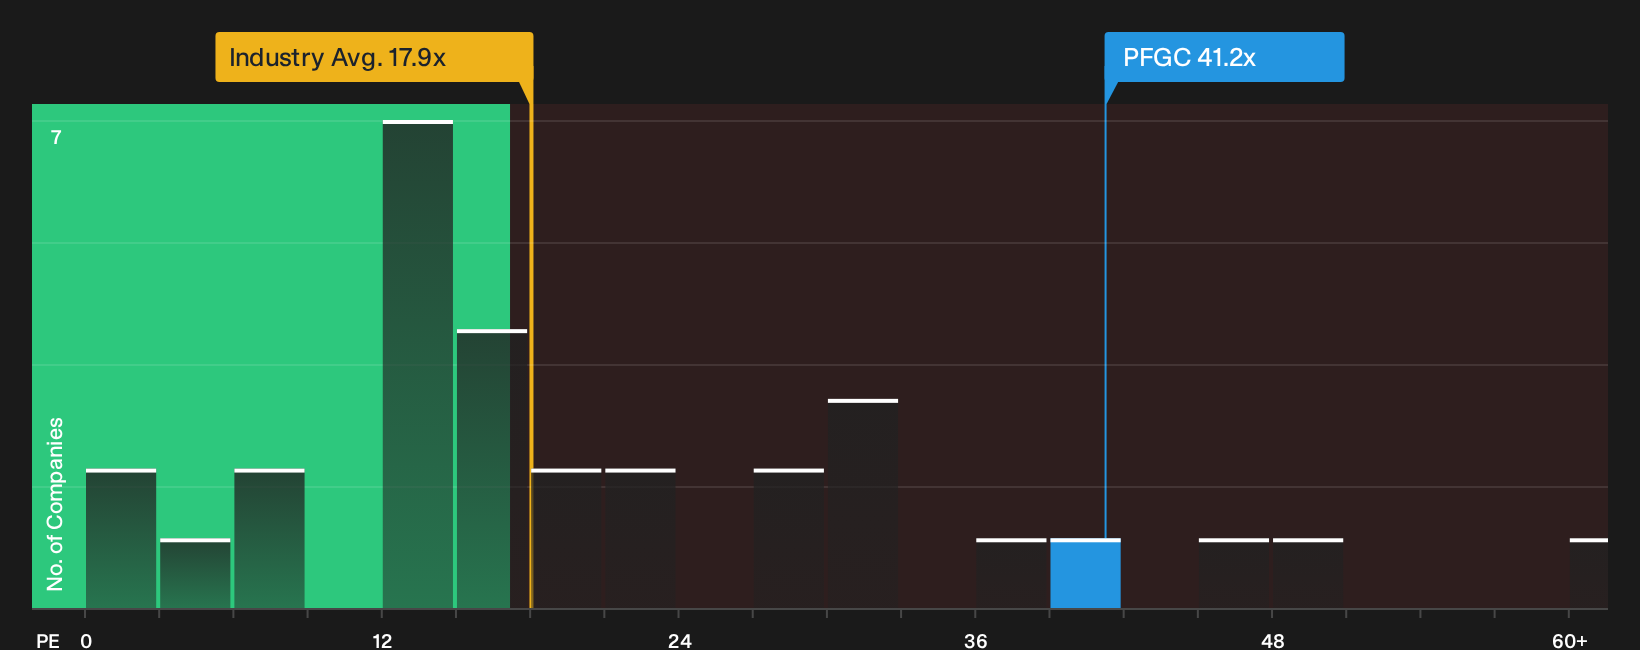
The story looks very different when the focus shifts from discounted cash flows to simple earnings multiples. Performance Food Group currently trades on a P/E of 41.2x, compared with 17.9x for the wider US Consumer Retailing group and about 33x for its direct peers.
The fair ratio for Performance Food Group is estimated at 31.6x P/E, which is much closer to the sector and peer benchmarks than to the current share multiple. That gap suggests valuation risk rather than a clear margin of safety, so the key question is whether future execution justifies staying this far above the pack.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Performance Food Group is clearly split, with optimism on long term execution facing off against concerns about valuation and business risks. Consider moving quickly and stress testing the data for yourself. To see both sides laid out in one place, review the 3 key rewards and 1 important warning sign
Looking for more ideas beyond Performance Food Group?
Do not stop with Performance Food Group. Broaden your watchlist with fresh angles on quality, value, and resilience using targeted screeners that surface opportunities fast.
- Pinpoint resilient balance sheets and cleaner fundamentals by scanning a focused list of solid balance sheet and fundamentals (23 results) that cuts through noise and surfaces financially sturdier candidates.
- Hunt for quality trading at a discount by reviewing a curated 32 high quality undervalued stocks that highlights stocks where fundamentals and price appear out of sync.
- Target income plus staying power by checking a hand picked 6 dividend fortresses designed to spotlight higher yielding payers with more robust profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com