


Why Brightstar Lottery (BRSL) Is Getting Attention Today
Brightstar Lottery (BRSL) has moved to overhaul its balance sheet by issuing €500,000,000 in 4.875% senior secured notes due 2032, while also launching a tender offer for its existing 2028 bonds and targeting shorter-term credit facilities.
Brightstar Lottery’s refinancing push lands after a tough stretch for holders, with the share price at $10.80, a year to date share price return of down 29.41%, and a 1 year total shareholder return of down 30.91%. The recent 30 day share price return of down 8.40% suggests momentum has been fading, despite a 1 day share price gain of 1.31% as investors reassess risk around its debt profile and the long running 3 year total shareholder return of down 53.51%.
Spot opportunities beyond Brightstar Lottery by scanning a hand picked 32 high quality undervalued stocks that combine stronger recent momentum with balance sheets investors may find easier to live with.After a sharp reset in Brightstar Lottery’s share price and the addition of a new layer of longer dated debt, the key question is whether most of the easy upside has already been realised or if the more significant part of the rerating still lies ahead.
Most Popular Narrative: 35% Undervalued
Against a last close of $10.80, the most followed narrative pegs Brightstar Lottery’s fair value at $16.71. This frames the refinancing against a much higher long run valuation anchor built on digital growth, contract renewals, and cost savings.
Regulatory liberalization and successful contract renewals (notably Italy Lotto secured through 2034 and new or extended deals in Missouri, Portugal, and France) are expanding the addressable market and extending Brightstar's average revenue-weighted contract life to 7 years, thus providing long-term revenue stability and enhanced cash flow visibility.
See why 2 investors see Brightstar Lottery as 35% undervalued.
Result: Fair Value of $16.71 (UNDERVALUED)
Still, tighter gambling rules in Italy or the US, along with higher than expected costs on long term contracts, could quickly weaken the bullish Brightstar Lottery narrative.
Find out about the key risks to this Brightstar Lottery narrative.
Another View: Cash Flows Point A Different Way
Brightstar Lottery may look appealing on P/E screens at 10.5x, compared with a fair ratio of 12.8x and a US Hospitality average of 21.4x. However, the SWS DCF model points to a future cash flow value of just $2.30 per share, well below the current $10.80. Which signal do you trust more, earnings or cash flows.
Look into how the SWS DCF model arrives at its fair value.
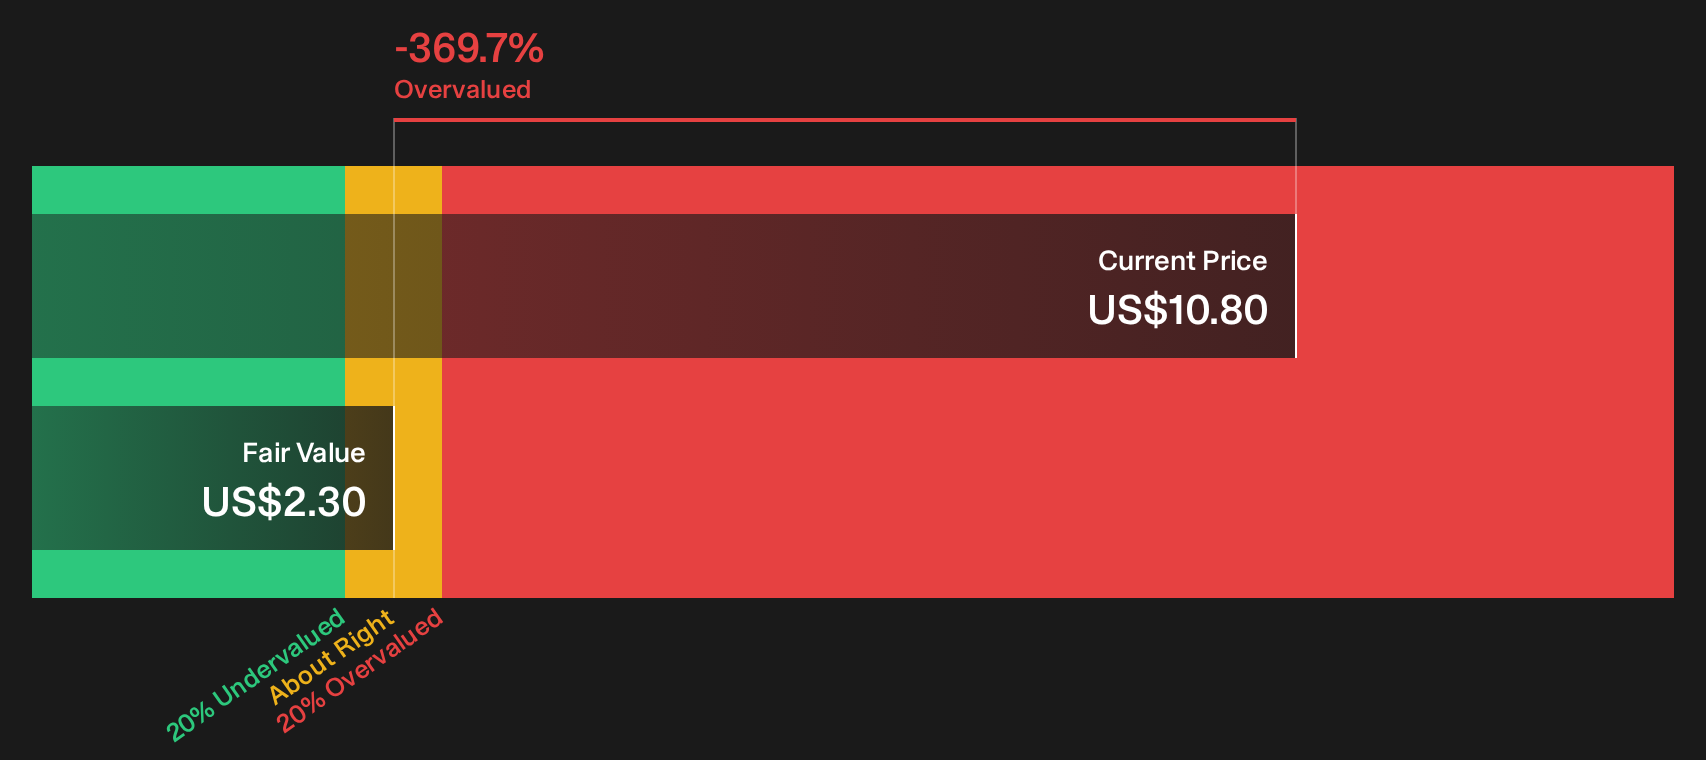
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brightstar Lottery for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Brightstar Lottery so far. If you want to move quickly and rely on your own judgement, weigh up the 3 key rewards and 4 important warning signs.
Looking for more Brightstar Lottery investment ideas?
If Brightstar Lottery has sharpened your focus on risk and reward tradeoffs, do not stop here. Use Simply Wall Street's tools to spot fresh setups before they move away.
- Target resilient compounding potential by scanning a 6 dividend fortresses that may appeal if you want income alongside capital preservation.
- Hunt for mispriced quality through a 15 high quality undiscovered gems that surfaces businesses with fundamentals many investors have not yet fully appreciated.
- Prioritize sleep at night potential with a 11 resilient stocks with low risk scores that filters for balance sheets and risk profiles some investors may find more comfortable.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com