


3 Growth Companies With High Insider Ownership Growing Earnings Up To 132%
The United States market has experienced a flat performance in the last week, yet it has shown a 14% increase over the past year with earnings projected to grow by 17% annually. In this environment, identifying growth companies with high insider ownership can be advantageous as they often indicate strong confidence from those closest to the business and potential alignment of interests between insiders and shareholders.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Uxin (UXIN) | 34.3% | 69.4% |
| Upstart Holdings (UPST) | 14.2% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 61.3% |
| Precigen (PGEN) | 11.7% | 55.4% |
| Nu Holdings (NU) | 22.8% | 21.8% |
| Karman Holdings (KRMN) | 14.4% | 54% |
| Himax Technologies (HIMX) | 29.2% | 70.2% |
| Dave (DAVE) | 16.9% | 23.2% |
| Carlyle Group (CG) | 27.4% | 20.5% |
| Almonty Industries (ALM) | 10.8% | 38% |
Below we spotlight a couple of our favorites from our exclusive screener.
Starling Oncology (STLN)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Starling Oncology, Inc. is an oncology company offering a range of oncology services in the United States with a market cap of $628.82 million.
Operations: The company generates revenue from Patient Services ($237.95 million), Specialty Pharmacy ($343.46 million), and Clinical Trials & Other ($5.84 million).
Insider Ownership: 12.8%
Earnings Growth Forecast: 111.5% p.a.
Starling Oncology exhibits strong growth prospects with expected revenue growth of 26.1% annually, surpassing the US market average. Despite recent volatility in share price and significant insider selling, the company maintains a favorable valuation compared to peers. Starling's innovative technology platform, Nexus, aims to streamline oncology care processes and improve efficiency. Recent financial flexibility is enhanced by a $25 million revolving credit facility, supporting its strategic initiatives and anticipated profitability within three years.
- Unlock comprehensive insights into our analysis of Starling Oncology stock in this growth report.
- Insights from our recent valuation report point to the potential undervaluation of Starling Oncology shares in the market.

Commerce.com (CMRC)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Commerce.com, Inc. operates an artificial intelligence-driven commerce ecosystem across multiple regions including the United States, Europe, the Middle East, Africa, and the Asia Pacific with a market cap of $0.29 billion.
Operations: The company's revenue segment includes Internet Information Providers, generating $346.90 million.
Insider Ownership: 10.8%
Earnings Growth Forecast: 132.3% p.a.
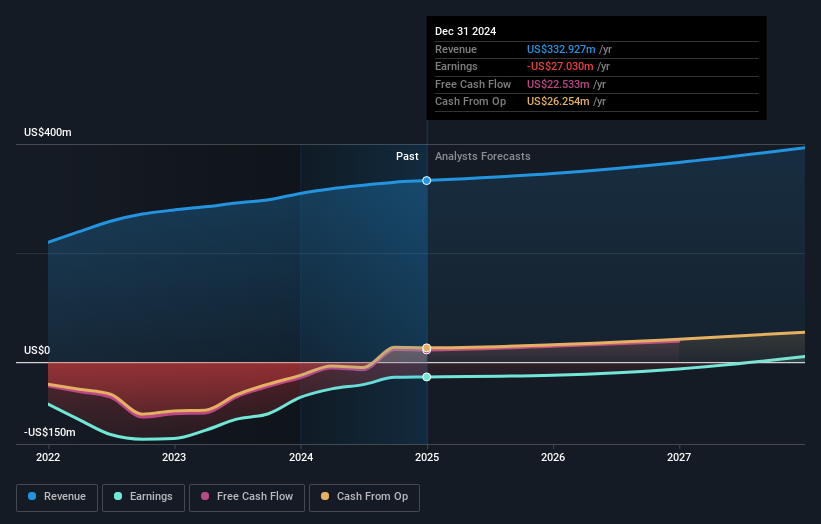
Commerce.com demonstrates potential as a growth company with high insider ownership, despite its volatile share price. The company's recent strategic partnership with WP Engine enhances its eCommerce capabilities, supporting mid-market brands. While revenue growth is forecasted to lag behind the US market at 1.4% annually, Commerce.com is expected to become profitable within three years. Recent buyback announcements and inclusion in multiple Russell indices reflect confidence in long-term value creation and operational resilience.
- Click to explore a detailed breakdown of our findings in Commerce.com's earnings growth report.
- Our expertly prepared valuation report Commerce.com implies its share price may be lower than expected.
Tesla (TSLA)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Tesla, Inc. is involved in the design, development, manufacturing, leasing, and sale of electric vehicles and energy generation and storage systems globally with a market capitalization of approximately $1.44 trillion.
Operations: The company's revenue segments include $90.82 billion from automotive activities and $12.80 billion from energy generation and storage solutions.
Insider Ownership: 28.5%
Earnings Growth Forecast: 34.4% p.a.
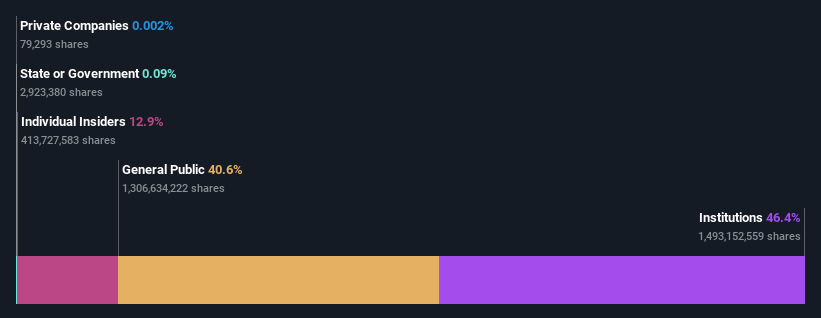
Tesla's growth trajectory is marked by significant insider ownership and strategic collaborations, such as the recent alliance with Pacific Gas and Electric to develop a Virtual Power Plant. Despite past shareholder dilution, Tesla's earnings are forecasted to grow substantially at 34.4% annually, outpacing the market. However, profit margins have declined year-over-year. The deployment of 500 Tesla Semis by Einride AB highlights Tesla's expanding influence in electric freight solutions across North America.
- Click here to discover the nuances of Tesla with our detailed analytical future growth report.
- Upon reviewing our latest valuation report, Tesla's share price might be too optimistic.
Make It Happen
- Explore the 177 names from our Fast Growing US Companies With High Insider Ownership screener here.
- Want To Explore Some Alternatives? The latest GPUs need a type of rare earth metal called Dysprosium and there are only 28 companies in the world exploring or producing it. Find the list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com