


Varonis Systems (VRNS) Could Be 11% Below Fair Value Following Proofpoint Deal Talk
Varonis Systems (VRNS) is back in focus after Bloomberg reported that Proofpoint is in talks to acquire the cybersecurity provider in a potential multi billion dollar take private transaction.
At a share price of $45.12, Varonis Systems has given investors a strong 90 day share price return of 33.25% and a year to date share price return of 40.82%, even though the 1 year total shareholder return is down 19.70%. This suggests that momentum has picked up more recently as takeover talk and new Snowflake partnership milestones have reshaped how the market prices both its growth potential and perceived risk.
Spot similar takeover and AI security momentum by scanning our hand picked list of 32 AI small caps, which, like Varonis Systems, sits at the crossroads of data protection and enterprise software.Varonis Systems has already priced in a burst of takeover talk and AI security enthusiasm. The real question now is whether you pay up at today’s level or wait and risk missing any deal premium altogether.
Most Popular Narrative: 11% Undervalued
The most followed narrative on Varonis Systems pegs fair value at $50.68, above the last close of $45.12. This frames the current story as a discount tied closely to its SaaS transition and AI security push.
Rapid proliferation of enterprise data and increased AI adoption are materially boosting demand for automated, comprehensive data protection, positioning Varonis to capture higher revenue growth and expand its total addressable market as organizations prioritize data security for both compliance and risk mitigation.
Expanding global data privacy regulations and mounting cyber threats are compelling enterprises to invest in advanced unstructured data security and governance, Varonis' differentiated platform (with new FedRAMP authorization, SaaS model, and deep cloud coverage) stands to benefit from long-term, recurring revenue tailwinds as security budgets become more data-centric.
See why 9 investors see Varonis Systems as 11% undervalued.
Result: Fair Value of $50.68 (UNDERVALUED)
Still, the bullish Varonis Systems story can break if the SaaS transition continues to pressure revenue and margins, or if larger platforms squeeze pricing and slow ARR momentum.
Find out about the key risks to this Varonis Systems narrative.
Another View on Varonis Systems Valuation
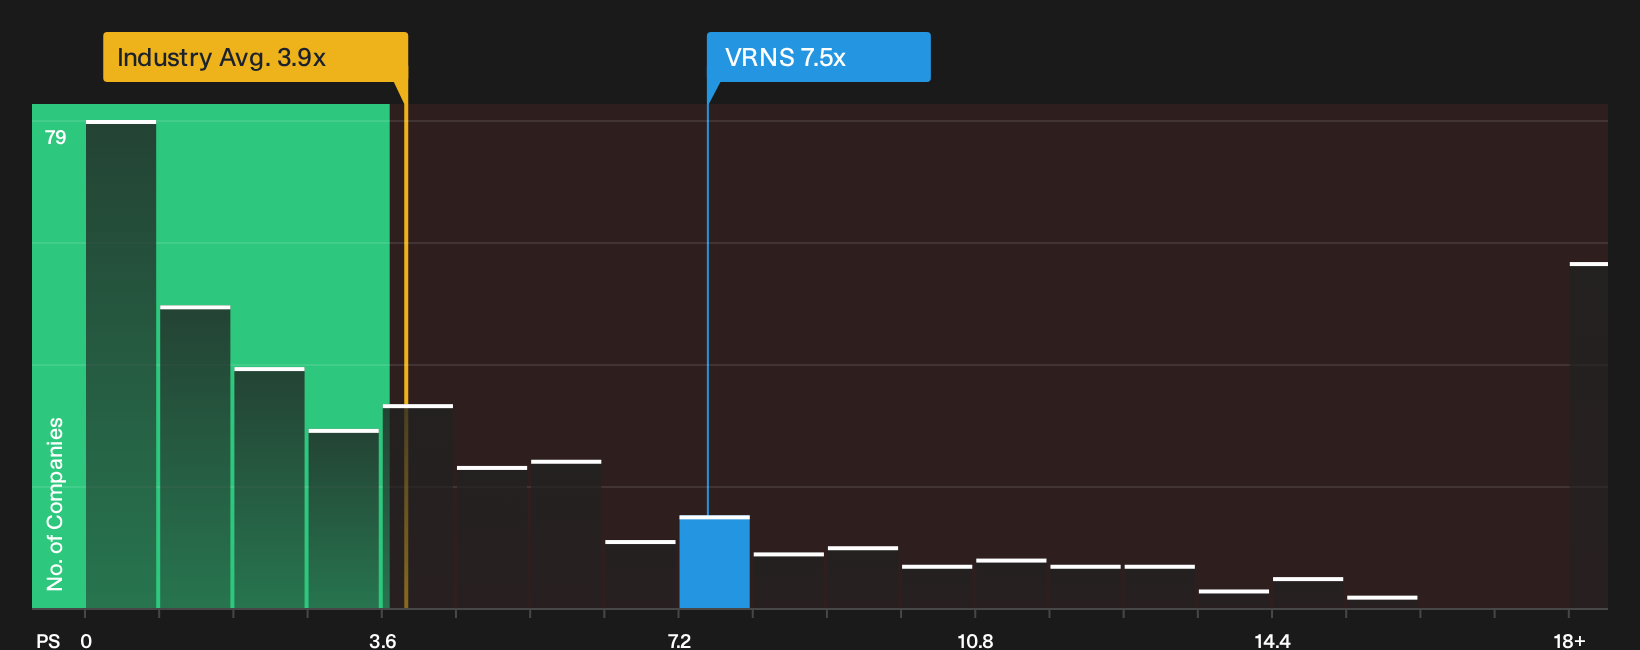
The market story around Varonis Systems looks different once the focus shifts from future earnings and analyst targets to what investors pay for each dollar of current sales. On a P/S of 7.5x, the stock trades well above the US software industry on 3.9x and a peer average of 5.1x. The fair ratio sits lower again at 5.7x, which raises the question of whether takeout speculation is inflating valuation risk more than the bullish narrative suggests.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Varonis Systems is clear, so move quickly, review the underlying numbers, and then weigh the 2 key rewards and 1 important warning sign against your own thesis.
Looking for more investment ideas beyond Varonis Systems?
You have momentum on Varonis Systems already, so do not stop there. Use the screener to surface fresh ideas that match your style and risk tolerance.
- Target quality at a discount by scanning the 32 high quality undervalued stocks that combine solid fundamentals with prices that lag their underlying metrics.
- Strengthen your portfolio foundation by reviewing a list of solid balance sheet and fundamentals (23 results) that can help cushion shocks when sentiment turns.
- Hunt for overlooked potential by checking a 15 high quality undiscovered gems before the wider market pays closer attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com