


BFSI Growth Might Change The Case For Investing In Cognizant Stock (CTSH)
- Cognizant Technology Solutions recently presented at Citi’s 2026 Global TMT Conference in New York, where CFO Jatin Pravinchandra Dalal outlined capital allocation priorities and business trends.
- The firm’s banking, financial services and insurance segment delivered double-digit growth, while AI now assists roughly 40% of software engineering work, signaling a meaningful shift in how projects are delivered.
- We will now assess how Cognizant Technology Solutions' investment narrative is affected by double-digit BFSI growth and deepening AI-assisted delivery.
Scan beyond Cognizant Technology Solutions and line up other AI driven IT and software service plays using our curated 89 AI infrastructure stocks for your next round of ideas.
Cognizant Technology Solutions Investment Narrative Recap
Cognizant Technology Solutions appeals to investors who buy into a simple premise. Large enterprises still need help modernizing core systems, and AI heavy workflows can make that delivery more efficient rather than instantly replacing it. The recent Citi conference update on double digit BFSI growth and 40% AI assisted engineering work supports that thesis but does not radically change it.
The near term swing factor remains execution on AI driven delivery while keeping project pricing and margins intact as clients push for productivity. The biggest risk still sits in rapid client adoption of platform based, as a service models that bypass Cognizant, which could matter more than any single quarter of BFSI strength.
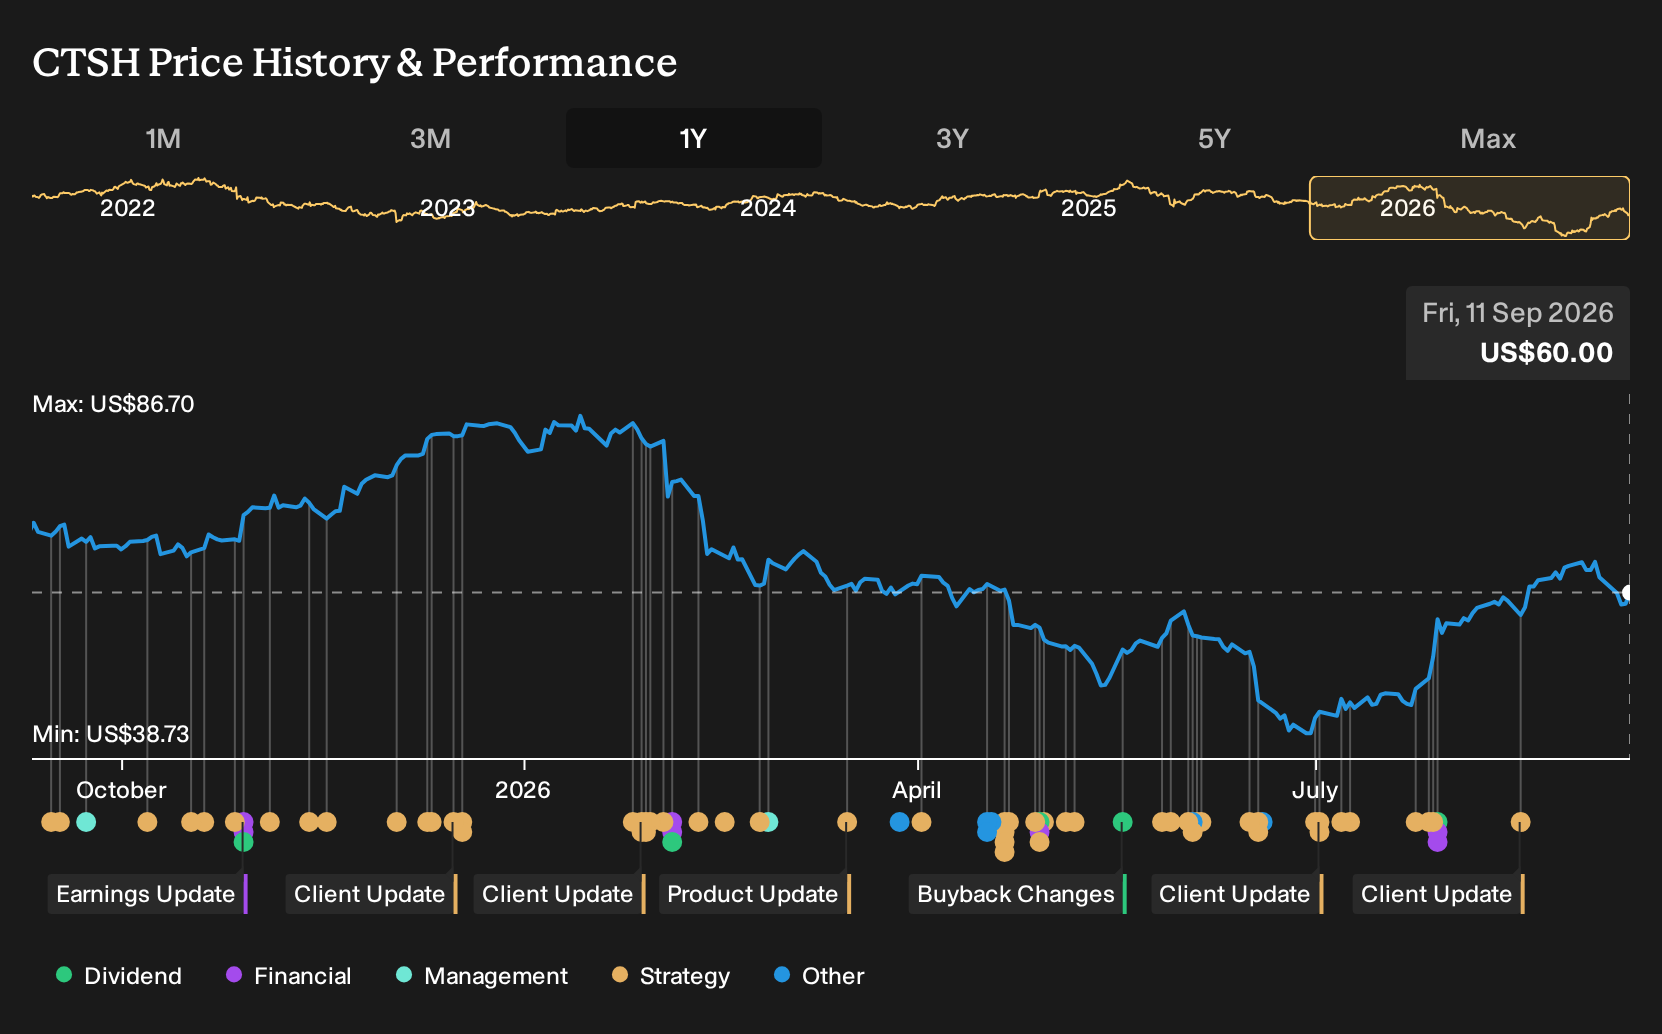
The most relevant disclosure tied to this conference is Cognizant Technology Solutions reaffirming its 50/25/25 capital allocation framework along with an accelerated US$1b buyback. For an investor, this signals that management is choosing to return a meaningful portion of cash while still keeping flexibility for internal projects and potential deals.
This mix connects directly to the core catalysts. AI heavy productivity work, large BFSI and health related transformation projects, and internal automation investments all require steady spending. At the same time, the repurchase program can offset any drag from slower revenue growth than the wider US market. It also raises the bar on execution risk if operating margins come under pressure.
Cognizant Technology Solutions' analyst narrative points to revenues of US$24.9b and earnings of US$3.1b by 2029, built on assumed yearly top line expansion of 5.2%. This implies an earnings increase of roughly US$0.9b from US$2.2b today to the 2029 consensus level.
Uncover why Cognizant Technology Solutions' fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on pricing pressure from AI tools. The most cautious analysts already pencilled in slower annual revenue growth of about 4% to US$24.3b and earnings near US$3.0b by 2029, paired with a low 7x P/E. You can treat the Citi update on Cognizant Technology Solutions as fresh input that might shift those assumptions in either direction and compare several viewpoints before deciding what feels reasonable.
Explore 8 other Cognizant Technology Solutions fair value estimates, including one that suggests as much as 26% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cognizant Technology Solutions research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cognizant Technology Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cognizant Technology Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cognizant Technology Solutions?
If Cognizant Technology Solutions has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you line up other stocks with different risk and return profiles before you commit fresh capital.
- For investors who care most about quality at a sensible entry point, use our 32 high quality undervalued stocks to see which companies currently combine strong fundamentals with pricing that may look appealing on the numbers.
- If capital preservation is front of mind, filter for stability with the 11 resilient stocks with low risk scores and focus your research on businesses that score well on balance sheet strength and earnings consistency.
- When you want to unearth fresh ideas away from the usual tickers, the 15 high quality undiscovered gems can surface companies with solid financial profiles that are not yet widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com