


NVR (NVR) Faces A Valuation Split, Is The Stock Undervalued Or Overvalued?
NVR (NVR) recently closed at US$6,160.76, with the share price down over the past month and past 3 months. That softer run follows modest annual revenue and net income growth.
Over the past year, NVR has seen its short term share price momentum fade, with a year to date share price return down 15.36% and a 1 year total shareholder return down 25.58%. However, the 5 year total shareholder return of 24.01% still points to a much steadier long term picture.
Scan beyond NVR and find other builders and related companies that match this kind of muted momentum profile using the hand picked 11 resilient stocks with low risk scores.
NVR now trades at a double digit discount to both analyst targets and estimated fair value. Is that a simple pricing gap, or is the market rightly cautious after this weaker share price run?
Most Popular Narrative: 64% Overvalued
On Esteban's framework, NVR screens as materially overvalued, with a narrative fair value of $3,758 against the recent close at $6,160.76. That gap anchors a much more cautious stance than the current share price implies.
NVR converts the most capital-intensive, most cyclical, most balance-sheet-fragile activity in U.S. industrial business, residential land development, into a software-like compounder with 30% ROIC and net-cash balance sheets. The mechanism is the Lot Purchase Agreement (LPA) model: NVR pays non-refundable deposits of approximately 10% of finished lot value to third-party developers for the right to take down lots on a quarter-by-quarter basis. The capital that peers tie up in raw land is instead redeployed by NVR into share buybacks. The risk that peers absorb in housing downturns is instead managed by NVR walking away from projects by forfeiting deposits.
See why 6 investors see NVR as 64% overvalued.
Result: Fair Value of $3,758 (OVERVALUED)
Still, the NVR narrative could be knocked off course if the Lot Purchase Agreement model fails to protect returns in a deep housing downturn, or if competitors successfully copy it.
Find out about the key risks to this NVR narrative.
Another View On NVR's Value
NVR looks expensive on Esteban's narrative, yet the SWS DCF model points in the opposite direction. At $6,160.76, the shares sit about 13.3% below an estimated future cash flow value of $7,106.27. That framing presents NVR as undervalued rather than stretched. Which story do you lean toward?
For a closer look at how that cash flow estimate is built and what might stress test it in different scenarios, Look into how the SWS DCF model arrives at its fair value.
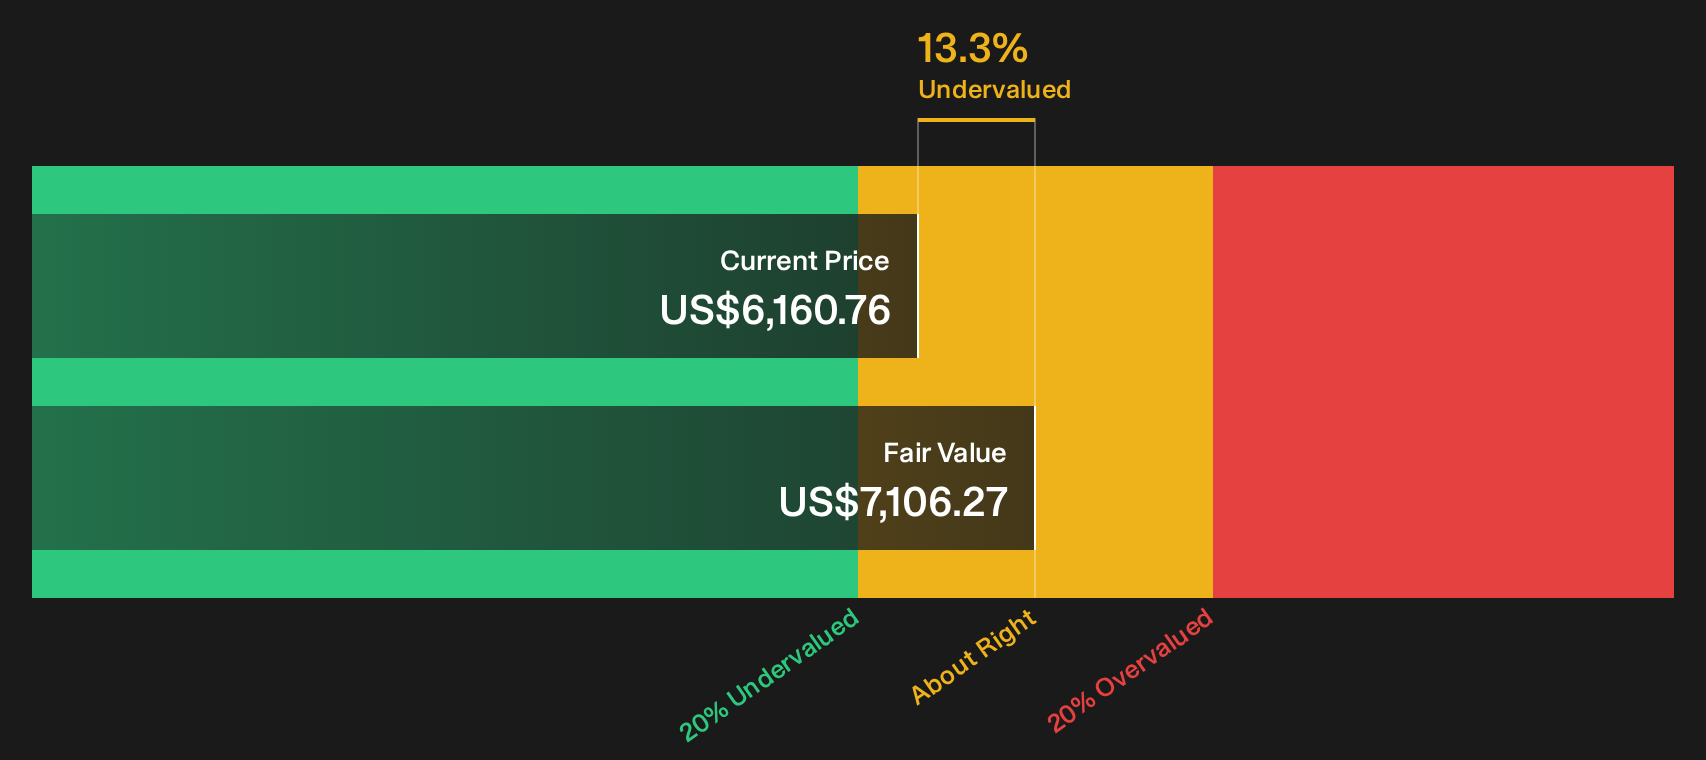
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NVR for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on NVR split between caution and opportunity, consider acting promptly and evaluating the story against your own thresholds using the 1 key reward.
Looking for more NVR investment ideas?
If NVR feels interesting but not quite enough on its own, you can broaden your watchlist now to spot opportunities others ignore before they become crowded trades.
- Target resilient prospects with cleaner finances by running the list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced opportunities that combine quality and value through the 32 high quality undervalued stocks.
- Identify potential cash income streams by scanning for high yielding candidates using the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com