


Essent Group (ESNT) Is Getting Attention, What Is The Market Weighing?
Essent Group (ESNT) has drawn attention after recent share performance data showed the stock down around 2% over the past month but up roughly 14% in the past 3 months.
At a share price of $68.18, Essent Group has given investors a 10.06% total shareholder return over the past year, so the recent 1-month share price softness looks more like a pause within a longer stretch of gains, where momentum has been building rather than fading.
Scan beyond Essent Group and see how other financials with strong balance sheets and fundamentals are trading with our curated list of solid balance sheet and fundamentals (23 results)
Bears see Essent Group as a mortgage insurer with earnings under pressure, while bulls point to a solid recent run and sizeable implied discount. Which story does the valuation actually support next?
Most Popular Narrative: 9% Undervalued
Essent Group’s most followed valuation storyline points to a fair value of about $74.71 per share compared with the last close at $68.18, which frames the current price as a discount that hinges on how the mortgage insurance cycle and capital returns play out.
The company's expansion into adjacent credit risk management, through reinsurance (Essent Re) and advisory services, provides new and growing fee-based revenue streams, which support long-term earnings growth and diversification beyond traditional mortgage insurance. Essent's strong capital position is enabling substantial buybacks at undervalued price levels, which, combined with disciplined capital allocation and book value growth, is likely to increase earnings per share and shareholder returns.
See why 1 investors see Essent Group as 9% undervalued.
Result: Fair Value of $74.71 (UNDERVALUED)
Still, the Essent Group story can change quickly if housing affordability weakens further or if new underwriting technology sidelines traditional private mortgage insurers.
Find out about the key risks to this Essent Group narrative.
Another View on Essent Group’s Valuation
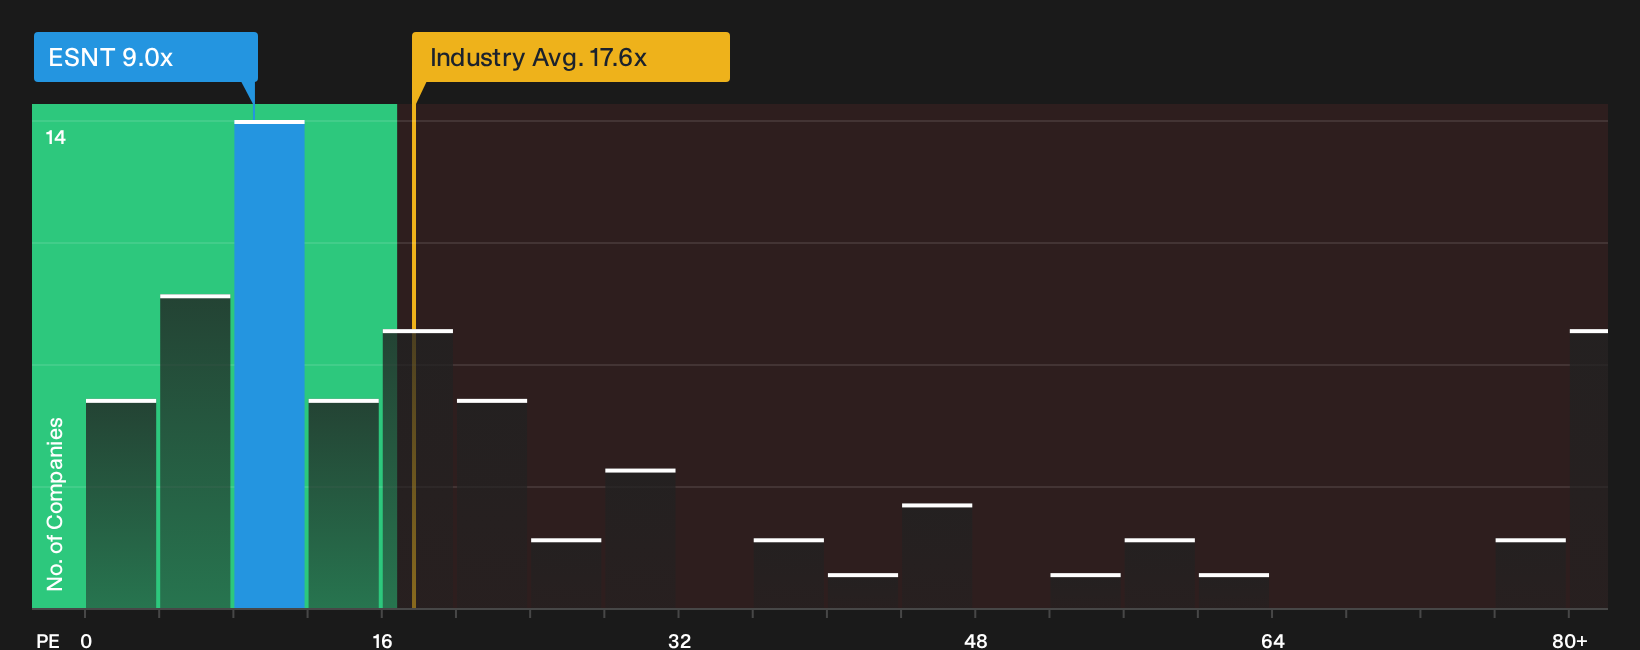
The story looks different when switching from fair value estimates to simple P/E math. Essent Group trades on roughly 9x earnings, which is above its peer average of 8.9x but below the US Diversified Financial industry at 17.6x and under an estimated fair ratio of 10x. Is the market underpricing quality or already baking in the good news?
To see how this earnings multiple stacks up in more detail, and what that gap to the fair ratio might mean for future repricing risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Essent Group is clearly split, so it makes sense to move quickly, review the data yourself and pressure test both sides of the argument. To see how the key upside drivers stack up against the main concerns, take a focused look at the 1 key reward and 2 important warning signs.
Looking for more ideas beyond Essent Group?
You have already done the work on Essent Group, so keep that momentum going and use the Simply Wall Street Screener to surface fresh leads.
- Target potential mispricing by scanning a curated set of high quality opportunities with pricing that still looks appealing using the 32 high quality undervalued stocks.
- Prioritise resilience in your watchlist and focus on businesses with stronger financial risk profiles through the 11 resilient stocks with low risk scores.
- Hunt for under-the-radar opportunities by reviewing a carefully filtered group of strong fundamentals in the 15 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com