


Learn Why The Bull Case For Calumet Stock Could Change Following Middle East Shipping Attacks
- Calumet, Inc. recently saw renewed investor attention after attacks on Middle East shipping routes and production shut-ins raised concerns about global crude supply tightness and refined product availability.
- The episode highlights how Calumet's refining and specialty products model can become more sensitive to shifts in feedstock costs and refining spreads when supply chains are disrupted.
- This development may influence how investors view Calumet's investment narrative in the context of heightened geopolitical risk to key Middle East crude shipping corridors.
Scan how rising crude prices are rippling across the sector by comparing Calumet with a hand-picked 39 power grid technology and infrastructure stocks.
Calumet Investment Narrative Recap
To own Calumet, you need to believe the mix of specialty products, Montana Renewables and branded performance lines can turn improving efficiency into steadier cash generation. The recent crude spike helps near term refining spreads, but the more meaningful short term catalyst remains execution on cost controls and throughput reliability across all three segments.
The biggest near term risk still sits in Calumet's balance sheet and policy exposure, not in daily oil headlines. High leverage and negative shareholders' equity leave little room for operational missteps. Any adverse change in renewable fuel credits or RVOs would matter more than a temporary move in benchmark crude prices.
Recent attention has focused on Calumet's MaxSAF 150 project, which is guided to start up in the first half of 2026 and target 120 million to 150 million gallons of sustainable aviation fuel a year. That future capacity ties directly into the current conversation about supply security and demand for lower carbon transport fuels.
As crude markets react to Middle East disruptions, the MaxSAF project sits in the background as a key operational swing factor. Execution on construction, feedstock sourcing and regulatory support around credits such as 45Z will shape how valuable this SAF stream becomes as a complement to Calumet's more commodity exposed refining activities.
Calumet's current revenue forecasts point to about 2.4% yearly top line growth, and earnings are projected to move from a loss of US$136.8 million today to US$495.3 million by 2029. This implies an earnings swing of roughly US$632 million alongside a revenue target of US$4.9b in the same year.
Uncover why Calumet's fair value indicates a 6% potential downside to its current price, a premium that may not hold.
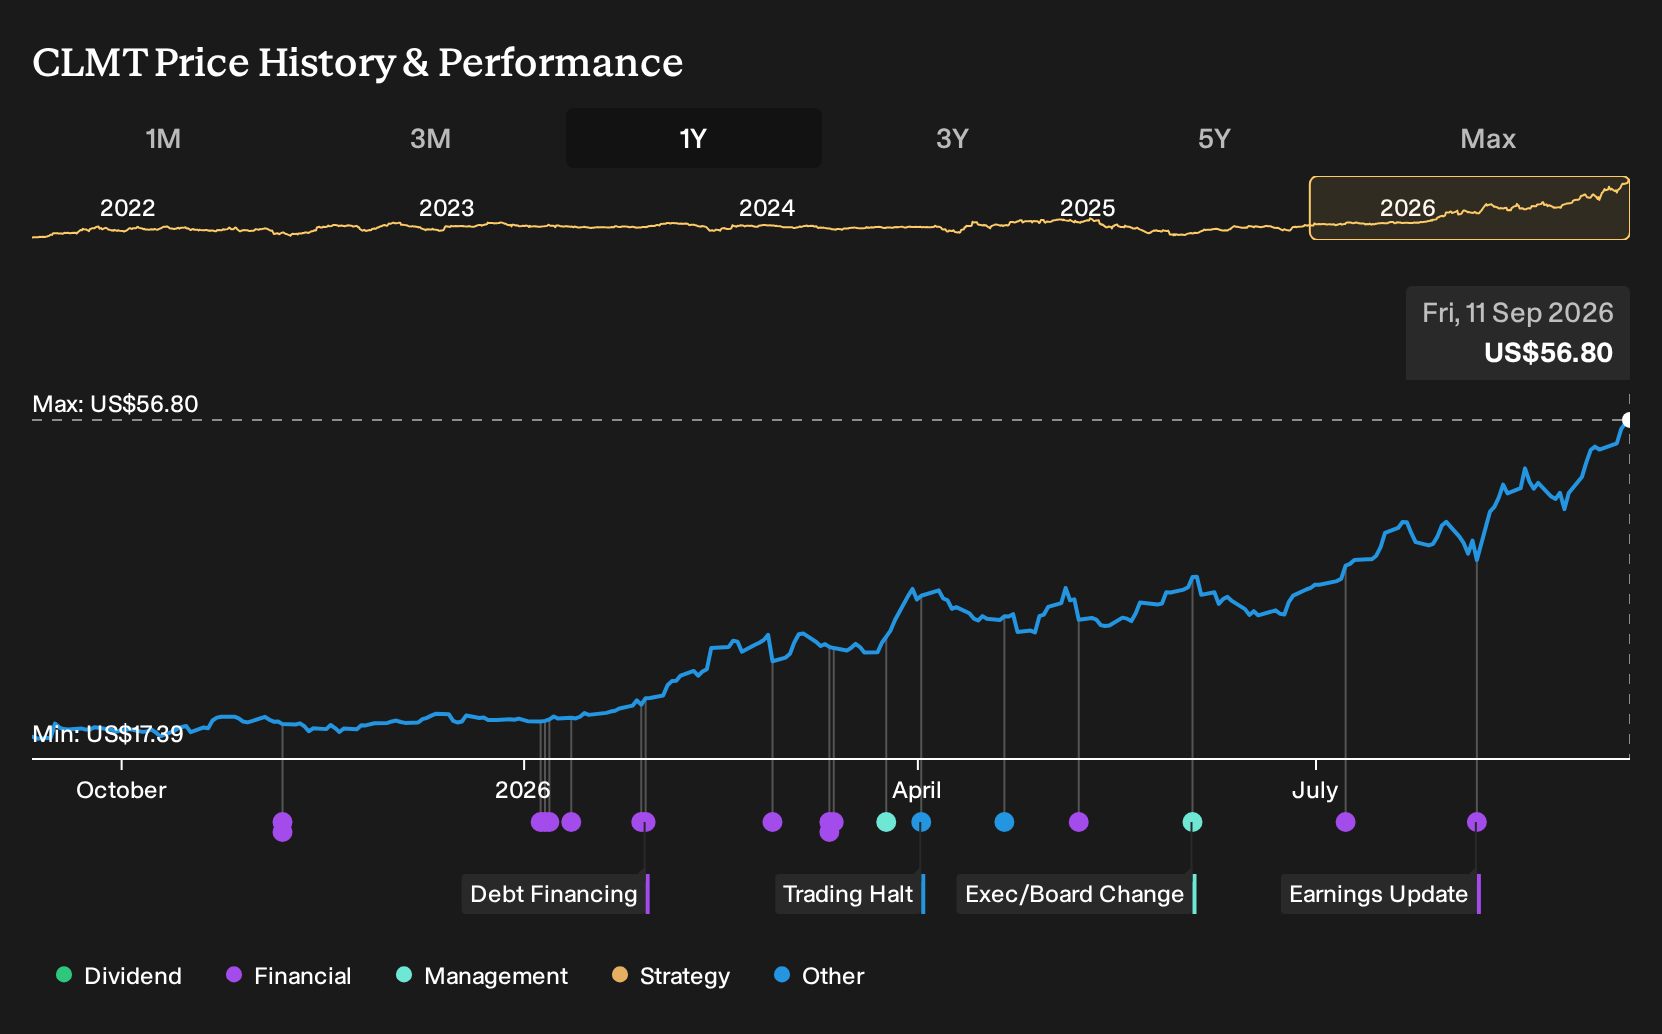
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Calumet’s MaxSAF upside rather than crude shocks. Before these shipping attacks, the bullish camp was modeling revenue to reach about US$6.8b and earnings of roughly US$152.8 million by 2029. You can treat that as one possible path that might shift as this news filters into new forecasts.
Explore another Calumet fair value estimate, including one that suggests up to 6% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Calumet research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Calumet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Calumet's overall financial health at a glance.
Looking For More Investment Ideas Beyond Calumet?
If the Calumet story has you thinking about portfolio balance, it can help to scan a broader watchlist and see how other businesses stack up on quality, value and resilience. The Simply Wall St Screener gives you a way to filter by fundamentals so you are not just reacting to headlines.
- For investors who care most about valuation support, review a 32 high quality undervalued stocks that combine sturdy balance sheets with pricing that still looks disciplined.
- If income reliability is a priority, focus on companies that pay you while you wait by checking out a group of 6 dividend fortresses built around higher yields.
- To keep risk in check while you search for opportunities, sort through a carefully filtered pool of 11 resilient stocks with low risk scores that score well on financial strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com