


FirstEnergy (FE) Could Be 13% Undervalued As Grid Spending Fuels The Narrative
FirstEnergy (FE) has been drawing attention after recent trading left the share price at $46.13, with returns over the past month and past 3 months both drifting lower.
Recent trading suggests that momentum in FirstEnergy’s share price has softened, with the stock easing over the past week and quarter. However, the year to date share price return remains positive and multi year total shareholder returns remain meaningfully higher.
Scan beyond FirstEnergy and see how other utilities with steadier recent trends stack up in the 39 power grid technology and infrastructure stocks.
FirstEnergy has eased back to $46.13 while analyst targets cluster near $53 and one intrinsic estimate points much lower. Where does a sensible view of fair value fall within that range?
Most Popular Narrative: 13% Undervalued
FirstEnergy’s most followed narrative points to a fair value of about $53.23, compared with the recent $46.13 close, so the debate centers on whether data center driven demand and grid spending plans can justify that gap.
Large scale infrastructure modernization and grid hardening initiatives, including the $28 billion investment plan through 2029 and a 15% CAGR in transmission rate base, are described as enabling higher returns on equity, improved reliability, and ultimately enhanced net margins and earnings growth. Constructive regulatory environments in key states (e.g., Pennsylvania and Ohio) with mechanisms such as forward looking base rates and distribution investment surcharges are cited as increasing earnings predictability and supporting consistent growth in cash flow.
See why 14 investors see FirstEnergy as 13% undervalued.
Result: Fair Value of $53.23 (UNDERVALUED)
Still, that 13% upside narrative for FirstEnergy can unravel if legal and regulatory issues resurface, or if heavy grid investment strains cash flow and raises financing pressure.
Find out about the key risks to this FirstEnergy narrative.
Another View on FirstEnergy’s Valuation
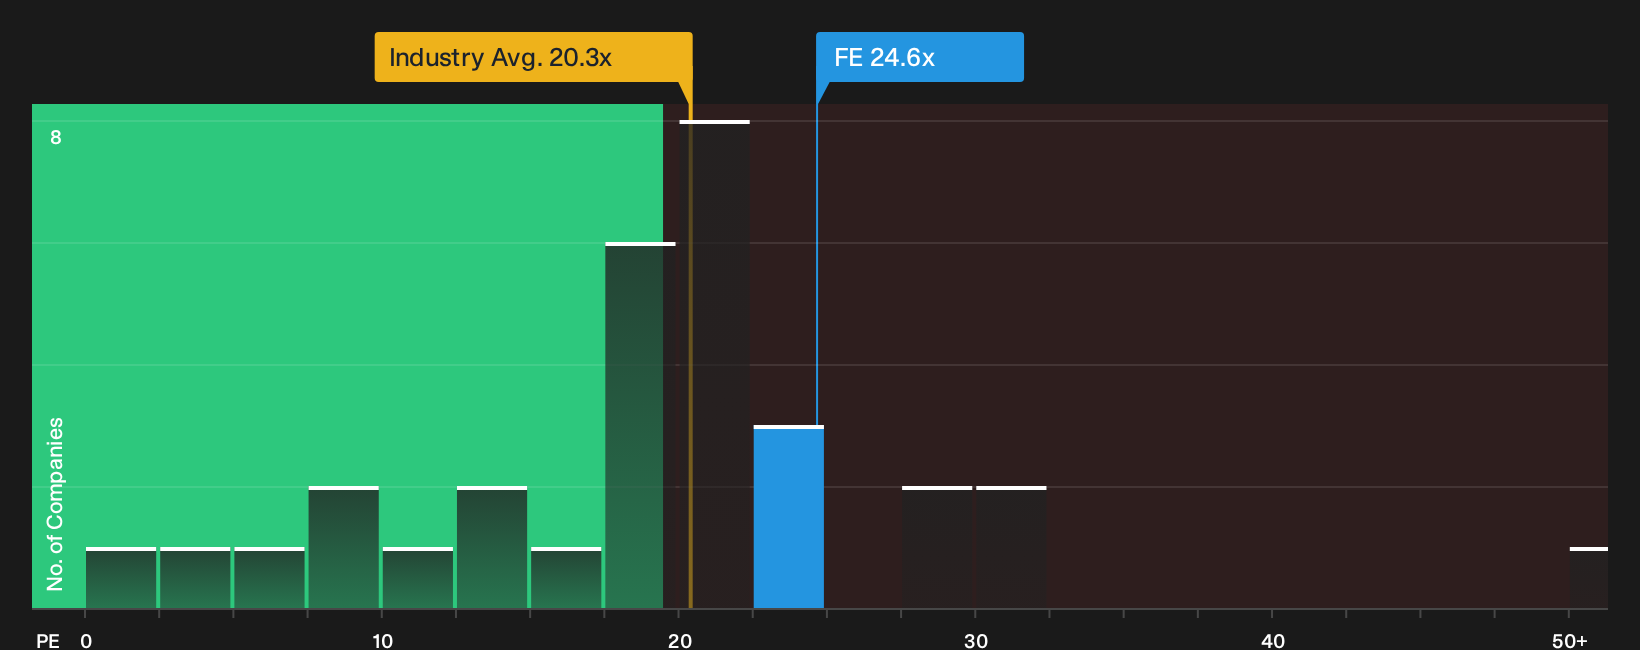
The story looks very different when you switch from that $53.23 fair value narrative to what the current P/E suggests. FirstEnergy trades on about 24.6x earnings, compared with 20.3x for the US electric utilities group and a fair ratio estimate of 22.8x.
That premium means investors are already paying more for each dollar of profit than both peers and the fair ratio suggest. This raises the risk that any disappointment on earnings or regulation could hit the share price harder than a cheaper utility. How comfortable are you with paying up for this grid modernization story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around FirstEnergy’s value and risk can feel messy. Move quickly from noise to evidence and stress test the story yourself using the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond FirstEnergy?
Do not stop with FirstEnergy. Use targeted stock lists to pressure test your portfolio and keep fresh opportunities on your radar before the crowd notices.
- Zero in on potential value opportunities by scanning companies that look mispriced on quality and fundamentals with the 32 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that pair higher yields with resilience using the 6 dividend fortresses.
- Reduce portfolio stress by concentrating on companies with robust finances through the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com