


TransMedics Group (TMDX) Stock May Be Below Fair Value As Earnings Lead
TransMedics Group has given long term holders a powerful ride, with the share price up 179.1% over the past 5 years, even though more recent returns have been weak. With the stock now around US$82.18 after a year in which it has fallen sharply, the question is whether that kind of history is still backed up by the company’s earnings power today.
- A 179.1% gain over 5 years puts real pressure on the current valuation to be supported by what TransMedics Group can earn from its organ transplant platform over a full cycle.
- The business model is capital intensive and heavily tied to clinical adoption, which can affect how quickly reported earnings catch up with past investment and justify the current share price.
- There is a second opinion on TransMedics Group worth weighing. See what analysts think TransMedics Group's shares could be worth.
The stock's next move may depend on whether TransMedics Group's present earnings justify the valuation implied by today’s share price.
If you are considering whether TransMedics Group's recent earnings justify its current share price, it can be helpful to evaluate that question using 32 high quality undervalued stocks for additional context.
Does TransMedics Group Look Undervalued on Earnings?
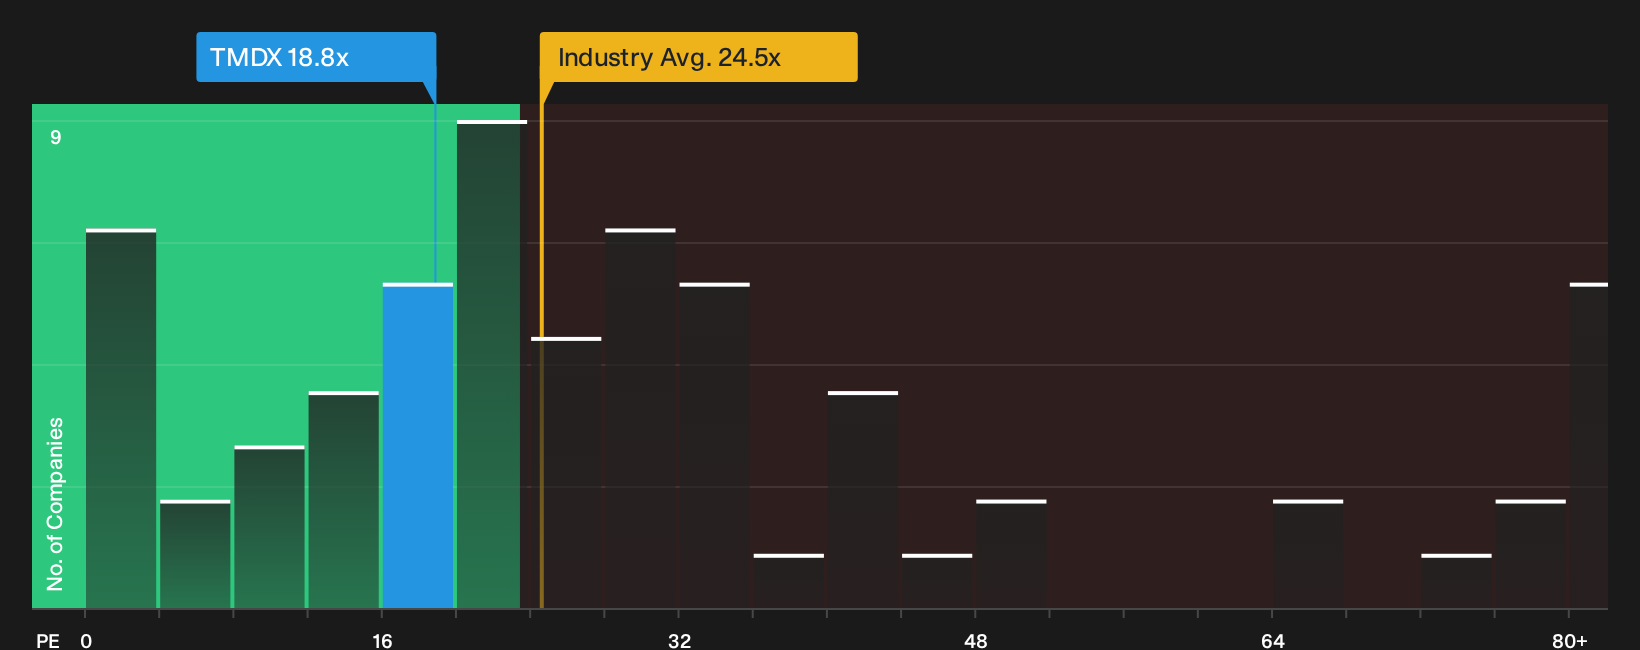
The P/E ratio fits TransMedics Group because investors often focus on how many dollars they are paying for each dollar of current earnings in established healthcare businesses. On this yardstick, TransMedics Group trades on a P/E of about 18.8x, which is lower than the Medical Equipment industry average of roughly 24.5x and also below the peer group near 25.0x. That gap means the current share price implies a smaller earnings multiple than many comparable listed operators in the same space.
The fair P/E that would be expected for TransMedics Group given its profile is higher than where the shares trade today, which indicates the stock appears undervalued on this earnings yardstick. For you as a shareholder or potential buyer, the key question is whether the quality, consistency and risk around those earnings justify any move back toward that richer multiple over time. Explore the numbers behind TransMedics Group's P/E valuation.
The TransMedics Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for TransMedics Group pick up where the P/E discussion leaves off. They spell out which future paths for TransMedics Group's growth, profitability and earnings would need to hold for the stock to be worth significantly more or less than today. Each narrative links its number to a clear view on how revenue expansion, margins and key risks might evolve, giving you something concrete to revisit as fresh information comes through.
Community views on TransMedics Group split between those who see runway left in the story and those who think expectations already stretch the fundamentals.
Bull case: 16% undervalued
"Expansion into new organ types (notably kidney) and next-generation product launches (Gen 3 OCS platforms for heart, lung, and liver) are expected to materially grow TransMedics' total addressable market..."
Discover why this Narrative puts TransMedics Group at 16% undervalued.
Bear case: 26% overvalued
"Increasing healthcare cost controls, reimbursement pressures, and potential moves toward lower-cost or generic alternatives threaten TransMedics' ability to maintain pricing power for its premium technology..."
Explore why this Narrative puts TransMedics Group at 26% overvalued.
For TransMedics Group, who is steering the ship matters as much as what it earns
Before you stop at the share price and earnings multiple, it is worth asking who actually allocates the capital at TransMedics Group and how their pay packets line up with your priorities as a shareholder. See who runs TransMedics Group and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com