


Remitly Payout Deal Might Change The Case For Investing In Etsy (ETSY)
- Remitly Global announced that it partnered with Etsy to become an additional payout option on Etsy Payments in 15 countries, allowing new international sellers to hold earnings in USD and convert to local currencies before moving funds to bank accounts or mobile wallets.
- This extra payout flexibility directly targets friction points for cross border sellers and could influence how Etsy attracts and retains international merchants on its marketplace.
- We will now look at how Etsy's investment narrative could be affected by the added Remitly payout option for new international sellers.
Scan how Etsy compares with a curated list of marketplace-focused platforms and payment-linked plays inside the 15 high quality undiscovered gems to spot other under-the-radar opportunities around similar themes.
Etsy Investment Narrative Recap
Etsy attracts shareholders who think a focused marketplace for unique, creator led products can keep buyer engagement healthy enough to support GMS and earnings over time. For that to hold, the drop in active buyers and GMS per buyer needs to stabilise, while marketing spend starts to translate more cleanly into profitable transactions.
The Remitly payout option looks helpful but not game changing for the near term. It could smooth onboarding for some new international sellers. However, the bigger swing factors still sit with AI driven personalization, app engagement, and whether rising acquisition costs can be brought under control.
The recent insider sale by director Frederick R. Wilson is the announcement that matters most alongside the Remitly news. Wilson sold 20,000 shares under a Rule 10b5 1 plan and still holds 401,329 shares. The planned nature of the trade and remaining ownership base suggest it is an incremental data point rather than a thesis changer.
For you as an investor, that keeps the spotlight squarely on execution. Etsy is working through negative GMS trends, high marketing intensity, and meaningful competition, while also carrying high debt and negative shareholders equity. The real catalysts remain operational proof that AI, loyalty and product work can support buyer activity without eroding margins further.
Etsy's current analyst narrative points to revenues of US$3.2b and earnings of US$538.4 million by 2029. This outlook is built on an assumed 2.8% yearly revenue growth rate and an earnings increase of about US$167 million from earnings today of US$371.4 million.
Uncover how Etsy's fair value indicates a 20% potential upside to its current price that could narrow quickly if Etsy execution improves.
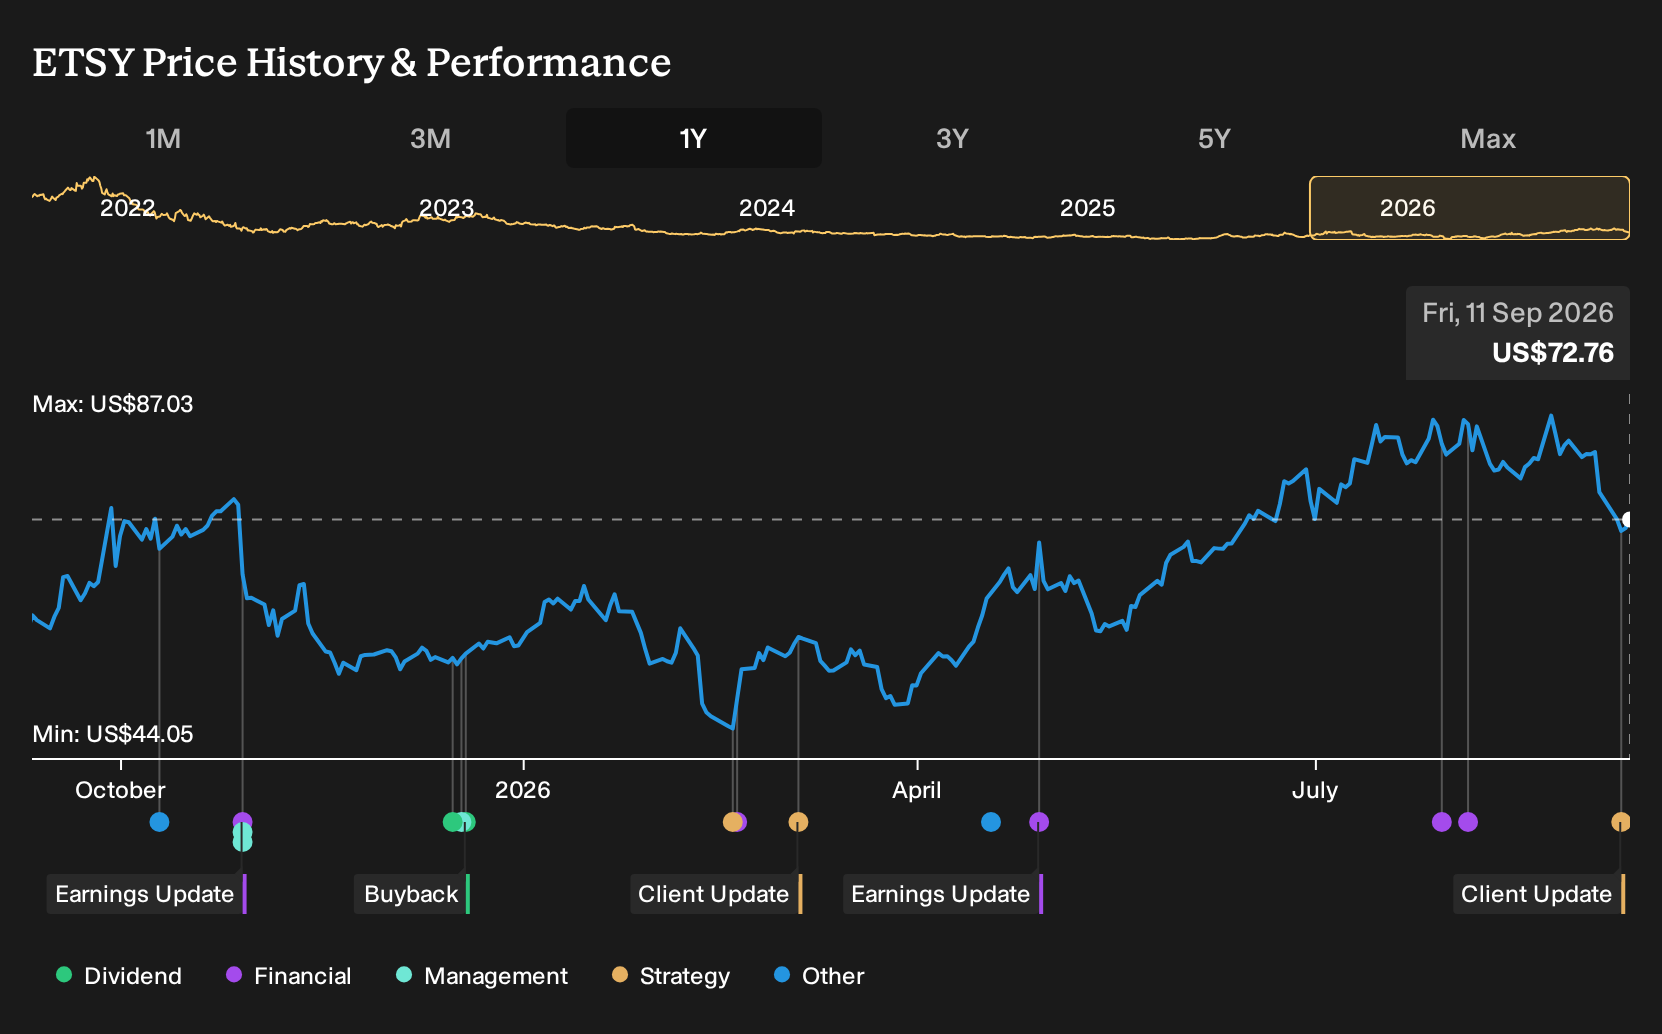
Exploring Other Perspectives
You might see the Remitly partnership and wonder if it supports the more bullish narrative on Etsy. The most optimistic analysts were already modeling revenue of about US$3.3b and earnings near US$653.1 million by 2029. Those forecasts came before this payout tweak, so future revisions could move quite a bit.
Explore 3 other Etsy fair value estimates, including one that suggests potential upside of as much as 113% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Etsy research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Etsy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Etsy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Etsy?
Once you have a view on Etsy, it can help to compare it with other businesses that share similar traits, whether you care most about upside, resilience or income.
- If you are hunting for potential bargains with quality fundamentals, start with companies that screen as 32 high quality undervalued stocks relative to their cash flows and balance sheets.
- If capital preservation matters most to you, focus on businesses that pass our filters for 11 resilient stocks with low risk scores and see which ones line up with your comfort level.
- If you care about stability and income, zero in on companies that show up in the 6 dividend fortresses and then test whether their payouts fit your objectives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com