


Is Baidu (BIDU) A Bargain Or Fully Priced On Its AI Narrative?
Baidu (NasdaqGS:BIDU) has been under pressure recently, with the share price closing at US$91.40 and the trailing 1-year total return down about 20% for investors.
For Baidu, recent trading has been heavy on downside momentum, with the share price return down 11.8% over the past month and 39.2% year to date, while the 1 year total shareholder return has fallen 20.4%, signaling that sentiment has weakened both in the short term and over a longer holding period.
Scan Baidu alongside hand picked Chinese tech peers under pressure, and see which ones still screen well on quality and valuation using our 32 high quality undervalued stocks
Baidu now trades roughly 40% below analyst price targets after a sharp slide this year, so the key issue is whether that discount reflects mispricing or justified caution on the fundamentals.
Most Popular Narrative: 38% Undervalued
The most followed narrative currently pegs Baidu's fair value around $146.50 compared with the recent $91.40 close, which points to a wide gap that investors need to judge against the underlying AI and cloud thesis.
The rapid rise in digitalization and urbanization across China is fueling increased engagement with online platforms and services, creating a larger addressable market for Baidu's AI-powered products. This secular shift underpins continued growth potential in core search, cloud, and new digital services, which could support revenue upside as AI monetization progresses.
See why 172 investors see Baidu as 38% undervalued.
Result: Fair Value of $146.50 (UNDERVALUED)
Still, Baidu's narrative can crack if advertising weakness persists and heavy AI spending keeps margins under pressure longer than analysts currently model.
Find out about the key risks to this Baidu narrative.
Another View On Baidu’s Value
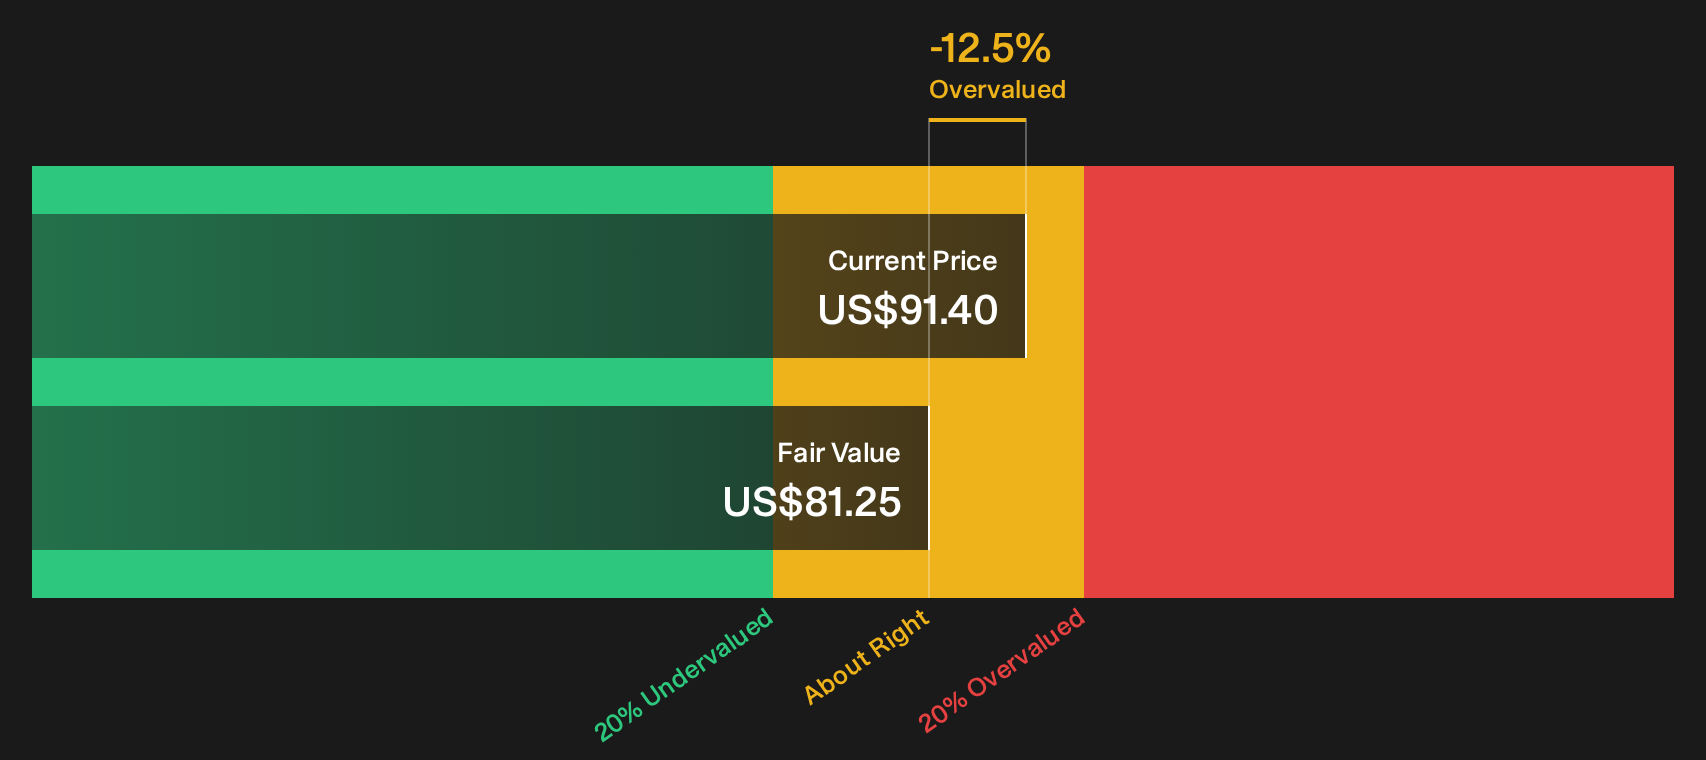
The first narrative leans on analyst targets that imply Baidu is significantly undervalued. A different perspective comes from Simply Wall St's DCF work, which suggests the shares at $91.40 trade above an estimated future cash flow value of about $81.25, indicating that the stock appears overvalued on that metric.
If the SWS DCF model is accurate and Baidu is pricing in more cash flow than the model supports, investors are left asking which story to trust: the more optimistic analyst fair value or the more cautious cash flow analysis.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Baidu for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Baidu is clearly split, so move fast, pull up the same numbers and pressure test both the bullish and cautious narratives for yourself. To understand what optimistic investors are focusing on, start by reviewing the 1 key reward.
Looking for more Baidu investment ideas?
If Baidu has your attention, do not stop here. Broaden your watchlist now and compare it with other targeted opportunities so you are not late to the next move.
- Spot potential turnaround plays early by reviewing the 21 elite penny stocks with strong financials that already clear strict financial quality checks.
- Strengthen your core holdings by scanning a focused list of solid balance sheet and fundamentals (23 results) that can complement or offset Baidu's risk profile.
- Hunt for future leaders before the crowd notices by running through a curated 15 high quality undiscovered gems that meet tight fundamental filters.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com