


Asian Value Stocks Estimated Below Intrinsic Worth In September 2026
In September 2026, the Asian markets have been navigating a complex environment characterized by geopolitical tensions and fluctuating energy prices, which have contributed to inflation concerns and influenced investor sentiment. Amidst these challenges, identifying undervalued stocks becomes crucial as investors seek opportunities that are priced below their intrinsic worth, offering potential for growth when market conditions stabilize.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Thai Vegetable Oil (SET:TVO) | THB27.00 | THB51.97 | 48% |
| Shizuki Electric (TSE:6994) | ¥1144.00 | ¥2275.72 | 49.7% |
| PAL GROUP Holdings (TSE:2726) | ¥1481.00 | ¥2861.24 | 48.2% |
| Niterra (TSE:5334) | ¥7205.00 | ¥13730.39 | 47.5% |
| Nickel Asia (PSE:NIKL) | ₱4.54 | ₱8.59 | 47.2% |
| Leopalace21 (TSE:8848) | ¥657.00 | ¥1302.96 | 49.6% |
| Ichikoh Industries (TSE:7244) | ¥554.00 | ¥1067.46 | 48.1% |
| CMOC Group (SHSE:603993) | CN¥18.15 | CN¥36.10 | 49.7% |
| BuySell TechnologiesLtd (TSE:7685) | ¥2800.00 | ¥5554.24 | 49.6% |
| AK Medical Holdings (SEHK:1789) | HK$4.915 | HK$9.61 | 48.8% |
Let's uncover some gems from our specialized screener.
Sakata Seed (TSE:1377)
Overview: Sakata Seed Corporation is engaged in the production and sale of vegetable and flower seeds, bulbs, plants, and agricultural supplies across various regions including Japan, the Americas, Europe, the Middle East, and Asia with a market cap of ¥184.25 billion.
Operations: The company's revenue primarily comes from its Overseas Wholesale Business, which generated ¥84.90 billion, and its Domestic Wholesale Business, contributing ¥13.85 billion.
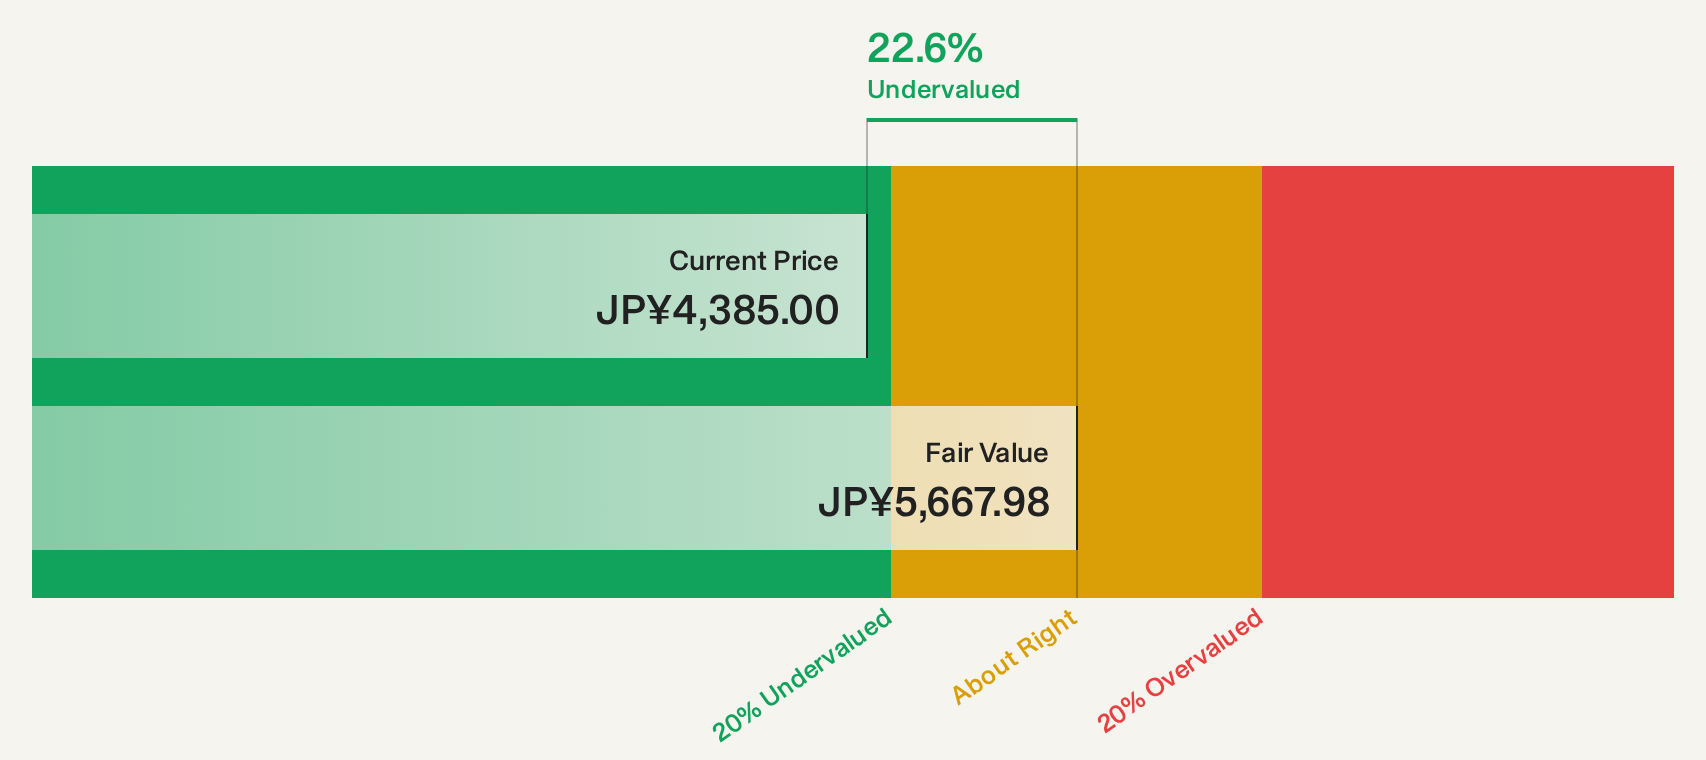
Estimated Discount To Fair Value: 23.1%
Sakata Seed is trading at a good value, with its current price of ¥4,360 below the estimated future cash flow value of ¥5,667.98. Although earnings are expected to grow slower than the market at 1.5% annually, recent profit growth was strong at 25.2%. The company has initiated a share buyback program and increased dividends consistently; however, dividend sustainability remains a concern due to limited free cash flow coverage.
- Our growth report here indicates Sakata Seed may be poised for an improving outlook.
- Click here to discover the nuances of Sakata Seed with our detailed financial health report.
Maxell (TSE:6810)
Overview: Maxell, Ltd. is engaged in the manufacturing and sale of energy products, functional materials, optics and systems, and value co-creation solutions across Japan and international markets with a market cap of ¥92.19 billion.
Operations: The company's revenue segments include Energy at ¥47.81 billion, Optics & Systems at ¥37.78 billion, Functional Materials at ¥34.38 billion, and Value Co-Creation Businesses at ¥17.31 billion.
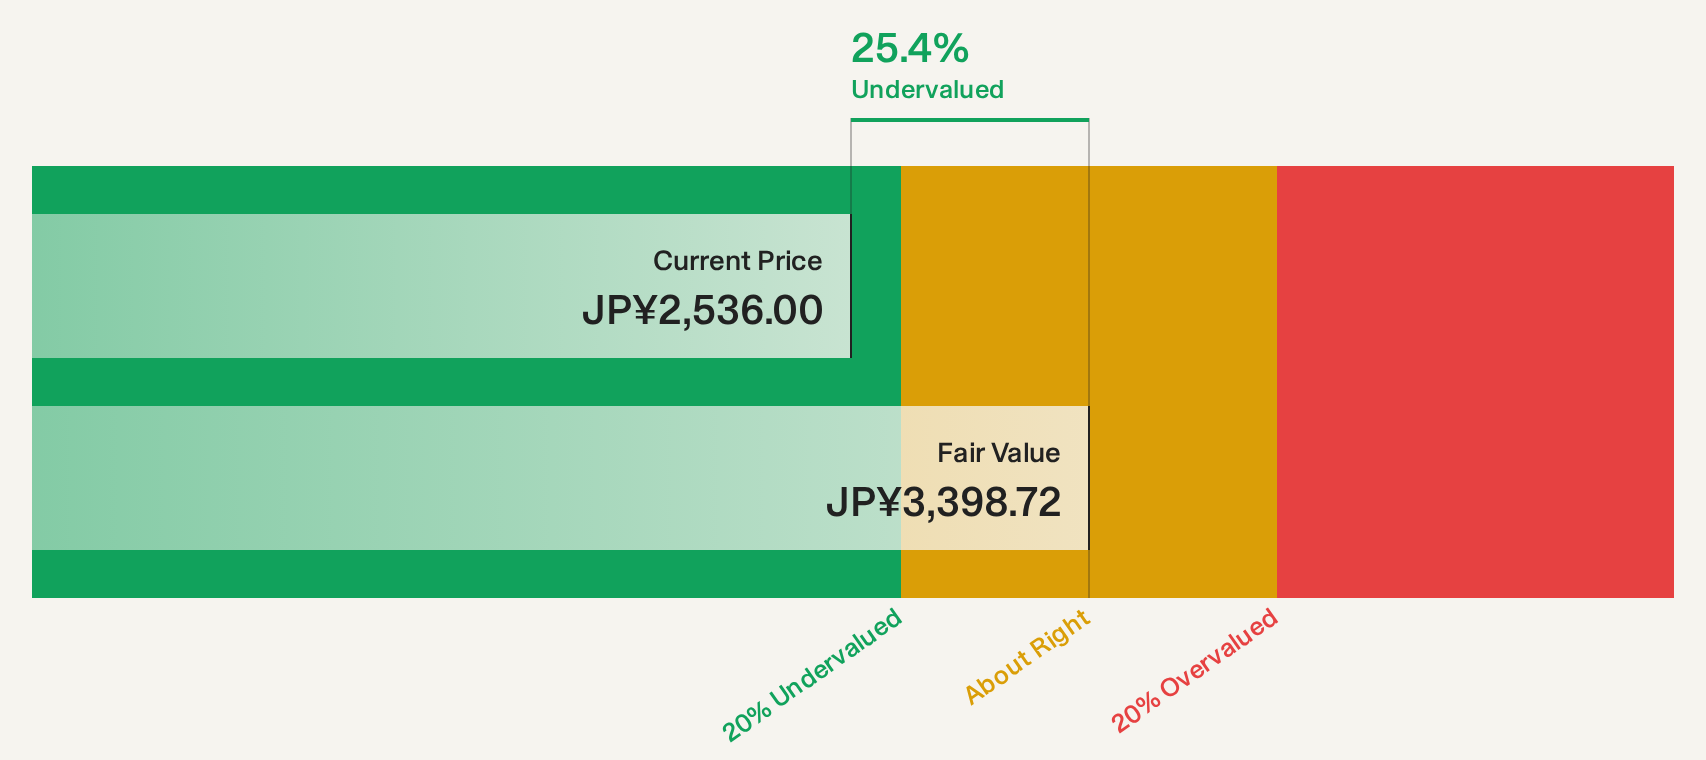
Estimated Discount To Fair Value: 25.9%
Maxell is trading at ¥2,501, significantly below its estimated future cash flow value of ¥3,372.95, indicating it is undervalued by more than 20%. Despite a volatile share price recently and slower forecasted revenue growth than the market, earnings have grown substantially by 160.8% over the past year. Recent innovations in all-solid-state battery technology could enhance operational efficiency and reduce waste in industrial applications, potentially supporting future financial performance improvements.
- The analysis detailed in our Maxell growth report hints at robust future financial performance.
- Take a closer look at Maxell's balance sheet health here in our report.
Leopalace21 (TSE:8848)
Overview: Leopalace21 Corporation, with a market cap of ¥208.76 billion, operates in Japan through its subsidiaries by constructing, leasing, and selling apartments, condominiums, and residential housing.
Operations: The company's revenue primarily comes from its Leasing Business, including development activities, which generated ¥433.78 billion, complemented by the Elderly Care Business contributing ¥13.64 billion.
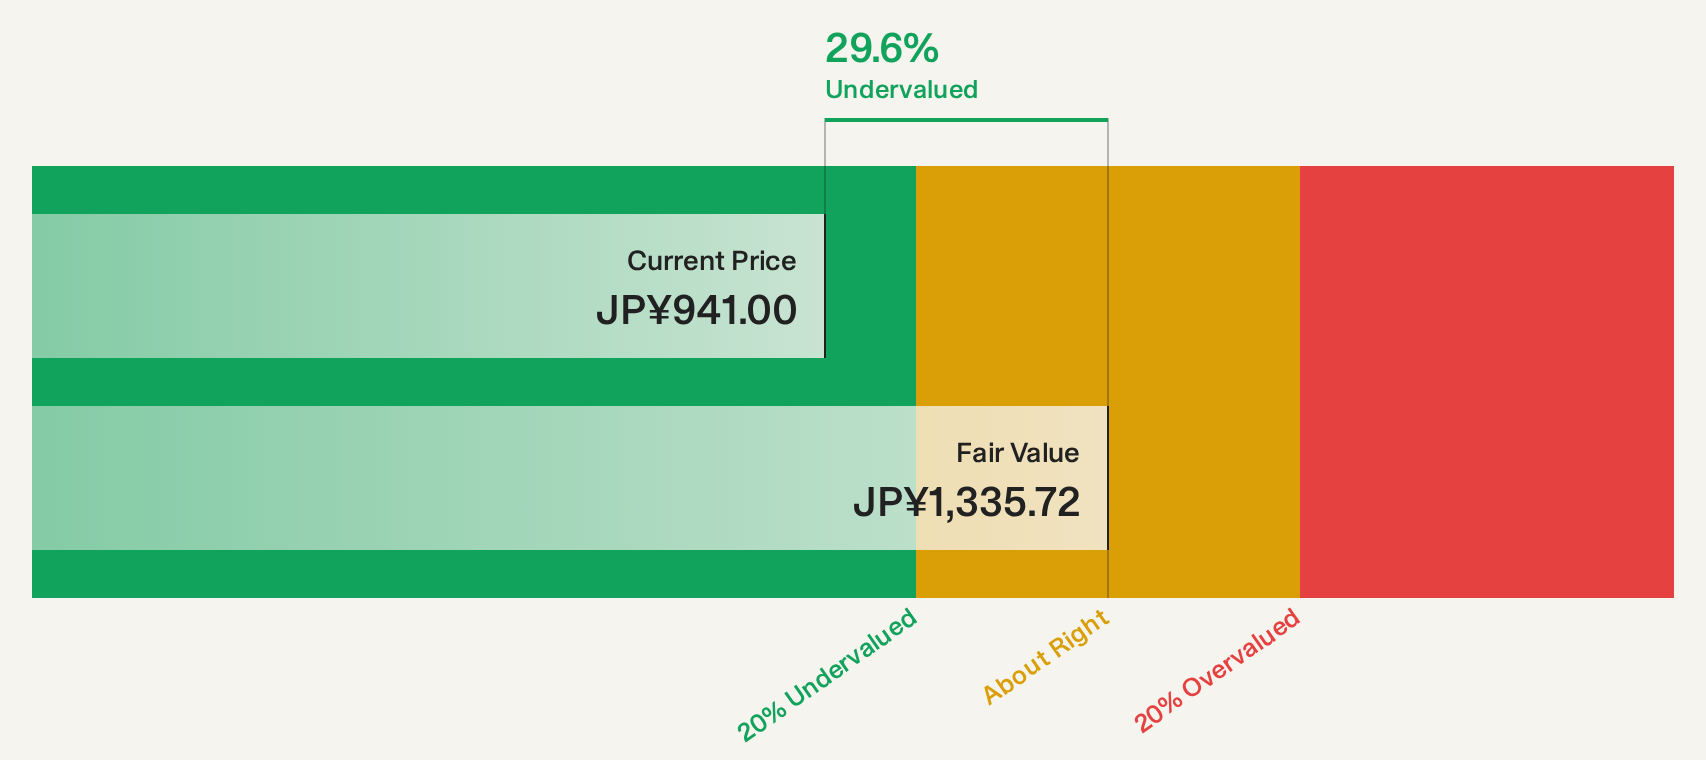
Estimated Discount To Fair Value: 49.6%
Leopalace21 is trading at ¥657, significantly below its estimated future cash flow value of ¥1,302.96, reflecting a substantial undervaluation. The company reported impressive earnings growth with net income rising to ¥7.03 billion from ¥555 million year-on-year for Q1 2026. Despite slower revenue growth forecasts compared to the market and an unstable dividend track record, Leopalace21's high forecasted return on equity and strong recent earnings performance highlight its potential as an undervalued investment based on cash flows.
- Our earnings growth report unveils the potential for significant increases in Leopalace21's future results.
- Unlock comprehensive insights into our analysis of Leopalace21 stock in this financial health report.
Summing It All Up
- Take a closer look at our Undervalued Asian Stocks Based On Cash Flows list of 91 companies by clicking here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com