


DorianG (LPG) Secures Fresh Funding And Newbuilds As Investors Ask If Shares Are Fully Valued
DorianG (LPG) has just paired a new seven year US$368.4 million credit facility with a US$345 million order for three dual fuel Panamax VLGCs, tying financing directly to fleet renewal and greener shipping capacity.
DorianG’s dual announcement comes after a powerful run in the stock, with a 30-day share price return of 16.5% and a year-to-date share price gain of 123%. This outpaces its already strong 1-year total shareholder return of 91.2% and very large 5-year total shareholder return, suggesting that momentum has been building as investors reassess both the growth potential and risk around its LPG shipping fleet and funding mix.
Scan how DorianG compares with other shipping and energy plays by reviewing our hand picked list of 15 high quality undiscovered gems that have strong fundamentals but less headline attention.
DorianG has already rewarded anyone who was in before this latest surge, while new buyers now face a very different entry point. Is the recent jump already pricing in the fleet upgrade and fresh credit line, or not yet?
Most Popular Narrative: 1% Overvalued
DorianG last closed at $55.18 compared with a narrative fair value of $54.60. The current quote sits slightly above that framework while still leaning heavily on long term shipping and decarbonization themes.
The increasing role of LPG as a lower-carbon "transition fuel" and as an economically attractive marine fuel (especially for dual-fuel vessels) is expected to support steady or rising shipping volumes and favorable charter rates, bolstering long-term earnings and net margins.
DorianG's ongoing investments in enhancing fleet energy efficiency, retrofitting vessels for ammonia carriage, and early compliance with IMO decarbonization targets position the company to benefit from tightening environmental regulations, supporting improved margins and lower compliance costs.
See why 40 investors see DorianG as 1% overvalued.
Result: Fair Value of $54.60 (OVERVALUED)
Still, the DorianG narrative can be knocked off course if geopolitical shocks hit LPG trade routes or if an oversupplied VLGC market forces weaker spot rates.
Find out about the key risks to this DorianG narrative.
Another View On DorianG’s Valuation
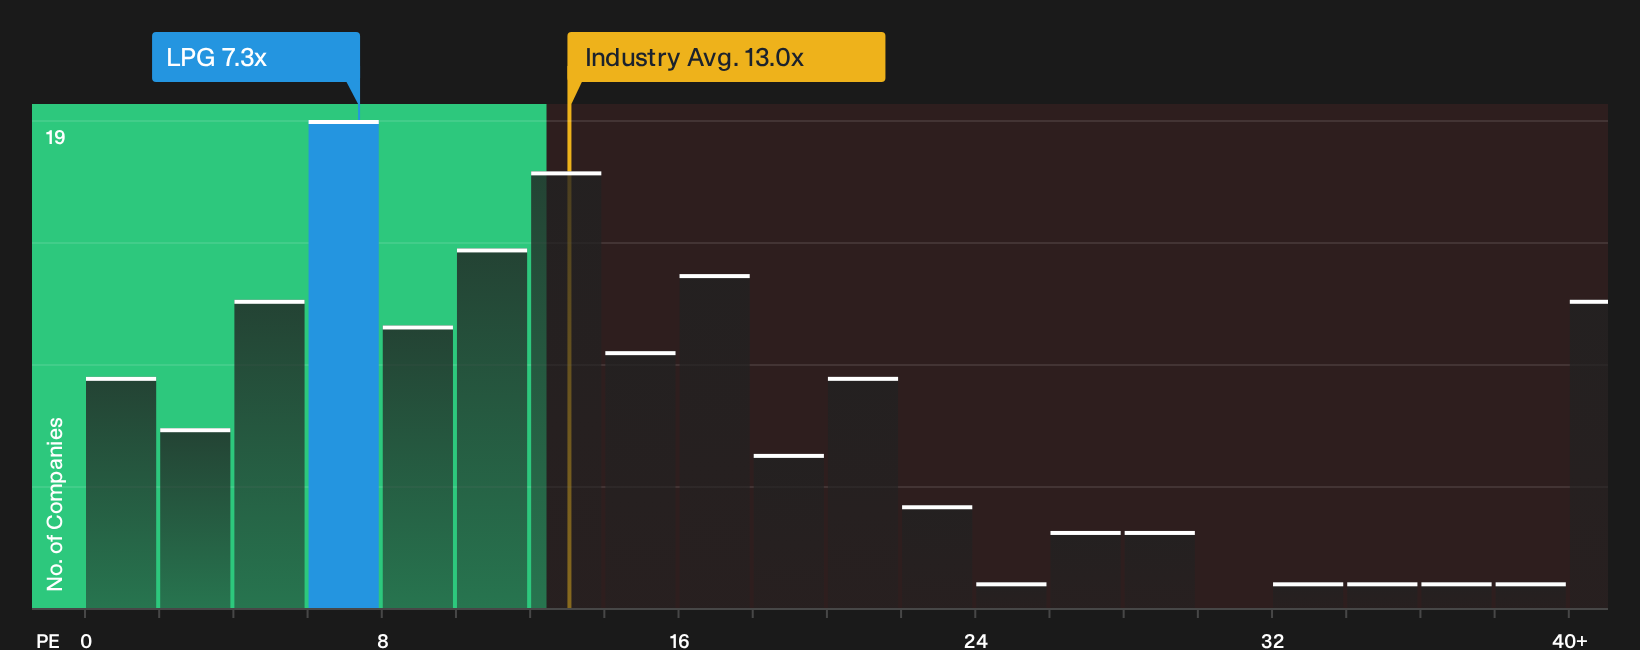
The fair value narrative pegs DorianG as slightly overvalued at $54.60, yet the current P/E of 7.3x tells a different story. That multiple is far below the US Oil and Gas industry on 13x and well under peers on 19.3x, while still sitting above a fair ratio of 3.7x that the market could move toward over time. That kind of gap raises a basic question for you as an investor: is the risk that sentiment compresses the P/E further or that it drifts closer to the wider sector?
To see how this valuation stacks up against the sector and where the numbers could shift next, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on DorianG is split. This is exactly when it can help to move fast, stress test the numbers, and reach your own verdict using the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond DorianG?
If DorianG has sharpened your focus, do not stop here. The next opportunity you research could be the one that reshapes your whole portfolio.
- Target potential mispricing by reviewing companies on the 32 high quality undervalued stocks that pair quality fundamentals with lower market expectations.
- Prioritise resilience and support a more stable approach by checking the 11 resilient stocks with low risk scores that screen for sturdier balance sheets and cleaner risk profiles.
- Strengthen your income stream by scanning the 6 dividend fortresses that highlight higher yielding payouts with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com