


CrowdStrike (CRWD) Stock Could Be Pricey After Fresh AI Security Launches
CrowdStrike Holdings has delivered a very strong run over the past three years, yet the current valuation checks say the stock screens as expensive rather than a clear bargain.
- The share price return over three years is about 4x, which puts extra pressure on today’s valuation assumptions to hold up.
- Extensive product launches around AI security and broad partnerships can support high expectations, while any reset in how investors view growth or cyber risk could hit a richly priced stock hard.
- The firm scores 0 out of 6 on a broad valuation scorecard, which means CrowdStrike is not screening as a clear value opportunity on these checks.
The stock's next move may depend on whether CrowdStrike's current price already fully reflects these ambitious expectations for the business.
Spot potential CrowdStrike peers by scanning hand picked cybersecurity and AI infrastructure opportunities in the 89 AI infrastructure stocks.Does CrowdStrike Holdings Look Pricey on Sales?
Price to sales suits CrowdStrike Holdings because the business is still framed more by revenue scale than by conventional earnings metrics.
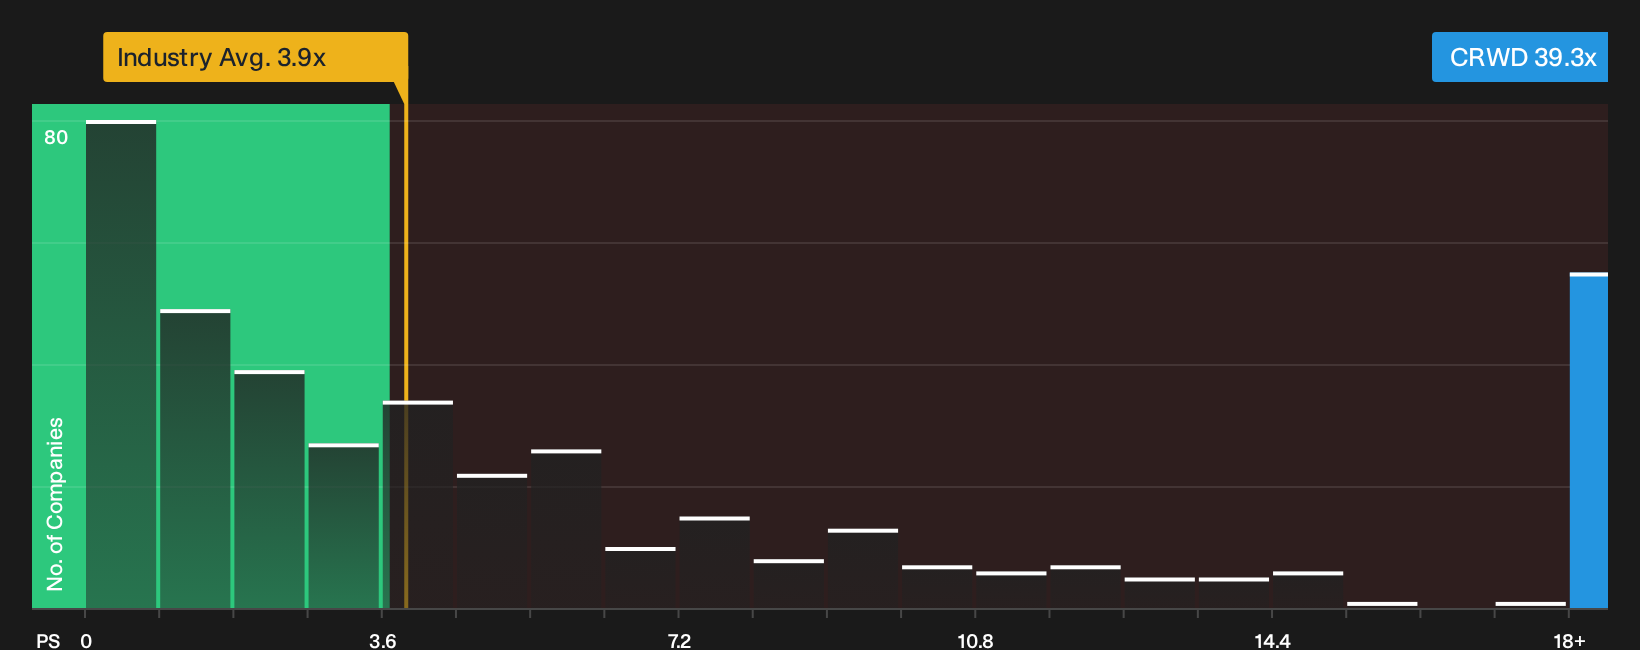
The stock trades on a P/S ratio of about 39.3x, compared with a Software industry average near 3.9x and a peer group average around 13.6x. That is a very steep premium to both the wider sector and closer comparables. On Simply Wall St's fair ratio of roughly 17.4x, which attempts to adjust for factors such as growth profile, margins, size and risk, CrowdStrike still appears expensive relative to that benchmark.
Recent headlines around new AI security tools and high profile partnerships keep attention on CrowdStrike's growth story. However, the current P/S multiple already reflects a significant level of optimism when compared with typical software valuations.
On this sales based yardstick, CrowdStrike Holdings appears overvalued compared with both its sector and a tailored fair multiple.
See what the numbers say about this price — find out in our valuation breakdown.
The CrowdStrike Holdings Narrative: What Would Justify Today's Price?
CrowdStrike Holdings' high P/S ratio raises a clear question for investors. Simply Wall St Narratives sit on the Community page and explain what kind of future growth, profit margins and earnings power would need to occur for the stock to be worth materially more or less than it is today. Each scenario links a fair value estimate to a specific set of catalysts and risks so you can track which storyline moves closer to reality over time.
Community narratives around CrowdStrike could hardly be further apart, with one camp arguing the stock is materially undervalued and another seeing it as priced ahead of itself.
Bull case: 19% undervalued
"The company's accelerating success in the Managed Security Service Provider channel, now over 15% of new bookings compared to single digits two years ago, is transforming CrowdStrike into an indispensable platform for the mid-market and public sector…"
Read the full Bull Case to see why CrowdStrike Holdings could be undervalued
Bear case: 7% overvalued
"Any failure to successfully execute the Falcon Flex subscription model or to maintain high customer retention rates could negatively affect the company's ARR growth and long-term revenue projections…"
Read the full Bear Case to see why CrowdStrike Holdings could be overvalued
Do you think there's more to the story for CrowdStrike Holdings? Head over to our Community to see what others are saying!
The Bottom Line
CrowdStrike Holdings currently screens as overvalued on market multiples, with the share price implying very strong expectations for revenue scale and profitability. That premium can persist if investors stay confident in the company’s role in cybersecurity and AI security, yet any shift in sentiment around growth or risk appetite could pressure the valuation quickly. The crux of the debate is simple: it is whether CrowdStrike can keep justifying this rich multiple through execution, or whether the rating eventually normalizes closer to sector norms.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com